
Why Key Man Insurance Coverage is Essential for Business Survival
Key man insurance coverage is a life or disability policy a business buys on a crucial employee—someone whose absence would cause significant financial harm. If that key person dies or can’t work, the business receives a payout to cover lost revenue, hire a replacement, pay debts, or maintain operations during the transition.
Quick Answer:
- What it is: Insurance on a critical employee where the business is the beneficiary.
- Who needs it: Companies dependent on specific individuals (owners, top salespeople, experts).
- What it covers: Death, disability, or critical illness of the key person.
- Benefits: Covers lost profits, replacement costs, debt payments, and business continuity.
Here’s a sobering fact: 99% of businesses have at least one key person, yet only 18% have insurance to cover them. This gap leaves most companies vulnerable. Whether you’re a small business in Victorville or a growing company in Southern California, protecting your human capital is as vital as insuring physical assets.
I’m Ryan McEachron, CEO of ISU Insurance Services ARMAC Agency in Victorville. I’ve helped countless local businesses implement key man insurance coverage to protect their operations, and I’ve seen how it can mean the difference between survival and closure.
What is Key Person Insurance and Why is it Crucial?
Key man insurance coverage is a financial safety net for your business. It protects your company from the financial devastation that could follow if a crucial employee dies, becomes disabled, or suffers a critical illness. Your most valuable assets are the people who drive sales, manage operations, and maintain investor confidence. Losing one can have an immediate and severe impact.
For most businesses in Victorville, Apple Valley, and Hesperia, surviving the loss of a key person without significant financial strain is unlikely. The foundation of this coverage is insurable interest, meaning your business must prove it would suffer a measurable financial loss if the insured person were gone. You can’t insure just anyone; there must be a quantifiable business risk. Learn more about how this works by reading What is Keyman Insurance?.

Who is Considered a ‘Key Person’?
A key person is anyone whose absence would cause your business serious financial harm due to their unique skills, relationships, or knowledge. This isn’t limited to the CEO or founder. It can include:
- C-suite executives providing strategic leadership.
- High-performing sales staff with vital client relationships.
- Employees with unique technical skills or patents.
- Founders with critical vision and industry connections.
- Individuals essential for securing financing.
The common thread is that their contribution is not easily duplicated, and their absence would mean lost revenue, higher costs, or operational halts.
The Importance of Protecting Your Business
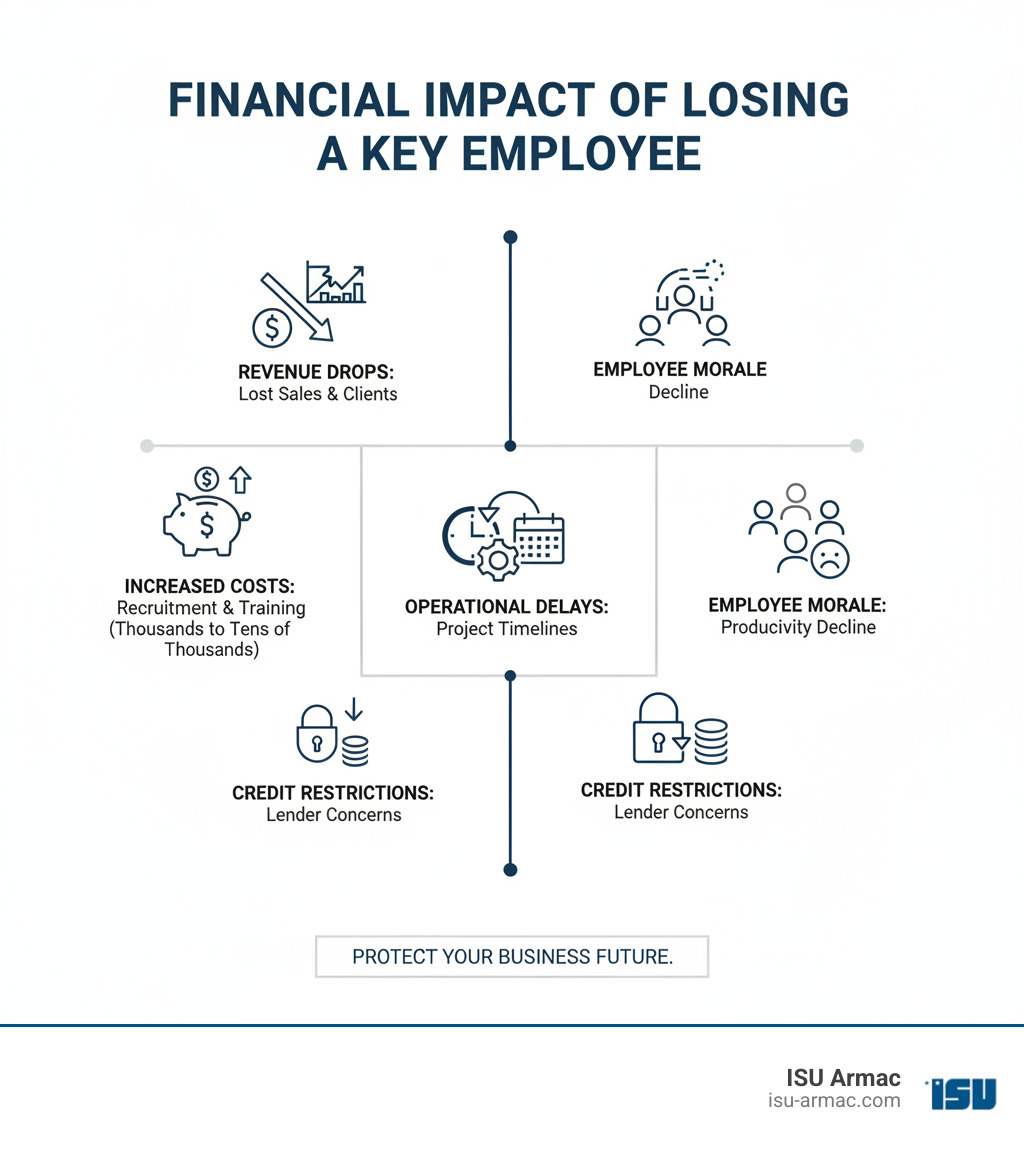
Research shows that almost half of businesses would fail if a key person dies or becomes critically ill—a coin flip for business survival. Without protection, problems cascade: stakeholders lose confidence, and creditors may restrict credit or call in loans, especially if the key person guaranteed them. A real-world example saw a business fail after its owner’s unexpected death because it couldn’t absorb the financial loss.
Key man insurance coverage provides the funds to offset lost profits, cover recruitment costs, pay off debts, and reassure everyone that you have a plan for a smooth transition. It buys you invaluable time to adapt and stabilize without the threat of financial collapse. At ISU Armac, we’ve seen this protection make the difference for businesses across Southern California.
How Key Person Insurance Works and Its Primary Benefits
The mechanics of key man insurance coverage are straightforward. Your business purchases a policy on a key employee, pays the premiums, and is named the beneficiary. Unlike personal life insurance, where the payout goes to family, this policy protects the business. When the insured person dies or becomes disabled (depending on the policy), the business files a claim and receives the funds directly. This quick access to capital provides breathing room to reorganize and recover. Explore the Benefits of Keyman Insurance for a more comprehensive look.

Primary Benefits for Business Stability
The payout from key man insurance coverage is strategic working capital. It helps your business:
- Cover lost profits: When a key person is gone, revenue often drops. The payout cushions this blow, allowing you to maintain operations.
- Fund recruitment and training: Finding and training a replacement is expensive and time-consuming. The funds cover these costs.
- Pay off business debts: If a key person guaranteed loans, their absence could trigger clauses that put your credit at risk. The payout can settle these obligations.
- Facilitate buy-sell agreements: The proceeds can fund the purchase of a deceased or disabled partner’s ownership stake, allowing remaining owners to maintain control.
- Reassure stakeholders: The funds show customers, employees, and investors that the business is stable and has a plan, restoring confidence.
Using Key Person Insurance for Business Loans
Key man insurance coverage is a powerful tool for securing financing through collateral assignment. Here’s how it works: you assign a portion of the policy’s death benefit to a lender as collateral. If the key person dies before the loan is repaid, the lender is paid first from the proceeds, with the remainder going to your business.
This arrangement reduces the lender’s risk, making them more willing to extend credit. It’s often a requirement for securing SBA loans and is looked upon favorably by traditional banks. It also protects personal guarantors; if something happens to you, the policy can repay the loan, removing the liability from your estate.
We help business owners in the High Desert structure these policies correctly. Learn more by visiting our page on the Assignment of Keyman Insurance Policy. Securing this protection beforehand gives you leverage in loan negotiations.
Types of Key Man Insurance Coverage and How Much You Need
Key man insurance coverage isn’t one-size-fits-all. The right protection depends on your specific risks and what losing a key person would cost. The main types are life, disability, and critical illness insurance, which can be combined for a comprehensive safety net. We can help you steer these choices and determine How Much Keyman Insurance Do I Need?.
Key Person Life Insurance
This is the most common form of key man insurance coverage. If a key person dies, the policy pays a death benefit to the business. There are two main types:
- Term life insurance: Covers a specific period (e.g., 10-30 years). It’s more affordable and ideal for temporary risks, like covering the duration of a business loan.
- Permanent life insurance: Offers lifelong coverage and builds tax-deferred cash value over time. This cash value becomes a business asset that can be accessed if needed.
Both options provide funds to help your business recover. For more details, see our page on Life Insurance on Key Employees.
Key Person Disability Insurance
A key person is more likely to become disabled than to die unexpectedly, making this coverage crucial. If a key employee becomes totally disabled and cannot work, this policy provides monthly benefit payments to the business, typically for 12 or 24 months. This provides vital cash flow during the transition. Policies have an elimination period (usually 60-90 days) before benefits begin. This coverage addresses a probable risk many businesses overlook. Learn more about Key Person Disability Insurance.
Determining the Right Coverage Amount
How much key man insurance coverage do you need? There’s no magic number, but several methods can provide a solid estimate.
| Method | Description | Example |
|---|---|---|
| Salary Multiplier | 8-10 times annual salary | $100,000 salary = $800,000-$1,000,000 coverage |
| Profit Contribution | Annual revenue impact × years to replace | $1M annual sales × 2 years = $2,000,000 coverage |
| Cost-to-Replace | Recruitment + training + lost business | $50,000 search + $100,000 training + $500,000 lost business = $650,000 coverage |
| Business Debt | Outstanding loans and obligations | $750,000 in business loans = $750,000 minimum coverage |
These methods—the salary multiplier, profit contribution, cost-to-replace, and business debt coverage—help quantify the financial impact of losing a key person. At ISU Armac, we work with businesses in Victorville, Apple Valley, and Hesperia to find the right amount of coverage that balances protection with manageable premiums.
Costs, Taxes, and Limitations of Key Person Policies
Understanding the costs, taxes, and limitations of key man insurance coverage is essential. We help business owners in the High Desert steer these details to avoid surprises. For a breakdown of potential expenses, visit our guide on How Much Does Keyman Insurance Cost?.
Factors That Influence Insurance Costs
Premiums for key man insurance coverage are determined by an underwriting process that assesses risk. Key factors include:
- The insured person’s age, health, gender, and medical history. Younger, healthier individuals typically receive lower rates.
- Lifestyle and hobbies. Risky activities like skydiving or smoking will increase costs.
- Occupation risks. Hazardous jobs may lead to higher premiums.
- Policy type and coverage amount. Term life is cheaper than permanent life, and higher coverage amounts mean higher premiums.
Tax Implications for Your Business
While you should always consult a tax professional, the general tax rules for key man insurance coverage are straightforward:
- Premiums are not tax-deductible. They are paid with after-tax dollars.
- The death benefit is generally received tax-free. This provides a significant influx of capital to your business without a tax burden.
- Cash value growth is tax-deferred in permanent policies. Taxes are not due until funds are withdrawn.
For more detailed information, please visit our guide: How is Keyman Insurance Taxed?.
Common Limitations and Exclusions
Key man insurance coverage is a powerful tool, but it’s important to know what it doesn’t cover. The policy will not pay out for:
- Employee resignation or job changes. It does not cover voluntary departures.
- Planned retirement. The policy is for unexpected losses, not planned transitions.
- Non-crucial employees or independent contractors. Coverage is reserved for employees whose absence would cause significant financial harm.
Like all policies, there are specific exclusions written into the contract. It is vital to read your policy documents carefully and ask questions to understand the full scope of your protection.
Frequently Asked Questions about Key Person Insurance
Business owners in Southern California often have questions about key man insurance coverage. We’ve compiled answers to the most common ones to provide clarity. For more general inquiries, visit our page on Key Employee Insurance.
How does key person insurance differ from personal life insurance?
The primary difference is the beneficiary and purpose. With key man insurance coverage, the business owns the policy and receives the payout to ensure business continuity. With personal life insurance, an individual owns the policy, and the payout goes to their family to cover personal expenses. In short, key person insurance protects your business, while personal life insurance protects your loved ones. To clarify this distinction, explore Is Keyman Insurance the Same as Life Insurance?.
When should a business consider key man insurance coverage?
The best time is before you need it. Consider this coverage if:
- Your business is a startup reliant on its founders.
- You are applying for loans, as lenders often require it.
- Your business is heavily reliant on specific individuals for sales, technical skills, or leadership.
- You are engaged in succession planning and need to fund a buy-sell agreement.
Crucially, you should secure coverage before a key person’s health changes, as it becomes more expensive or unavailable later.
What are the steps to get key man insurance coverage?
Getting key man insurance coverage is a straightforward process:
- Identify key individuals: Determine who is irreplaceable to your operations and profitability.
- Calculate their financial value: Use methods like the salary multiplier or profit contribution to determine an appropriate coverage amount.
- Obtain employee consent: The key employee must agree to be insured.
- Work with an insurance expert: An independent agency like ISU Armac can shop multiple carriers to find the best policy for your needs and budget.
- Complete the application and underwriting: This involves paperwork and often a medical exam for the key person.
Our team at ISU Armac guides clients through each step, making the process as smooth as possible.
Secure Your Business’s Future
Running a business means managing uncertainty, and one of the biggest risks is losing the people who make your company successful. Key man insurance coverage is a cornerstone of smart business planning, acting as a financial parachute when the unthinkable happens. It ensures the business you’ve built has the resources to survive and thrive after the loss of a crucial team member.
For businesses across Southern California—from Victorville and Apple Valley to Hesperia and Oak Hills—this protection shows employees, customers, and lenders that you are a responsible leader committed to stability. At ISU Armac, we’ve seen how the right key man insurance coverage can be the difference between weathering a storm and closing down.
As your local, independent agency in Victorville, we shop multiple carriers to find the best coverage for your specific needs and budget. The best time to protect your business is now, before it’s too late. To safeguard your company against the unexpected, explore your options. Learn more about a custom keyman insurance policy today. We’re here to help you protect what you’ve built.