
Why Manufacturers Insurance is Your First Line of Defense
Business insurance for manufacturers is essential protection against the unique risks that come with producing goods—from property damage and equipment failure to product liability claims and business interruption. Manufacturing operations face more complexity than ever, with specialized machinery, supply chain vulnerabilities, and technology integration creating new areas of risk at every stage of production.
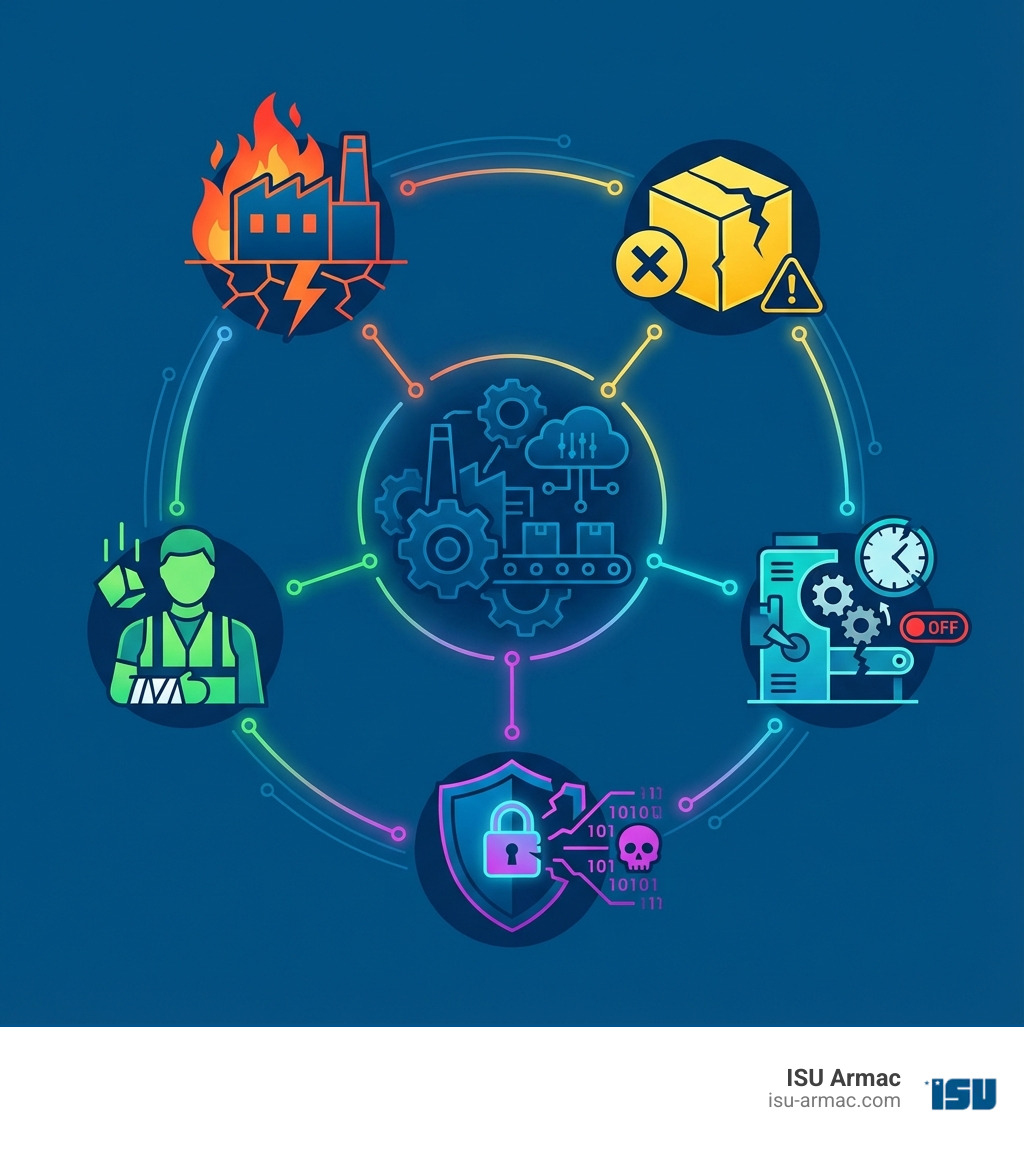
Key Protection Areas for Manufacturers:
- Property & Equipment – Covers buildings, machinery, raw materials, and finished inventory
- Product Liability – Protects against claims of injury or damage from products you manufacture
- Business Interruption – Replaces lost income when operations stop due to covered events
- Workers Compensation – Covers medical costs and lost wages for injured employees
- Equipment Breakdown – Pays for repairs and lost income from machinery failure
- Cyber Liability – Protects against data breaches and ransomware attacks
The stakes are high. Manufacturing represents more than 10% of the U.S. economy—$2.9 trillion in annual output. Over 37,900 fires at industrial properties occur each year, and the manufacturing industry accounted for 15% of all nonfatal workplace injuries in 2019. These aren’t just statistics—they’re real risks that can shut down your operation overnight without proper coverage.
Your manufacturing business faces risks at every stage, from receiving raw materials to shipping finished products. A single equipment failure can halt production for months. One defective product can trigger costly recalls. A workplace accident can result in significant medical claims. The right insurance strategy doesn’t just protect your assets—it ensures business continuity when the unexpected happens.
I’m Ryan McEachron, CEO of ISU Insurance Services ARMAC Agency in Victorville, and I’ve spent decades helping Southern California manufacturers find comprehensive business insurance for manufacturers that fits their specific operations and risk profile. Working with manufacturers ranging from small fabricators to large-scale food processors, I understand the protection gaps that can leave your business vulnerable.
Business insurance for manufacturers terms explained:
- insurance on manufactured homes
- manufactured home insurance companies
- manufactured home insurance policy
Core Coverages in Business Insurance for Manufacturers
When we talk about business insurance for manufacturers, we’re discussing a comprehensive suite of protections designed to safeguard your operations from the factory floor to the final customer. For many small to medium-sized manufacturers, a Business Owners Policy (BOP) is an excellent starting point. A BOP bundles essential coverages like general liability, commercial property, and business income insurance into one convenient and often cost-effective package. However, given the unique complexities of manufacturing, custom policies are crucial to ensure you’re adequately protected against the specific risks your business faces. Let’s dig into the core coverages that form the backbone of a robust manufacturing insurance plan.
Protecting Your Physical Assets and Operations
Your manufacturing facility, the machinery within it, and the materials you process are the heart of your business. Protecting these physical assets is paramount.

Commercial Property Insurance is designed to cover your buildings and structures, as well as their contents, from perils like fire, theft, vandalism, and certain natural disasters. This includes your invaluable machinery and equipment, raw materials waiting to be transformed, and the finished inventory ready for shipment. Imagine a fire breaking out in your facility—a scenario that, unfortunately, is not uncommon, with over 37,900 fires at industrial or manufacturing properties reported each year. Without adequate commercial property insurance, rebuilding and replacing everything could be financially devastating. We ensure your property is insured to its full replacement cost, considering factors like inflation and the time it takes to replace specialized equipment. For more detailed information on how we can help protect your assets, explore our Commercial Property Insurance services.
But what happens if a covered event forces your operations to shut down temporarily? This is where Business Interruption Insurance becomes a lifesaver. It helps replace lost income and covers ongoing operating expenses—like payroll, rent, and utilities—while your business is unable to operate. It can even cover the costs of temporary relocation, helping you get back on your feet as quickly as possible. For instance, if a power outage caused by an off-premises utility service interruption brings your production to a halt, this coverage can step in to mitigate the financial impact. Protecting your business’s ability to earn revenue, even when you can’t produce, is a critical component of any comprehensive business insurance for manufacturers strategy.
Shielding Against Liability Claims
In manufacturing, liability is a constant concern. From someone slipping and falling in your facility to a product you made causing harm, the potential for costly lawsuits is significant.

General Liability insurance is your first line of defense against claims of bodily injury or property damage that occur on your premises or as a result of your operations. If a visitor to your plant in Victorville trips over a loose wire and is injured, or if a piece of equipment you’re installing accidentally damages a client’s property, general liability can cover the associated legal fees, medical expenses, and settlements.
However, for manufacturers, the most critical liability coverage is often Product Liability Insurance. This coverage protects your business if a product you manufacture causes bodily injury or property damage to a third party. This can stem from:
- Design defects: Flaws in the product’s blueprint.
- Manufacturing flaws: Errors during the production process.
- Marketing defects: Inadequate warnings or instructions.
The role of product liability insurance for manufacturers cannot be overstated. It covers the legal defense costs, settlements, and judgments that can arise from such claims. Imagine a scenario where a component you manufactured for an appliance malfunctions and causes a fire in a customer’s home. Product liability insurance would be essential to steer the ensuing legal challenges. This protection is vital for any business that produces goods, from food processors in Hesperia to electronics manufacturers in Apple Valley. We understand the nuances of product liability and can help you secure robust coverage. Learn more about our specialized Product Liability Insurance services.
Covering Your Most Valuable Asset: Your People
No matter how automated your manufacturing process, your employees are indispensable. Their safety and well-being are not only ethical responsibilities but also legal and financial considerations.
Employee injuries and workplace accidents are an unfortunate reality in the manufacturing sector. The manufacturing industry accounted for 15% of all nonfatal injuries and illnesses in 2019, according to the U.S. Department of Labor Statistics. From operating heavy machinery to handling raw materials, there are inherent risks.
Workers’ Compensation Insurance is designed to provide benefits to employees who suffer work-related injuries or illnesses. This coverage typically pays for medical expenses, rehabilitation costs, and a portion of lost wages while the employee is recovering. In California, like most states, workers’ compensation insurance is generally mandatory for businesses with employees, regardless of size. This ensures that injured workers receive the care they need without having to sue their employer, and it protects your business from potentially devastating lawsuits. We can help you steer California’s specific requirements and ensure your coverage is compliant and comprehensive. For more information on protecting your team, visit our Workers Compensation Insurance services.
Beyond the Basics: Specialized Coverage for Modern Risks
While core coverages provide a strong foundation, the modern manufacturing landscape introduces a host of emerging risks. From increasing reliance on technology to complex global supply chains, your business needs specialized protection to thrive. We help manufacturers in Southern California and beyond identify these unique vulnerabilities and tailor insurance solutions accordingly.
Equipment Breakdown and Cyber Liability
Our factories today are powered by sophisticated machinery and interconnected digital systems. This technological backbone brings incredible efficiency but also new points of failure.
Equipment Breakdown Coverage is a crucial addition to any manufacturing policy. Standard commercial property insurance often excludes damages caused by mechanical or electrical breakdown. This specialized coverage steps in to protect your critical machinery and equipment from internal failures like power surges, mechanical failure, or even operator error. Considering that nearly half of unplanned downtime with electrical equipment and machinery is due to hardware failure and malfunction, this coverage can be a lifesaver. It not only covers the cost of repairing or replacing the damaged equipment but can also include business interruption coverage to compensate for lost income during the downtime. How can manufacturers insurance help with equipment breakdown? It ensures that a sudden, unexpected failure of a key piece of machinery doesn’t bring your entire operation to a grinding halt and drain your finances.
In our increasingly digital world, Cyber Liability Insurance has become non-negotiable. Manufacturers rely heavily on computer systems for design, production, inventory management, and customer data. A data breach, ransomware attack, or other cyber incident can disrupt your operations, compromise sensitive information, and lead to significant financial and reputational damage. Cyber liability insurance can cover costs associated with:
- Data breach notification and credit monitoring.
- Forensic investigations and data recovery.
- Legal defense and regulatory fines.
- Business interruption stemming from a cyber event.
How can manufacturers insurance help with cyber liability? It provides a crucial safety net in an age where digital threats are as real as physical ones. Protecting your data and systems is as important as protecting your physical assets. Explore our comprehensive Cyber Liability Insurance services to learn how we can safeguard your digital infrastructure.
Specialized business insurance for manufacturers: Small Businesses
Small manufacturing businesses often operate with tighter margins and fewer resources than their larger counterparts, making insurance even more critical. We pride ourselves on helping small manufacturers in places like Oak Hills and Apple Valley find custom, affordable protection. What are the benefits of specialized insurance for small manufacturing businesses?
- Cost-effective BOPs: As mentioned, a Business Owners Policy bundles key coverages, often at a lower premium than purchasing them separately. We can help customize a BOP that fits your specific needs without breaking the bank.
- Access to risk management: Many specialized insurers or independent agents like us offer valuable risk management resources and advice, helping small businesses implement safety protocols and reduce their exposure to claims.
- Scalable coverage: As your small business grows, your insurance needs will evolve. Specialized policies are designed to be flexible, allowing you to easily adjust coverage as you expand operations, acquire new equipment, or increase your workforce.
- Improved credibility: Having comprehensive business insurance for manufacturers signals professionalism and financial stability to clients, suppliers, and potential investors, enhancing your business’s credibility.
We understand the unique challenges faced by small manufacturers and are dedicated to finding solutions that protect your hard work. Find more about our offerings for small enterprises by visiting our Small Business Insurance services page.
Other Critical Endorsements
Beyond the foundational and specialized coverages, manufacturers often benefit from additional endorsements that address very specific risks.
- Product Recall Insurance: If a product you’ve manufactured is found to be defective or unsafe, leading to a recall, the costs can be astronomical. Product recall insurance can cover expenses such as notifying customers, logistics for retrieving the product, disposal, replacement costs, and even public relations efforts to protect your brand reputation.
- Commercial Auto Insurance: If your manufacturing business owns or leases vehicles for deliveries, transporting materials, or any business-related travel, commercial auto insurance is essential. It covers bodily injury and property damage liability, as well as physical damage to your company vehicles, ensuring your fleet is protected on the roads of Southern California and beyond. You can find more details on our Commercial Auto Insurance services.
- Inland Marine Insurance: This coverage protects your property that is frequently in transit or at a location other than your primary premises. For manufacturers, this could include raw materials being shipped to your facility, finished goods being transported to distributors, or specialized tools and equipment moved between job sites.
- Manufacturers E&O (Errors & Omissions) Insurance: While product liability covers physical injury or property damage from your product, Manufacturers E&O protects against financial losses incurred by a third party due due to a defect in your product, a failure to perform, or a mistake in your services. For example, if a component you manufactured causes a client’s final product to fail, leading to significant financial loss for them, E&O could provide coverage where general or product liability might not.
Understanding the Cost of Your Manufacturing Policy
One of the first questions we hear from manufacturers in Victorville, Hesperia, and across Southern California is, “How much will this cost?” There’s no one-size-fits-all answer because each manufacturing business is unique. We approach every client with a fresh perspective, conducting a thorough risk assessment to develop custom-rated policies that truly reflect your operations.
Key Cost Factors for Business Insurance for Manufacturers
What factors influence the cost of manufacturers insurance? Several elements come into play when determining your premium:
- Type of Products Manufactured: The inherent risk associated with what you produce plays a major role. For instance, a manufacturer of medical devices or food products may face higher product liability risks than a textile manufacturer, influencing rates.
- Annual Revenue: Generally, businesses with higher revenues may have more assets to protect and potentially greater exposure to claims, which can impact premiums.
- Number of Employees & Payroll: This is a significant factor for workers’ compensation costs. More employees, especially in hazardous roles, will lead to higher premiums.
- Claims History: A history of frequent or costly claims will almost certainly result in higher insurance premiums, as it indicates a higher future risk to insurers.
- Safety Protocols and Risk Management: Businesses with robust safety programs, regular employee training, and a strong safety culture often qualify for lower premiums. Insurers view proactive risk mitigation favorably.
- Equipment Type and Age: The value, complexity, and age of your machinery and equipment can affect property and equipment breakdown insurance costs. Older or highly specialized equipment might be more expensive to insure.
- Location: Geographic location influences property insurance costs (e.g., proximity to fire services, natural disaster risks like earthquakes or wildfires in Southern California) and can also affect liability and workers’ compensation rates due to varying state regulations and legal environments.
- Coverage Limits and Deductibles: Higher coverage limits provide more protection but come with higher premiums. Conversely, choosing a higher deductible (the amount you pay out-of-pocket before insurance kicks in) can lower your premium, but means you bear more initial risk.
Understanding these factors is the first step toward managing your insurance budget effectively. We work closely with our clients to balance comprehensive protection with cost-efficiency. For more insights into how these factors impact your overall expenses, please explore our Business Insurance Cost services.
Choosing the Right Partner: Selecting Your Insurance Provider
When it comes to business insurance for manufacturers, expertise matters. The unique risks of manufacturing mean that not all insurance providers are created equal, and not all policies offer the same level of protection. You need a partner who understands your industry, your specific challenges, and your goals. We believe in building long-term relationships, becoming an extension of your risk management team.
What to Look for in an Insurer
What are the key considerations when choosing an insurance provider for a manufacturing business? Here’s what we advise our clients to prioritize:
- Industry Specialization: Look for an insurer or agency with a deep understanding of the manufacturing sector. They should be familiar with your specific processes, equipment, and regulatory environment.
- Financial Stability: Choose an insurer with a strong financial rating. This ensures they have the capacity to pay out large claims if and when they occur.
- Claims Handling Process: A smooth, efficient, and fair claims process is crucial. You want an insurer that will respond quickly and transparently when you need them most.
- Risk Control Services: Many top insurers offer valuable risk control and safety services. How can manufacturers leverage resources and safety services offered by insurers to mitigate risks? These services can include on-site hazard assessments, development of workplace safety programs, loss trend analysis, and training resources for employees. Leveraging these can not only reduce your risk of claims but potentially lower your premiums.
- Safety Program Resources: Look for partners who provide resources to help you cultivate a culture of safety. This could be anything from online training modules to best practice guides for product liability.
- Global Coverage Capabilities: If your manufacturing business has international operations or supply chains, ensure your insurer can provide consistent global coverage and services, addressing any differences in conditions or limits between domestic and foreign policies.
- Policy Customization: Your business is unique, and your insurance should be too. Look for a provider who can tailor policies precisely to your needs, rather than offering a one-size-fits-all solution.
The Value of an Independent Agent
In the complex world of business insurance for manufacturers, an independent agent like us is your greatest asset. We bring several distinct advantages to the table:
- Access to Multiple Carriers: Unlike captive agents who represent a single insurer, we work with a wide network of insurance companies. This means we can shop around to find the best coverage options and rates that fit your specific manufacturing business, whether you’re in Apple Valley or anywhere else in Southern California.
- Unbiased Advice: Our primary allegiance is to you, our client. We provide objective recommendations based on your needs, not on promoting a single company’s products.
- Local Knowledge: As a Victorville-based agency, we understand the local business environment, regional risks, and specific regulations that might impact manufacturers in Southern California. This local insight is invaluable in crafting relevant coverage.
- Personalized Service: We take the time to understand your unique operations, challenges, and goals. This allows us to offer truly personalized service and build a relationship based on trust and understanding.
- Advocacy During Claims: Should you ever need to file a claim, we act as your advocate, guiding you through the process and ensuring your interests are represented.
Working with ISU Armac means you have a dedicated partner committed to securing the best possible protection for your manufacturing business. You can find an agent through us to tailor coverage that addresses the specific risks your business faces.
Frequently Asked Questions about Manufacturing Insurance
We often get asked similar questions by manufacturers looking to protect their businesses. Here are some of the most common ones:
Who needs manufacturers insurance?
Any business that produces products or goods needs business insurance for manufacturers. The risks inherent in designing, producing, and distributing physical items are universal across the sector. This includes a vast array of industries, such as:
- Food and beverage manufacturers: Bakeries, bottling plants, canning facilities, craft breweries, fruit drink producers.
- Metal goods manufacturers: Fabricators, iron and steel manufacturing, metalworking shops.
- Plastic goods manufacturers: Producers of various plastic components and finished products.
- Electronics manufacturers: Computer and electronics assembly, electronic component manufacturing.
- Textiles manufacturers: Clothing and apparel producers, textile mills.
- Furniture manufacturers: From custom pieces to mass-produced items.
- Other specialized manufacturers: Tool and die manufacturers, printers, publishers, mobile home manufacturers, and many more.
If you’re turning raw materials into finished products, you have unique risks that generic business insurance simply won’t cover adequately.
What is the most important insurance for a manufacturer?
While all coverages discussed are vital for a comprehensive protection strategy, Product Liability Insurance is uniquely critical for manufacturers. This is because your primary function is to create and sell products, and with that comes the inherent risk that your product could cause harm. A single product liability lawsuit can be financially ruinous, covering legal defense costs, settlements, and potential damage to your brand reputation. While property insurance protects your assets and workers’ compensation protects your employees, product liability directly addresses the unique exposure that defines a manufacturing business—the product itself. We emphasize this coverage because it directly impacts your core business output.
How can I lower my insurance costs?
Managing insurance costs is a priority for every business. Here are several effective strategies we recommend to our manufacturing clients:
- Implement a formal safety program: A proactive approach to workplace safety, including regular training, proper equipment maintenance, and clear safety protocols, can significantly reduce accidents and claims, leading to lower workers’ compensation and liability premiums.
- Maintain a clean claims history: Fewer claims over time demonstrate lower risk to insurers, which can translate into more favorable rates.
- Increase your deductible: By agreeing to pay a larger portion out-of-pocket for each claim, you can lower your annual premium. Just ensure your deductible is an amount your business can comfortably afford.
- Bundle policies: Often, combining multiple insurance policies (like general liability, property, and business income in a BOP) with a single insurer can result in discounts compared to purchasing them separately.
- Regularly review your coverage needs: Your business evolves, and so should your insurance. Annual reviews with your agent ensure you’re not over-insured or under-insured, and that your policy reflects your current operations and risks.
We help manufacturers in Southern California identify these opportunities and work towards a more cost-effective yet robust insurance program.
Conclusion: Secure Your Legacy with the Right Protection
From the moment raw materials enter your facility to the final product leaving your docks, your manufacturing business faces a dynamic array of risks. Business insurance for manufacturers isn’t just a regulatory requirement; it’s a strategic investment in your future. By understanding and securing the right protections—from commercial property and product liability to specialized coverages like equipment breakdown and cyber liability—you build resilience against the unexpected.
Proactive risk management, coupled with comprehensive insurance, ensures your hard-earned investments are safeguarded, your employees are protected, and your business continuity is maintained. Don’t let a single unforeseen event derail years of dedication and hard work. Working with an expert partner like ISU Armac ensures you can steer the complexities of business insurance for manufacturers and find the best coverage from multiple carriers to protect your investment from raw materials to final product. We’re here in Victorville, ready to help manufacturers across Southern California secure their legacy.