
Manufactured home insurance policy is a specialized insurance designed to protect your manufactured or mobile home and its contents from various types of losses. This coverage typically includes protection against theft, fire, severe weather, and liability for accidents that occur on your property.
Here’s a quick breakdown of what a manufactured home insurance policy usually covers:
- Your home and attached structures
- Personal belongings such as electronics and appliances
- Liability protection if someone is injured on your property
- Temporary living expenses if your home becomes unlivable
Insurance is not legally required for manufactured homes. However, most lenders and communities do require it for financing or residency.
Understanding the importance of a manufactured home insurance policy is crucial for protecting your investment and peace of mind. Accidents and unpredictable weather can happen, making it essential to have the right coverage.
I’m Ryan McEachron, and I’ve spent years helping residents and business owners in the High Desert region find affordable insurance solutions custom to their needs. My experience with manufactured home insurance policy ensures you get coverage that fits your lifestyle—whether you’re a homeowner or a business owner seeking protection. Let’s explore more about this essential insurance policy.
Simple manufactured home insurance policy word guide:
– manufactured home insurance
– manufacturing insurance
Understanding Manufactured Home Insurance Policies
When it comes to protecting your manufactured home, understanding the different coverage types is key. Let’s explore the two main components: Dwelling Coverage and Personal Property Coverage.
Dwelling Coverage
Dwelling Coverage focuses on the physical structure of your home. This includes the walls, roof, and any attached structures like a garage or porch. If a fire, storm, or other covered event damages your home, dwelling coverage helps pay for repairs or even replacement.
Imagine a severe hailstorm hits, damaging your roof. With dwelling coverage, the cost to repair or replace your roof is covered, minus your deductible. This ensures your home remains safe and livable.
Personal Property Coverage
Personal Property Coverage protects the belongings inside your home. This includes electronics, furniture, and clothing. If your personal items are stolen or damaged by a covered event, this coverage helps replace them.
For instance, if a fire damages your living room, personal property coverage can help replace your TV, couch, and other items. It’s like having a safety net for your possessions.
Both dwelling and personal property coverage are essential parts of a manufactured home insurance policy. They ensure that both your home and the things you love are protected from unexpected events.
Understanding these coverage types helps you make informed decisions about your insurance needs. Next, we’ll explore additional coverage options that can further improve your policy.
Additional Coverage Options
When it comes to protecting your manufactured home, having the right coverage is crucial. Beyond the basic dwelling and personal property coverage, there are additional options to consider. Let’s explore Scheduled Personal Property and Liability Coverage.
Scheduled Personal Property
Your standard manufactured home insurance policy covers many of your belongings, but there are limits. If you own high-value items like jewelry, collectibles, or fine art, you might need more protection. This is where scheduled personal property coverage comes in.
Scheduled personal property coverage allows you to insure specific items for their full value. For example, if you have a diamond ring that’s worth more than your policy’s limit for jewelry, you can add an insurance rider to cover its full value. This ensures that if the ring is lost, stolen, or damaged, you won’t be left out of pocket.
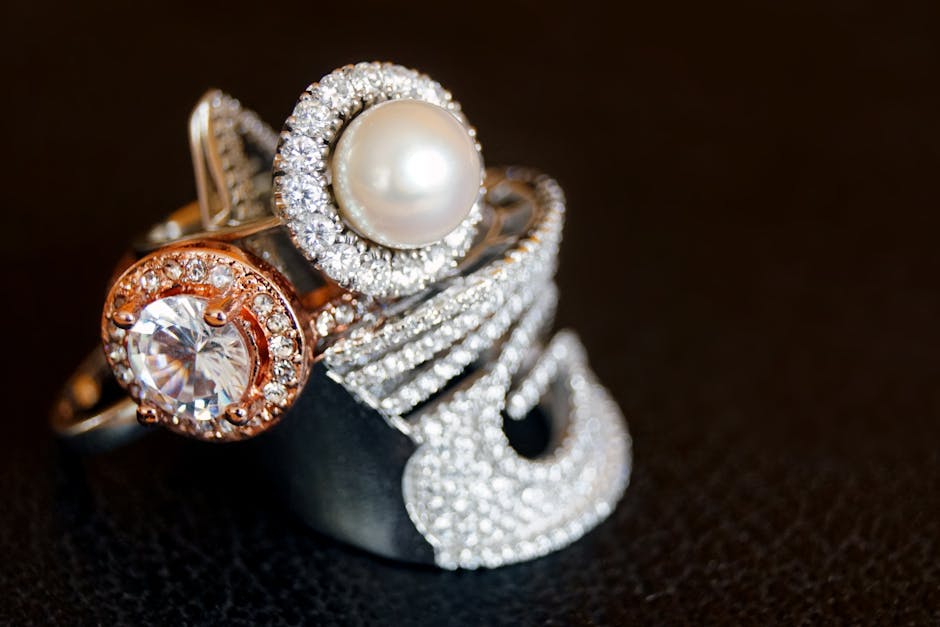
To schedule an item, you’ll need to provide a receipt or appraisal. This helps the insurance company determine its value. The benefit? There’s often no deductible for scheduled items, and they’re covered for a wider range of risks.
Liability Coverage
Liability coverage is another essential part of a comprehensive manufactured home insurance policy. It protects you financially if someone is injured on your property or if you accidentally damage someone else’s property.
Imagine your child is playing with friends in the yard and accidentally breaks a neighbor’s window. Liability coverage can help pay for the repair. Similarly, if a visitor trips on your porch steps and needs medical attention, this coverage can cover their medical bills and any legal fees if they decide to sue.
Having robust liability coverage gives you peace of mind. It ensures you’re protected against unexpected incidents that could otherwise lead to significant financial strain.
Both scheduled personal property and liability coverage are valuable additions to your manufactured home insurance policy. They offer extra layers of protection, ensuring that both your cherished belongings and your financial well-being are safeguarded.
Next, we’ll dive into the factors that can affect the cost of your manufactured home insurance and explore potential discounts and savings.
Factors Affecting Manufactured Home Insurance Costs
When it comes to the cost of a manufactured home insurance policy, several factors play a significant role. Understanding these can help you manage expenses and ensure you’re getting the right protection at a fair price.
Age of Home
The age of your manufactured home is a key factor. Newer homes often have updated safety features and materials, which can reduce insurance costs. Many insurers offer an age of home discount for newer properties, as they are generally less risky to insure.
Location
Where your home is located matters a lot. Homes in areas prone to natural disasters like floods or earthquakes typically have higher premiums. For example, a manufactured home in coastal regions of Southern California might face higher rates due to the risk of earthquakes or severe weather.
Claims History
Your claims history can significantly impact your premium. If you’ve had few or no claims in recent years, you might qualify for a loss-free discount. This discount rewards homeowners who have maintained a clean claims record, indicating lower risk to insurers.
Discounts and Savings
Insurance companies often provide several ways to save on your manufactured home insurance. Here are some common discounts:
Age of Home Discount: As mentioned, newer homes often qualify for discounts due to their modern safety features.
Loss-Free Discount: If you haven’t filed any claims for a certain period, you might receive a discount on your premium.
New Purchase Discount: Just bought your manufactured home? Some insurers offer discounts for new purchases as an incentive for new homeowners.
To maximize your savings, ask your insurance provider about available discounts and see which ones you qualify for. By understanding these factors and potential savings, you can make informed decisions about your manufactured home insurance costs.
In the next section, we’ll tackle some frequently asked questions about manufactured home insurance policies.
Frequently Asked Questions about Manufactured Home Insurance Policies
Is manufactured home insurance required?
While there is no legal requirement to have a manufactured home insurance policy, many mortgage lenders do require it. This is because they want to protect their investment in your property. If you’re financing your home, it’s likely that your lender will insist on insurance coverage to ensure that their financial interests are safeguarded in case of damage or loss.
What is not covered by standard policies?
Standard manufactured home insurance policies cover a lot, but not everything. For example:
Floods and Earthquakes: These natural disasters are typically not covered under standard policies. If you live in an area prone to floods or earthquakes, you might need separate policies for these risks. Learn more about what isn’t covered by standard policies.
Maintenance Issues: Regular wear and tear, such as a leaky roof or old plumbing, are not covered. Insurance is designed to protect against unexpected events, not routine maintenance.
How much coverage do I need?
Determining how much coverage you need can be tricky, but it boils down to a few key factors:
Personal Property: Consider the value of your belongings, like electronics, furniture, and clothing. Make sure your policy covers the replacement cost of these items.
Assets: Think about your total assets and how much you stand to lose in a worst-case scenario. You want enough liability coverage to protect your financial well-being.
Custom Policy: Everyone’s needs are different, so customizing your policy is crucial. Work with an insurance agent to tailor your coverage to fit your specific situation and ensure you’re not underinsured.
By understanding these aspects, you can make informed decisions about your manufactured home insurance policy. Next, we’ll explore additional coverage options that can further protect your home and belongings.
Conclusion
Choosing the right manufactured home insurance policy is crucial for protecting your home and personal belongings. At ISU Armac, we understand that every homeowner’s needs are unique, and we’re here to help you find the best coverage that suits your situation.
As an experienced insurance agency based in Victorville, California, we pride ourselves on offering personalized service to our clients. Our ability to shop multiple carriers ensures that you get the most comprehensive coverage at competitive rates. Whether you’re in Apple Valley, Hesperia, Oak Hills, or anywhere in Southern California, our team is ready to assist you.
Why Choose ISU Armac?
Expert Guidance: Our knowledgeable agents help you steer the complexities of insurance, ensuring you understand your policy and options.
Customized Coverage: We tailor your policy to meet your specific needs, whether it’s additional coverage for valuables or increased liability protection.
Competitive Pricing: By leveraging our relationships with various carriers, we find the best rates without compromising on coverage quality.
Local Expertise: With a deep understanding of the Southern California market, we offer insights and advice that are relevant to your area.
Protecting your home is more than just a financial decision—it’s about peace of mind. Let us help you secure the coverage you need so you can focus on what truly matters. To learn more about how we can assist you with your manufactured home insurance needs, visit our Manufacturer Insurance page.
With ISU Armac by your side, you can rest easy knowing you’re covered.