
Why Getting a Business Insurance Quote Matters
Getting a business insurance quote is the first step to protecting your hard work. It means finding out how much it costs to shield your company from unexpected problems. Without the right coverage, lawsuits, accidents, or property damage can threaten your business.
Here’s how to get a business insurance quote:
- Gather Information: Collect details about your business. This includes your business type, annual income, number of employees, and location.
- Choose a Method: You can get quotes online, call insurance companies directly, or work with an independent insurance agent.
- Compare Offers: Look closely at the coverage limits, what you’ll pay out-of-pocket (deductibles), and the monthly or yearly costs (premiums) from different providers.
- Confirm & Buy: Pick the policy that best fits your business’s unique needs and budget.
This guide will walk you through everything you need to know. You’ll learn about different policy types and how to get the right coverage at a fair price.
I’m Ryan McEachron. My experience as CEO of ISU Insurance Services ARMAC Agency has given me a deep understanding of securing the right business insurance quote. I’ve helped countless businesses in the Victorville area protect their future.
Glossary for business insurance quote:
- business liability insurance cost
- commercial general liability insurance coverage
- is general liability insurance required by law
Understanding Your Business Insurance Needs Before You Quote

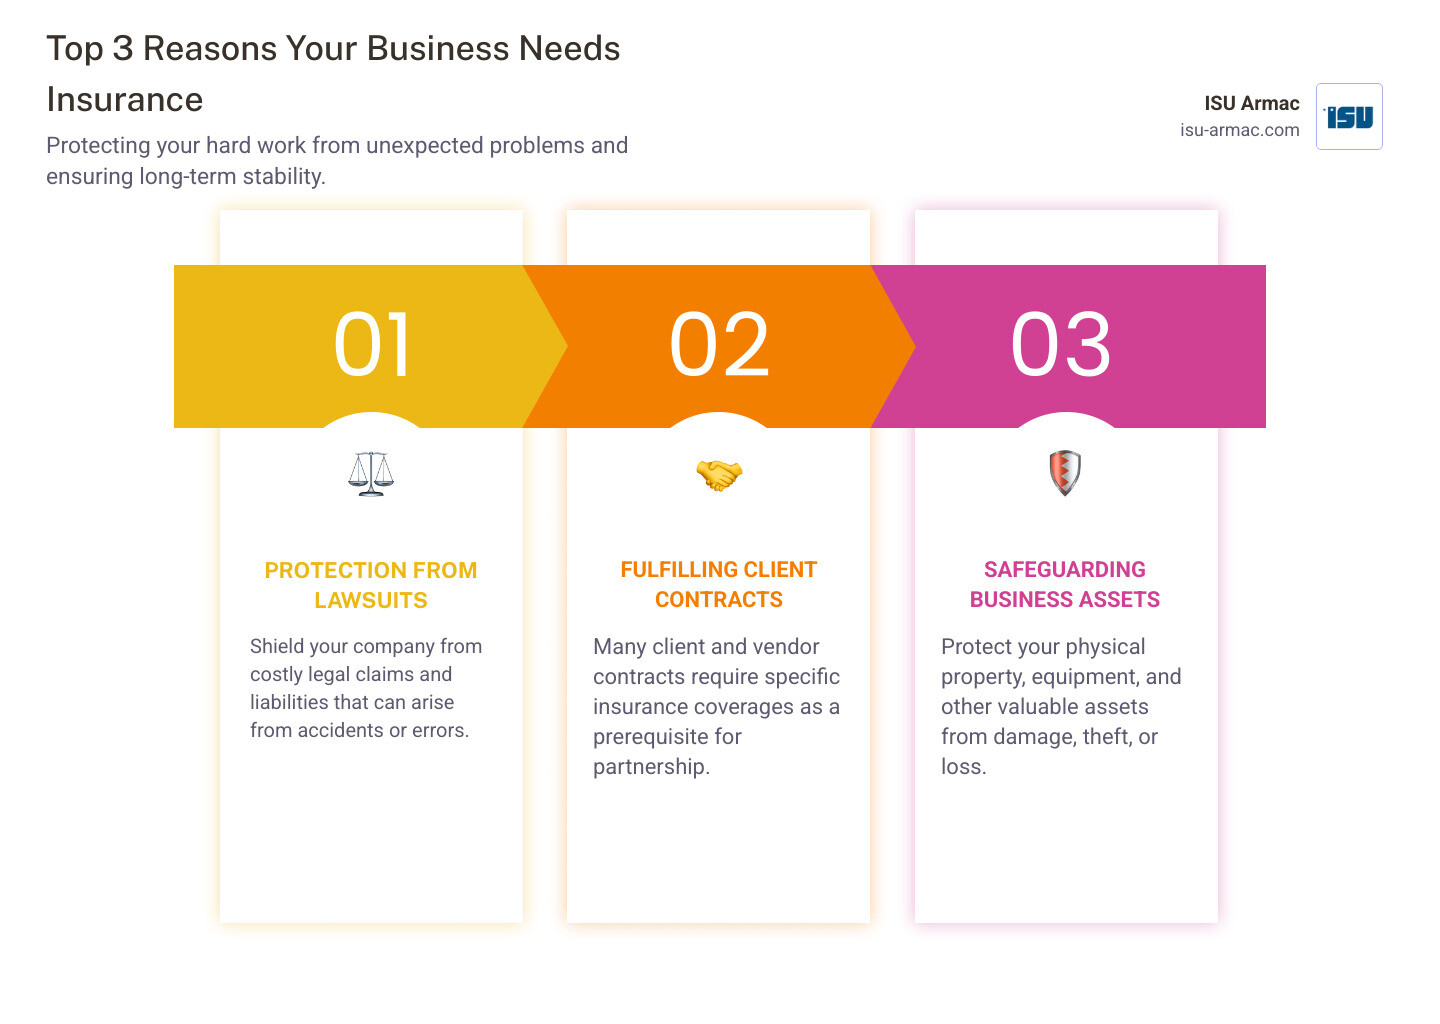
Before you collect a single business insurance quote, remember why coverage exists in the first place: to keep your company alive when the unexpected happens.
Why coverage matters
- Legal compliance – Most states mandate workers’ compensation and certain liability policies.
- Contract requirements – Landlords and big clients almost always ask for a Certificate of Insurance (COI).
- Asset protection – Buildings, tools and stock can be wiped out by fire, theft or disasters.
- Lawsuit defense – Liability policies pay legal costs so one claim doesn’t bankrupt you.
- Business continuity – Interruption coverage replaces lost income after a covered shutdown.
Essential policy types at a glance
- General Liability – Trip-and-fall, property damage, libel/slander.
- Professional Liability / E&O – Service mistakes or bad advice.
- Workers’ Compensation – Employee injuries or occupational illness.
- Commercial Property – Buildings, equipment and inventory.
- Commercial Auto – Vehicles titled to, or used by, the business.
- Business Owner’s Policy (BOP) – Bundles property and liability for a lower combined rate.
- Cyber Liability – Data breaches, ransomware, notification costs.
- Key Person Insurance – Replaces income if a vital owner or employee dies or is disabled.
Do you really need insurance if you’re an LLC, sole proprietor or online only?
Yes. An LLC shields personal assets from business debts, but not the company’s own cash or property. Sole proprietors have no separation at all, so one lawsuit can hit your house or savings. Online stores still face product-liability and cyber risks, and homeowners policies almost never cover business gear or client injuries at your residence.
For the eye-opening downside of skipping coverage, review the 9 Big Risks of Going Without Commercial Liability Insurance article on our site.
Decoding the Cost: What to Expect from Your Business Insurance Quote

No two companies pay the same premium. Insurers look at industry risk, location, payroll, revenue and claims history, then tailor a business insurance quote to match. According to the U.S. Small Business Administration, firms in higher-hazard trades (think construction) regularly spend several times more than low-risk consultants.
Key cost drivers in plain English:
- Industry – Heavy equipment or hazardous materials raise rates.
- ZIP code – Storm frequency, crime stats and lawsuit trends count.
- Head-count & payroll – More employees increase workers’-comp and liability exposure.
- Revenue – Bigger operations interact with more customers and contracts.
- Claims record – A clean loss run can earn sizeable discounts.
- Limits & deductibles – Higher limits cost more; larger deductibles lower premiums.
Typical monthly premiums
| Policy | National Median Monthly | National Median Annual |
|---|---|---|
| General Liability | $42-$68 | $504-$810 |
| Professional Liability | $42-$62 | $504-$744 |
| Workers’ Compensation | $45-$80 | $540-$1,032 |
| Business Owner’s Policy | $141 | $1,687 |
Figures above reflect new policies for small businesses in 2024; your own numbers may be lower or higher. Need a deeper dive? Our guide How Much Does Insurance Cost for a Small Business? breaks down the math and shows simple ways to save.
The Step-by-Step Guide to Getting a Business Insurance Quote

Getting covered no longer takes weeks-most of our clients in Victorville, Apple Valley and across Southern California secure protection in under 48 hours.
- Initial contact – Call us or start the secure form on our site.
- Information gathering – We’ll ask about legal name, EIN, operations, revenue, payroll, vehicles and prior claims.
- Market shopping – ISU Armac submits that single data set to multiple carriers, sparing you repeat paperwork.
- Underwriting review – Carriers analyze your risk profile; simple accounts can be approved instantly, complex ones usually within a day.
- Bind & pay – Choose the option you like and make the initial payment.
- Instant proof of insurance – Your Certificate of Insurance (COI) is emailed immediately so you can sign leases or contracts.
Need an easy starting point? Grab an online small-business quote or speak with an advisor for a customized commercial insurance quote.
Quick checklist: documents to have ready
- Legal business name & address
- Business structure (LLC, corporation, etc.)
- Detailed description of operations
- Estimated annual revenue & payroll
- Employee count
- Vehicle list (if any)
- Major equipment & inventory values
- Prior insurance policies and loss history
Bringing this data to the first conversation speeds everything up-and often lowers your premium because underwriters reward clear, complete information.
Customizing Your Policy and Finding the Right Provider

When it comes to protecting your business, there’s no such thing as a “one-size-fits-all” policy. Your business is unique, with its own special risks and needs. That’s why customizing your insurance is so important. It ensures your coverage truly fits what you do.
Custom Coverage and Bundling Discounts
A generic, “cookie-cutter” policy can leave you with big gaps. These gaps can expose you to risks you thought you were covered for. We take the time to understand your exact business operations and what risks you might face. This helps us build a policy that really works for you. For example, a landscaping company that only mows lawns has different needs than one that also trims tall trees. Your insurance should match these differences perfectly.
Many insurance companies also offer great discounts when you bundle different coverages together. A popular choice for small businesses is the Business Owner’s Policy (BOP). This package often combines general liability and commercial property insurance. It’s usually more affordable than buying each policy separately. For instance, some companies, like The Hartford, offer up to a 10% discount on a BOP when you add workers’ compensation insurance. This bundling is a smart way to get thorough protection and save money on your business insurance quote.
Beyond the main policies, you can also add policy endorsements. Think of these as little add-ons that fine-tune your coverage. They help protect against very specific risks. For example, you might add equipment breakdown coverage to your commercial property policy. This helps if your machinery suddenly stops working due to mechanical failure.
Choosing a Provider
Picking the right insurance provider is just as crucial as selecting the right coverage. You want a partner who will be there when you need them most. Here’s what we look for when helping you choose:
First, we check for carrier financial strength. This means making sure the insurance company has strong financial ratings. It shows they have the money to pay out claims, even big ones. You can rest easy knowing they’ll stand by you in a crisis.
Second, claims service ratings are key. What good is a policy if getting a claim paid is a nightmare? We prefer carriers known for excellent claims service. This ensures that if you ever need to file a claim, the process will be easy, fair, and supportive. For example, The Hartford has a strong 4.8-star claims rating from thousands of customers.
You have a couple of main choices when looking for a business insurance quote:
Direct Insurers: Some companies let you get quotes and buy policies straight from their website. This can seem fast and simple. But, you’re only seeing their products. You might miss out on better options from other providers.
Independent Agents (like ISU Armac!): This is where our unique value really shines! We are not tied to just one insurance company. Instead, we work with a wide network of top-rated carriers. This lets us shop around for you, comparing many different offers. We can then show you a range of options that fit your specific needs and budget. We act as your advocate, helping you understand the complex world of commercial insurance. Our goal is to ensure you get the best coverage at the lowest rates. This means you don’t have to spend hours researching different companies yourself. We do that legwork for you, giving you personalized advice custom to your business.
Our Business Insurance Services are designed to make this whole process simple for you. We give you the confidence that your business is truly well-protected.
Frequently Asked Questions about Business Insurance
We often encounter similar questions from business owners looking for protection. It’s smart to ask! Here are some of the most common questions we hear, and our simple answers:
Does my homeowners insurance cover my home-based business?
This is a really common question, and it’s super important to understand the answer. The short answer is: No, your homeowners insurance generally does not cover your home-based business.
Think of it this way: your homeowners policy is designed for your personal living space and belongings. It typically has very little, if any, coverage for things like business-related liability, specialized equipment, or your business inventory. For example, if you’re a photographer working from home and your expensive camera gear is stolen, your homeowners policy might not cover its full value because it’s considered business property. Or, if a client comes to your home for a meeting and accidentally gets hurt, your homeowners liability might not protect you from a lawsuit related to that business visit.
To truly protect your hard work and personal assets, you’ll need a separate business insurance policy. A Business Owner’s Policy (BOP) is often a great choice for home-based businesses because it bundles key coverages you’ll need.
What is a Certificate of Insurance (COI) and when do I need one?
A Certificate of Insurance (COI) might sound fancy, but it’s really just a simple document. It’s official proof that you have insurance coverage. Think of it like your business’s insurance ID card.
This document clearly shows important details about your policy, such as what types of coverage you have, how much coverage you’re carrying (your limits), and when your policy is active.
You’ll often need a COI in a few key situations:
- When you’re signing a commercial lease for an office or retail space.
- When you’re trying to win a new client contract, especially if you’re a contractor, consultant, or provide professional services. Many clients want to see proof you’re insured before they work with you.
- When you need to obtain a professional license or permit for your business.
The good news is that getting a COI is usually very easy. Many insurers allow you to get or even generate a customized COI online, often in just a few minutes. We can help you get yours quickly when you secure your business insurance quote and policy through us.
Can I save money by bundling business insurance policies?
Yes, absolutely! Bundling your business insurance policies is often one of the best ways to save money while still getting comprehensive coverage.
Insurance companies frequently offer discounts when you buy multiple types of coverage from them. It’s a win-win: they get more of your business, and you get a lower premium.
A very common and popular bundle for small to medium-sized businesses is a Business Owner’s Policy (BOP). This policy conveniently combines two essential coverages: general liability insurance and commercial property insurance. By getting these two policies together in a BOP, you’ll almost always pay less than if you bought each one separately.
Bundling is a smart strategy to make sure your business is well-protected without breaking the bank. It helps you get all the coverage you need while keeping your insurance budget optimized.
Conclusion
You’ve poured your heart and soul into building your business, and that’s something truly special. Protecting that hard work isn’t just about ticking a box; it’s one of the smartest investments you can make for its future.
Throughout this guide, we’ve walked you through understanding your unique needs, gathering all the right information, and carefully comparing your options. Why? Because the goal is always to secure a policy that truly safeguards your bottom line and gives you incredible peace of mind.
And that’s exactly where an independent insurance agency like ISU Armac comes in. We believe getting the right business insurance quote shouldn’t be a headache. Our superpower is shopping multiple top-rated carriers for you, all at once. This means you get a truly custom policy custom to your specific business, and often at a much more competitive price than if you went searching on your own.
We’re proud to help businesses just like yours in Apple Valley, Victorville, Hesperia, Oak Hills, and throughout Southern California steer the often-complex world of insurance. No more guessing games, just clear, effective protection.
So, are you ready to take that vital next step to secure your business’s future? Let’s get you covered.