
You open the doors to your Victorville podiatry practice, staff is in place, treatment rooms are ready, and patients are already on the schedule. Then the question hits. If a patient alleges negligent care, if someone slips in the lobby, if an employee gets hurt, or if your systems go down, what absorbs the financial damage?
That answer shouldn't be guesswork. If you're shopping for podiatrist insurance in Victorville, CA, you need coverage built for a California medical practice, not a generic small business package. A podiatry office has clinical liability, premises liability, staffing obligations, equipment exposure, and growing data risk. Miss one piece and the gap can get expensive fast.
You also need a policy structure that matches how you operate. A solo office has different pressure points than a growing clinic with front desk staff, assistants, digital records, and community outreach events. The right insurance plan protects your balance sheet, your license, and your ability to keep seeing patients without disruption.
Table of Contents
- Protecting Your Podiatry Practice in Victorville
- The Foundation Professional and General Liability
- Streamline Your Coverage with a Business Owner's Policy
- Protecting Your Team and Your Data
- Understanding Costs and Proactive Risk Management
- Why a Local Independent Agent in Victorville Matters
Protecting Your Podiatry Practice in Victorville
A patient slips near your front desk on a busy afternoon. An hour later, a post-op patient calls with a complication and says your office missed the warning signs. By closing time, you are dealing with two very different claim scenarios. That is how risk shows up in a Victorville podiatry practice. It is rarely one problem at a time.
Header image details: Alt text is provided above. Suggested IPTC metadata: Headline "Podiatrist insurance Victorville CA"; Description "Reception area of a modern podiatry clinic in Victorville, California"; Keywords "podiatrist insurance, Victorville CA, medical office insurance, podiatry clinic, California business insurance"; Creator "ISU Insurance Services"; City "Victorville"; State "California"; Country "United States."
If you practice in Victorville, your insurance plan should reflect how your office operates. Patient traffic, treatment rooms, charting systems, employees, equipment, and landlord requirements all create separate exposures. California adds another layer. Employment rules are stricter, claims can get expensive fast, and a coverage gap that looks small on paper can become a serious financial problem once a claim is filed.
Start with the exposures, not the policy names. That is how good coverage gets built.
Ask yourself four direct questions:
- If a patient alleges harm tied to diagnosis, treatment, or follow-up, do you have coverage built for that clinical risk?
- If someone falls in your waiting room or claims your office caused property damage, does your policy respond to that non-clinical event?
- If a fire, water loss, or other covered incident forces you to stop seeing patients, how does the practice keep paying rent, payroll, and overhead?
- If you have employees and digital records, have you set up coverage that matches California requirements and real-world office operations?
The right order matters. Buy insurance the same way claims tend to hit a practice. Cover patient-care risk first. Cover office and visitor risk next. Then protect the building contents, income, staff, and data that keep the practice running.
For many podiatrists, that means reviewing a medical office insurance program for healthcare businesses as part of the setup, then tailoring it to your practice size, procedures, payroll, and record systems. A solo office in Victorville needs a different structure than a growing practice with multiple employees, higher patient volume, and heavier reliance on digital scheduling and charting.
This is also where local advice matters. Victorville practices deal with the same core medical risks as any podiatry office, but your lease terms, property conditions, staffing setup, and patient flow are local. A local independent agent can spot gaps that a generic online quote will miss and help you set up coverage that fits the practice you run, not a template built for every healthcare office in California.
The Foundation Professional and General Liability
A patient leaves your treatment room in stable condition, then slips near the front desk on a wet patch from a tracked-in drink. By the end of the week, you could be dealing with two separate problems. One claim questions your clinical care. The other targets the condition of your office. Those are different exposures, and they belong on different policies.
Professional liability protects your clinical work
Professional liability covers allegations tied to diagnosis, treatment, follow-up, documentation, and other decisions connected to patient care. If a patient claims your medical services caused harm, this is the policy that responds.
For a Victorville podiatrist, this is the first coverage to review and the last place to cut limits. Hospital privileges, payer contracts, referral relationships, and your own risk tolerance all affect what limits make sense. California practice conditions also matter. If you perform higher-acuity procedures, treat diabetic patients with complicated wound issues, or rely heavily on charting and follow-up protocols, weak malpractice coverage is a bad bet.
Do not guess. Pull your declarations page and verify three things: your limits, whether the policy is claims-made or occurrence, and whether tail coverage would be needed if you retire, change carriers, or sell the practice.
General liability protects the business environment
General liability covers injuries and property damage tied to your premises and daily business operations. A patient trip in the lobby, a delivery person injured in a hallway, or accidental damage to someone else's property usually falls here, not under malpractice.
That distinction matters in a podiatry office because patients often have mobility issues. They use walkers, canes, post-op boots, and wheelchairs. A small hazard in reception or the hallway can turn into a claim fast. If you want a plain-language explanation of what this policy does, read this guide on general liability insurance for a business.
A lot of practice owners assume their malpractice policy will somehow catch these incidents. It will not.
Your treatment decisions and your office conditions create different claim paths. Insure both correctly.
Don't confuse the two
Keep the separation clear:
- Professional liability: A patient alleges your care caused injury or worsened a condition.
- General liability: A visitor, vendor, or patient alleges the office environment caused injury or property damage.
- Property insurance: Covered damage affects your equipment, furnishings, or office contents.
- Business income coverage: A covered loss interrupts operations and cuts revenue.
That is the baseline for a properly protected podiatry practice in Victorville. If one of these pieces is missing, you do not have a minor gap. You have a claim scenario waiting for a bad answer.
Streamline Your Coverage with a Business Owner's Policy
A pipe bursts overnight in your Victorville office. By morning, water has reached the front desk, damaged computers, and forced you to cancel a full day of patients. You are not dealing with one problem. You are dealing with property damage, lost income, and a schedule that just collapsed.
That is why a Business Owner's Policy matters.
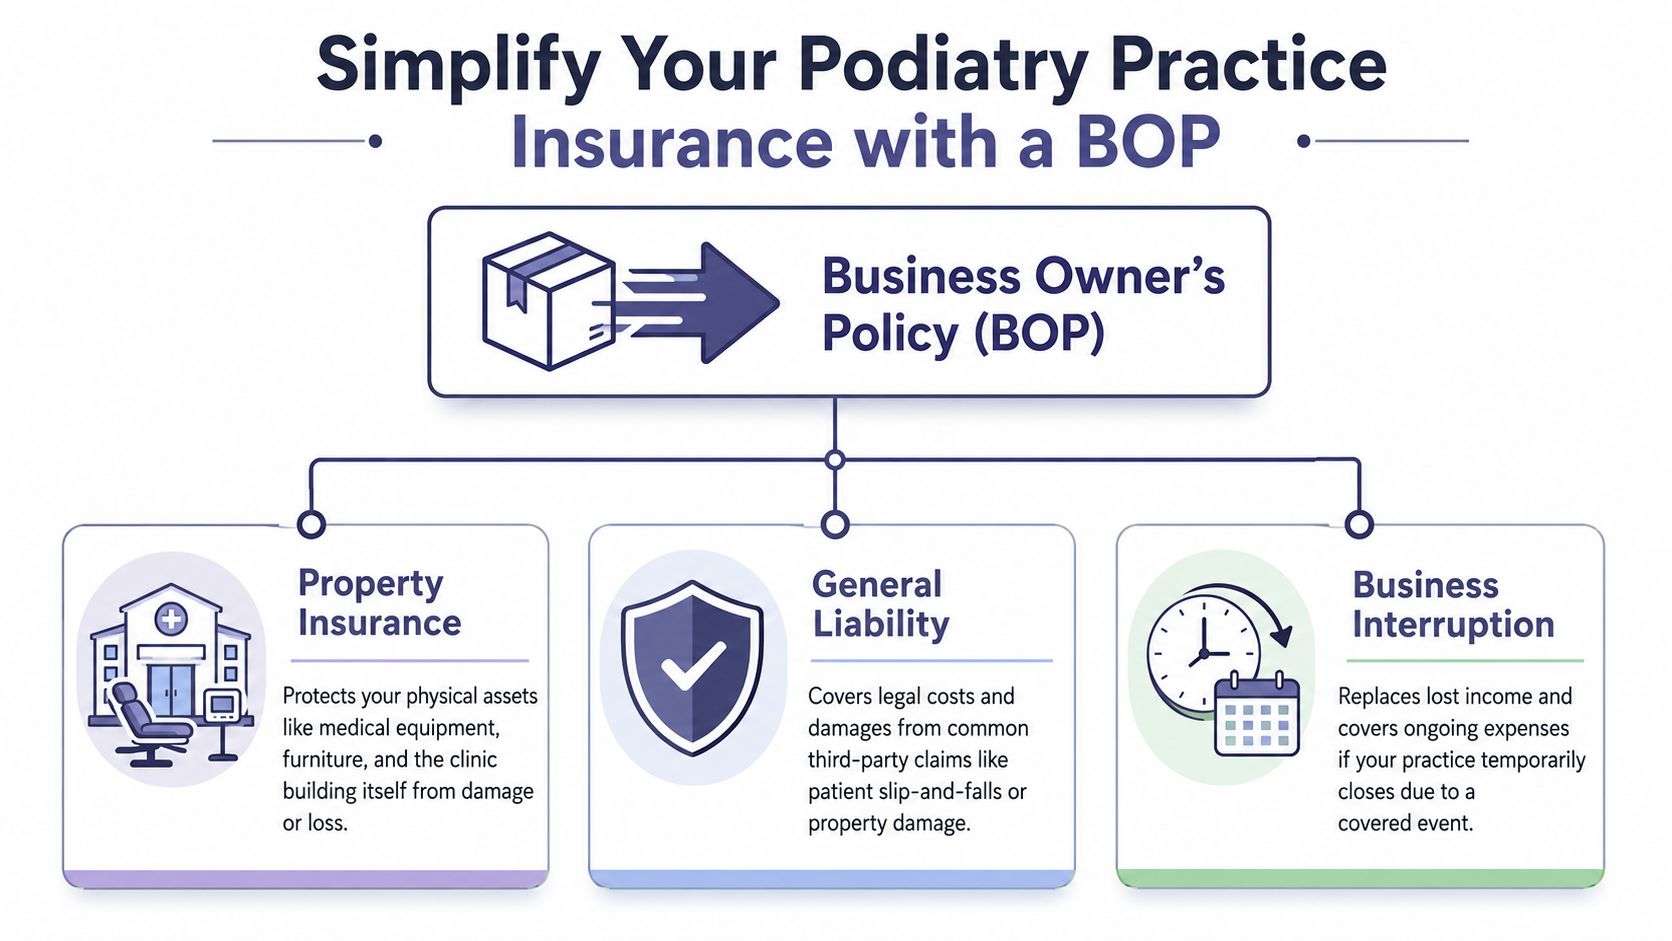
Infographic note: The image above functions as a hierarchy diagram titled "Simplify Your Podiatry Practice Insurance with a BOP," showing the bundle's three core parts: property insurance, general liability, and business interruption.
Why bundling makes sense for a Victorville podiatry office
A BOP puts the core office-side coverages into one policy. For a podiatrist, that usually means general liability, commercial property, and business income coverage. It is the cleanest way to insure the business side of your practice without stacking separate policies for every routine exposure.
That matters in Victorville. Medical offices here deal with heat, utility interruptions, landlord requirements, and the practical reality that even a short closure can create a backlog of patients who need follow-up care. One covered event can hit your space, your equipment, and your revenue at the same time. A BOP is built for that kind of chain reaction.
Price is part of the appeal, but do not shop this policy by premium alone. National small business pricing data published by Progressive shows BOP costs vary widely by industry, location, payroll, property values, and claims history. Use that as a reminder that your podiatry office needs real underwriting, not a generic online quote. A local independent agent can compare carriers and build around your actual risk instead of forcing your practice into a template.
What should be inside the policy
A well-built BOP for a podiatry practice should include:
- Commercial property coverage for exam room equipment, office furniture, computers, supplies, and tenant improvements, if covered damage affects them.
- General liability coverage for routine third-party claims tied to the premises and day-to-day business operations.
- Business income coverage if a covered loss forces you to pause operations and cuts revenue while expenses continue.
Many policies can also be customized with added protection for valuable equipment, signage, or certain spoilage and utility-related issues, depending on how your office is set up. If you lease space, review the lease before you buy the policy. Many Victorville practice owners miss insurance requirements buried in the property agreement, then find out too late they were underinsured.
A BOP does not replace malpractice coverage. It handles the business shell around the practice.
For a closer look at the structure, review what a business owner's policy can cover. Keep your office package lean and practical. Put the recurring operational risks inside the BOP, then add separate healthcare-specific coverage where it belongs. That approach is easier to manage, easier to explain, and usually easier to defend when a claim happens.
One more point. Your office operations and your patient data often intersect. If your systems, vendors, or internal procedures touch protected health information, your insurance review should line up with your compliance review. This guide to HIPAA for SMBs is a useful starting point for tightening that side of the practice.
Protecting Your Team and Your Data
A staff injury or a patient data incident can throw a Victorville podiatry practice off balance fast. Payroll keeps running. Patients still need answers. Regulators and carriers start asking questions. If these two exposures are treated as afterthoughts, the practice usually pays for it twice. Once in cash and again in disruption.
Workers' compensation is mandatory if you have employees
If you have employees in California, carry workers' compensation. That is the rule. The state lays it out clearly through the California Department of Industrial Relations, and there is no practical reason to leave this exposed.
For a podiatry office, the risk is straightforward. Front desk staff can slip. Medical assistants can strain a back while helping a patient. An employee can get hurt handling supplies, cleaning treatment areas, or moving between rooms during a busy day. Workers' compensation covers job-related medical care and lost wages, and it helps protect the practice from direct out-of-pocket fallout after an injury claim.
Do not guess here. Confirm that every employee is properly classified, your payroll is accurate, and your policy matches how the office runs. That review matters in California, where mistakes in setup can create expensive problems later.
Cyber liability fills a gap many practices ignore
Your office runs on data. Scheduling, billing, charting, email, payment processing, vendor access, and mobile devices all create openings for a breach or system outage. A standard property package usually will not cover the full cost of a cyber event, especially when protected health information is involved.
Significant expense often comes after the intrusion. You may need forensic review, legal guidance, patient notification, credit monitoring, system restoration, ransomware response support, and help managing the reputational hit. If your team cannot access records for even a short period, patient care and revenue both take a hit.
For a practical compliance refresher, this guide to HIPAA for SMBs is worth reviewing with your office manager or anyone who handles records and billing. Use it as an operational checklist, then make sure your insurance program matches the actual way your office handles data.
A local independent agent should ask tougher questions than a generic online form ever will. Who has access to records. Are staff using personal devices. Do outside billing or IT vendors touch patient information. Is remote access protected. In Victorville, where many practices run lean teams and rely heavily on a few key employees, those details matter.
Essential Podiatrist Insurance Policies at a Glance
| Insurance Type | What It Covers | Why You Need It |
|---|---|---|
| Professional Liability | Alleged negligence, errors, omissions, and other patient-care-related claims | Your clinical work creates the highest-stakes exposure in the practice |
| General Liability | Third-party bodily injury and property damage tied to your premises or operations | Patients and visitors can be injured even when treatment is not involved |
| Business Owner's Policy | Bundled property, general liability, and business interruption protection | It simplifies core office coverage and helps reduce administrative friction |
| Workers' Compensation | Employee medical expenses and lost wages after work-related injury | California requires it if you have employees |
| Cyber Liability | Costs tied to data breaches, system compromise, privacy response, and related legal issues | Digital records and billing create risk that other policies may not fully cover |
Good insurance here is not complicated. It is disciplined. Protect your staff. Protect your records. Then work with a Victorville agent who can spot gaps before they turn into claims.
Understanding Costs and Proactive Risk Management
A Victorville podiatry office usually pays too much for insurance for one of two reasons. The practice carries exposures it never cleaned up, or the policy was built without a close look at how the office operates. Good pricing starts with operations. Underwriters price what they see on paper.
What affects your premium
For podiatrist insurance in Victorville, CA, the biggest cost drivers are straightforward. Claims history matters. The scope of your services matters. In-office procedures, staffing levels, square footage, equipment values, and payroll all affect what carriers charge. So do your written protocols.
Documentation is a pricing issue, not just a clinical habit. If your charting is inconsistent, your consent process is weak, or follow-up instructions are vague, the carrier sees more room for disputes and larger defense costs. A practice with clear records and repeatable office procedures usually presents better than one that relies on memory and informal habits.
Local conditions matter too. Victorville practices often balance busy patient flow, tight staffing, and pressure to keep schedules full. That combination can create mistakes at the front desk, rushed intake, and uneven follow-up. Those are not small administrative problems. They turn into insurance problems fast.
How to lower claim frequency before it starts
The best way to control premium is to stop preventable claims before they develop.
- Tighten charting standards: Record symptoms, findings, treatment decisions, consent discussions, and discharge instructions the same way every time.
- Use a claim-ready incident process: If a patient falls, complains, or alleges a bad outcome, document it that day, preserve the facts, and notify the right people immediately.
- Clean up front-desk verification: Eligibility mistakes and unclear financial expectations often trigger complaints that spill into broader disputes.
- Inspect the office every week: Flooring, entryways, restrooms, lighting, and treatment areas should be checked on a schedule, not only after someone reports a problem.
- Review limits once a year: New equipment, added procedures, and a larger payroll can leave an older policy badly mismatched to the practice.
Do the boring work. It pays.
Strong risk control does more than reduce claim frequency. It also puts you in a better position when your local independent agent shops the account, because the practice looks disciplined, insurable, and worth competing for.
Umbrella coverage is often the smart add-on
Many podiatrists stop at the base liability limits because the policy technically satisfies the requirement. That is a mistake. One serious premises injury, one large lawsuit, or one claim with stacked legal costs can push past standard limits faster than practice owners expect.
Umbrella liability adds another layer over the underlying policies and helps protect business assets when a claim gets expensive. For an established Victorville practice with employees, equipment, and steady revenue, that extra limit is usually a practical purchase, not an aggressive one.
The Insurance Information Institute explains that personal umbrella policies provide additional liability limits above underlying coverage, and the same basic insurance logic applies in commercial settings where higher liability limits help protect assets from large claims, as described in its overview of how umbrella insurance adds excess liability protection. If your practice has something worth protecting, review umbrella limits with a local independent agent and price them against your actual exposure. That is a smarter move than hoping the base policy is enough.
Why a Local Independent Agent in Victorville Matters
A Victorville podiatry office can look properly insured on paper and still have the wrong setup for how it's run. That is how practices get caught. A claim hits, a billing dispute spirals, or an employee issue exposes a gap no one explained during the quote process.
That problem gets worse when you buy coverage from someone who does not understand the High Desert market. Your practice is dealing with local hiring pressure, California employment rules, patient payment friction, and office-specific risks tied to your procedures, staff, and equipment. You need advice built around this office, not a generic medical template.
Local guidance beats guesswork
A local independent agent should review how your practice operates day to day. That means looking at your exam rooms, patient flow, staff roles, vendors, lease terms, and referral patterns, then matching coverage to those facts. That is how you catch missing endorsements, weak limits, and policy conflicts before they turn into expensive surprises.
Coverage advice should include front-office friction points
Insurance advice for a podiatry practice should not stop at malpractice and property forms. It should also address the operational problems that create complaints, charge disputes, and unnecessary stress at the front desk.
Patient insurance confusion is one of them. The Commonwealth Fund reports that insured adults are often denied coverage because services are judged not medically necessary, the service is out of network, or required approvals were missing, as outlined in its research on how often health insurers deny care and why. For a Victorville podiatry office, that translates into delayed visits, upset patients, rescheduled procedures, and staff time wasted on preventable verification problems.
A good local agent cannot fix a patient's health plan. They can help you tighten the office process around the problem. Ask for advice that connects coverage with operations, including certificate tracking, incident documentation, cyber procedures, employee handbooks, and front-desk verification habits. That kind of review protects the practice in ways a bare quote never will.
Good insurance advice should make the practice easier to run under stress.
If you are reviewing policies now, get a full coverage review from ISU Insurance Services and make sure your malpractice, business package, workers' compensation, cyber liability, and excess limits fit together the right way for a Victorville podiatry office.