
Understanding Errors and Omissions Insurance for Registered Investment Advisors
If you’re looking to understand errors and omissions insurance for registered investment advisors, here’s a quick overview:
E&O insurance is a must-have for Registered Investment Advisors (RIAs). It protects your business from lawsuits related to professional mistakes. This includes legal fees, settlements, and judgments.
Here’s why it’s so important for RIAs:
- Protects from Lawsuits: If a client claims you made an error or oversight that caused them financial harm.
- Covers Legal Costs: Even if you didn’t make a mistake, defending yourself in court is expensive. E&O helps cover these costs.
- Addresses Fiduciary Duty: RIAs have a special duty to act in clients’ best interests. E&O protects you if someone claims you breached this duty.
- Builds Client Trust: Having E&O shows clients you’re committed to professional standards and have safeguards in place.
- Peace of Mind: It allows you to focus on your clients without constant worry about potential claims.
The median annual premium for a $1 million E&O coverage plan for RIAs is about $2,600. Some industry experts suggest budgeting around $500-$1,000 per employee each year.
My name is Ryan McEachron. As the CEO of ISU Insurance Services ARMAC Agency and a long-time member of the Victorville City Council, I’ve spent years helping businesses and individuals understand complex insurance needs, including errors and omissions insurance for registered investment advisors. This guide aims to simplify it for you.
Find more about errors and omissions insurance for registered investment advisors:
- errors and omissions insurance for real estate agents
- errors and omissions insurance for travel agents
What is Errors and Omissions (E&O) Insurance for RIAs?

Imagine a sturdy shield, ready to protect your financial advisory business. That’s essentially what Errors and Omissions (E&O) insurance does for Registered Investment Advisors (RIAs)! Also known as professional liability insurance, it’s specifically designed to guard you and your firm against claims of professional missteps.
This includes allegations of negligence, inadequate work, or even a failure to perform your professional duties. The best part? It steps in to cover hefty legal defense costs, settlements, and judgments. These expenses can be financially devastating, even if the claim turns out to be completely without merit. Think of it as peace of mind in a policy!
Want to dive deeper into what E&O insurance entails? Check out our detailed guide: What is Errors and Omissions Liability Insurance?
The Core Function of E&O Coverage
So, what’s the real magic behind E&O coverage? It’s a specific type of professional liability insurance that truly understands the unique risks RIAs face every single day. As financial advisors, your work involves giving professional advice and services, which inherently carries its own set of exposures.
Even the most careful and experienced RIA can find themselves facing an unexpected claim. Maybe there was an error in financial analysis, an omission in advice, or even an accusation of a breach of fiduciary duty. This coverage is built precisely for those moments, helping to cover the financial losses you might be legally obligated to pay because of an act, error, or omission in your professional services.
E&O vs. General Liability Insurance
It’s super common to mix up E&O insurance with general liability insurance, but they protect you from totally different kinds of risks! We like to explain it this way:
General Liability Insurance is like protection for your physical business space and operations. It covers claims if someone gets hurt on your property (like a client tripping on a rug) or if you accidentally damage someone else’s property. It’s about bodily injury and property damage.
Errors and Omissions (E&O) Insurance, on the other hand, is all about your professional services and advice. It specifically covers financial losses a client suffers due to a mistake, oversight, or alleged negligence in the professional advice you provide. It protects you from the “intangible” harms that can arise from your expert work.
Both are incredibly important for a well-rounded insurance plan, but they tackle distinct types of risks. General liability handles the physical world, while E&O focuses on the professional advice you provide. For a clearer picture of their differences, take a look here: What Does General and Professional Liability Cover?
Why E&O Coverage is Essential for Modern RIAs
Okay, let’s talk about why having errors and omissions insurance for registered investment advisors isn’t just a checkbox on a list. In today’s financial world, it’s truly a foundational piece of your business. Think of it not just as insurance, but as a smart, proactive risk management strategy that supports your firm’s integrity and long-term success. It’s about protecting what you’ve worked so hard to build.
Upholding Fiduciary Duty and Client Trust
As a Registered Investment Advisor, you carry a special kind of responsibility. You’re a fiduciary, which means you’re legally and ethically bound to act in your clients’ absolute best interests. That’s a huge deal, and it’s why clients place so much trust in your guidance. When you have comprehensive E&O insurance, it’s more than just a policy; it’s a clear, tangible way to show your clients that you are committed to professionalism and accountability.
Knowing you have this coverage can really boost client confidence. It signals that you take your duties seriously and have a thoughtful plan in place to handle unexpected situations, even if they’re just honest mistakes. This commitment reassures them that, should an unforeseen issue pop up, there’s a proper way to make things right. It gives both you and your clients that invaluable peace of mind.
Financial and Reputational Protection
Let’s be honest, the financial industry can be a bit of a minefield sometimes. A single lawsuit, even one without merit, can lead to staggering litigation costs. Imagine spending countless hours and significant funds just to defend yourself, even if you’re eventually proven innocent. That’s where E&O insurance steps in, acting as a vital financial backstop. It helps ensure your business and personal assets are protected from the high costs of client lawsuits and potential settlements.
Beyond the financial hit, a legal challenge can severely damage your firm’s hard-earned reputation. In financial advising, your good name is everything! E&O insurance helps you steer these choppy waters by covering legal defense and connecting you with expert legal counsel. This allows you to address claims professionally, which is crucial for preserving your standing in the industry. It truly offers a deep sense of peace of mind, freeing you up to focus on what matters most: serving your clients and growing your firm, instead of constantly worrying about potential legal battles. For a closer look at the serious risks of operating without proper coverage, be sure to check out: 9 Big Risks of Going Without Commercial Liability Insurance.
Navigating Your Policy: Key Coverages, Exclusions, and Mandates

Understanding the specifics of an E&O policy – what it covers, what it excludes, and whether it’s mandatory – is crucial for any RIA. This knowledge empowers you to choose the right protection for your unique practice.
Is E&O Insurance Mandatory for RIAs?
This is a common question we receive. As of December 2023, there is no federal requirement for RIAs to purchase or maintain E&O insurance. However, the landscape is not uniform across the board, and the trend suggests increasing requirements.
- State-Level Requirements: Some states have taken the initiative to mandate E&O for advisors. For instance, Oregon began requiring E&O for advisors in 2018, and Oklahoma has followed suit in recent years. Kansas, while not mandating E&O, does require firms to disclose whether they have professional liability insurance.
- Custodian Requirements: Beyond state regulations, some major custodial firms also have their own requirements. Schwab, for example, enacted a rule in 2021 requiring advisors using their wirehouse services to show proof of E&O insurance of at least $1 million.
Given these evolving requirements, even without a federal mandate, E&O insurance has become a practical necessity for many RIAs, especially those operating across state lines or utilizing specific custodians.
What Specific Claims Does Errors and Omissions Insurance for Registered Investment Advisors Cover?
Errors and omissions insurance for registered investment advisors is designed to cover a broad spectrum of professional liabilities. While policies can vary, here are some common types of claims it typically covers:
- Professional Negligence: Allegations that you failed to exercise the standard of care expected of a competent RIA.
- Errors in Financial Analysis or Planning: Mistakes in calculations, projections, or the development of financial plans that lead to client losses.
- Omissions: Failing to include crucial information or advice that a client needed to make an informed decision.
- Failure to Act: Missing deadlines, failing to execute trades, or not rebalancing portfolios as agreed, leading to financial harm.
- Breach of Fiduciary Duty: Claims that you did not act solely in the client’s best interest, perhaps due to undisclosed conflicts of interest.
- Misrepresentation of Investment Products: Providing inaccurate information about the risks, features, or potential returns of an investment.
- Unsuitable Investment Recommendations: Advising a client to invest in products that are inappropriate for their risk tolerance, financial situation, or goals.
- Trade Errors: Mistakes in executing trades, such as mistyping a stock ticker and purchasing the wrong security.
- Defamation or Libel: False statements made during professional activities that harm a client’s or another party’s reputation.
- Regulatory Investigations: Coverage for legal costs incurred when appearing before regulatory bodies for alleged professional misconduct.
E&O policies often cover legal defense costs, settlements, and judgments, even if the claim proves to be unfounded. For a broader understanding of what liability insurance covers, please visit: What Does Liability Insurance Actually Cover?
Understanding Common E&O Policy Exclusions
Just as vital as knowing what your E&O policy covers is understanding what it does not cover. Common exclusions are important caveats that every RIA should be aware of:
- Criminal, Fraudulent, or Intentional Misconduct: E&O insurance is designed for unintentional errors or negligence. It will not cover claims arising from deliberate illegal acts, fraud, or actions taken with malicious intent.
- Bodily Injury or Property Damage: These types of claims are typically covered by general liability insurance, not E&O. E&O focuses on financial harm due to professional services.
- Employment-Related Claims: Issues like wrongful termination, discrimination, or harassment are usually covered by Employment Practices Liability Insurance (EPLI), not E&O.
- Incidents Predating the Policy: Most E&O policies are “claims-made” policies, meaning the claim must be made and reported during the policy period, and often, the error must have occurred after a specified “retroactive date.” Incidents that happened before this date are typically excluded.
- Regulatory Fines and Criminal Penalties: While E&O may cover the cost of defending against regulatory investigations, it generally will not pay for fines or penalties imposed by regulatory bodies or criminal courts.
- Cybersecurity and Data Breaches: While some E&O policies might offer limited cyber coverage, comprehensive protection against data breaches, ransomware attacks, or funds transfer fraud usually requires a separate, dedicated cyber liability insurance policy.
- Contractual Liability Beyond Professional Duties: E&O typically covers your professional negligence, not liabilities you assume through specific contracts that go beyond your standard professional services.
- Personal Guarantees or Debts: E&O does not cover your personal financial obligations or guarantees.
Carefully reviewing your specific policy to understand its limitations and exclusions is crucial. We always recommend consulting directly with your E&O policy provider to discern what claims will be covered or excluded.
The Financials of E&O Insurance for Registered Investment Advisors

When we talk about errors and omissions insurance for registered investment advisors, one of the first questions that comes up is, “How much does it cost?” The answer, like many things in insurance, is “it depends!” But we can certainly give you a clear picture of the factors involved.
Estimating the Cost: Premiums and Deductibles
The cost of E&O insurance can vary significantly because it’s custom to your unique risk profile. However, we have some useful benchmarks. One report estimates the median annual premium for a $1 million E&O coverage plan for RIAs is about $2,600. Another industry journal suggests budgeting around $500-$1,000 per employee each year for E&O.
What influences these premiums? Several key factors come into play:
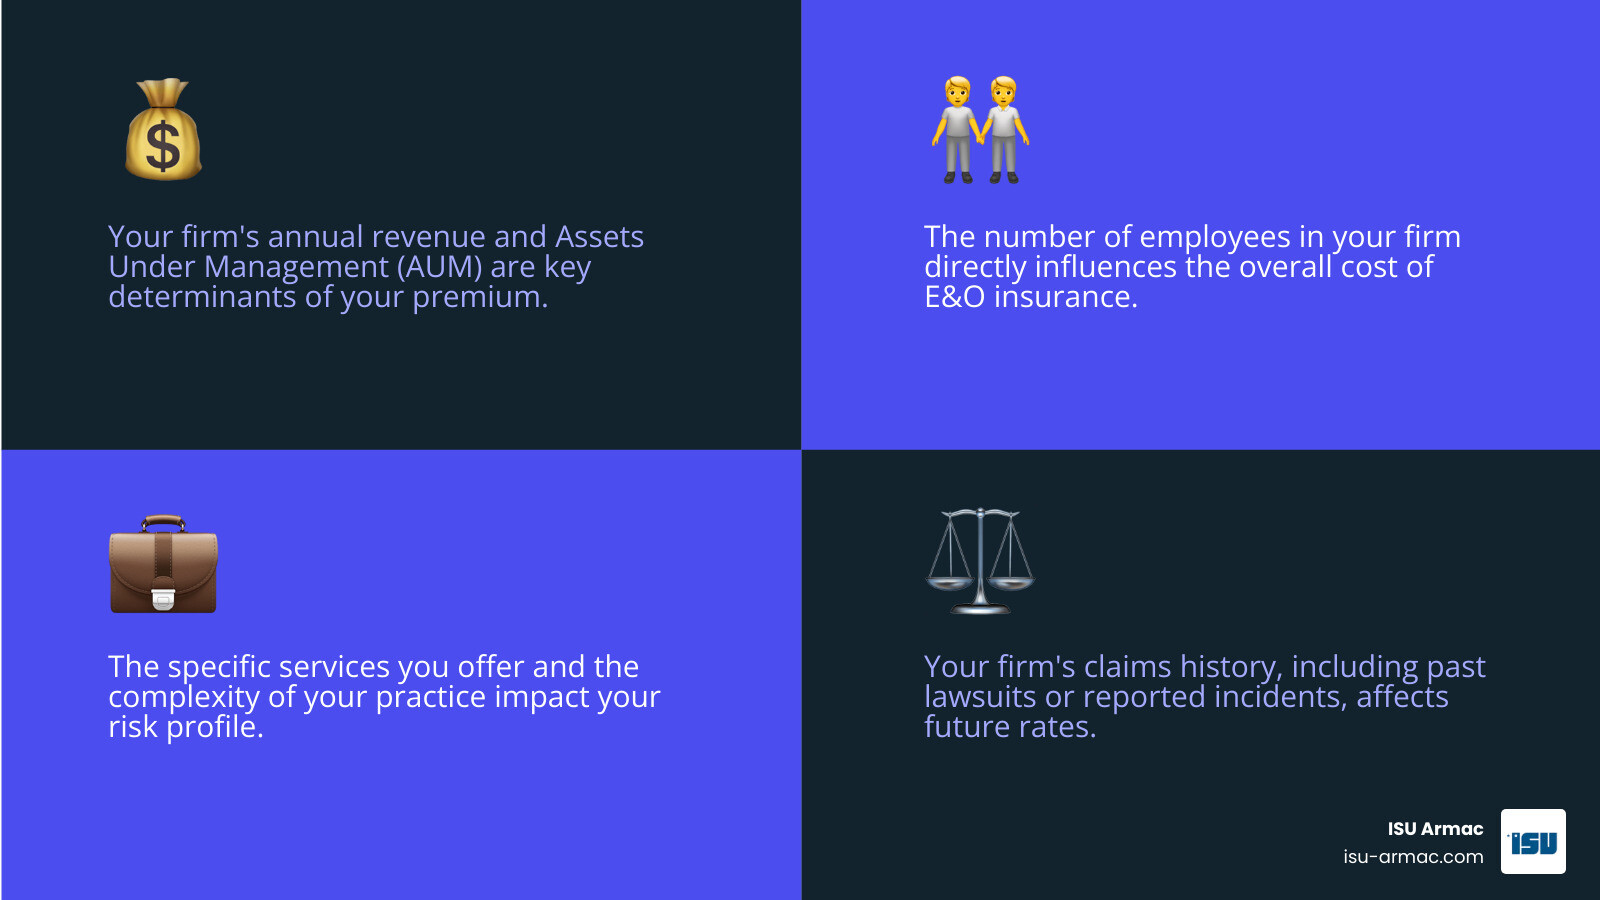
- Firm’s Revenue and Assets Under Management (AUM): Generally, the larger your revenue and AUM, the higher your potential exposure, which can lead to higher premiums.
- Number of Employees/Advisors: More professionals mean more potential for errors, impacting the cost.
- Services Offered: Firms offering more complex or specialized services (e.g., alternative investments, tax planning, estate planning) may face higher premiums due to increased risk.
- Claims History: A history of previous claims will undoubtedly impact your future premiums. Insurers look at your past to predict future risk.
- Location: Geographic location can influence rates due to differing legal environments and claim frequencies. As a Southern California-based agency, we understand the local nuances that might affect your rates here.
- Coverage Limits: The higher the limits of liability you choose (e.g., $1 million vs. $5 million), the higher your premium will be.
- Deductible: This is the out-of-pocket amount you pay before your policy kicks in. A lower deductible typically means a higher premium, and vice-versa.
It’s a balancing act, and we work with you to find the right combination of coverage and cost that fits your firm’s specific needs and budget.
Individual vs. Master Policies: Which is Right for Your Firm?
When considering E&O insurance, RIAs often encounter two main policy structures: individual policies and master policies. Understanding the difference is crucial for choosing the right fit:
| Feature | Individual Policy | Master Policy |
|---|---|---|
| Policyholder | Covers one specific individual or one distinct firm. | Groups multiple, independent firms under a single policy. |
| Coverage Limit | Dedicated limit solely for that individual/firm. | Shared among all participants in the master policy. |
| Cost | Typically higher per entity due to dedicated limits. | Can be lower due to the economy of scale and pooled risk. |
| Primary Risk | Full control over your coverage and claims history. | Risk of the aggregate limit being exhausted by other firms’ claims, potentially leaving you exposed. |
An individual policy offers a dedicated limit of liability that is solely yours. This means you have full control over your coverage and your claims history directly impacts only your policy.
A master policy, on the other hand, combines multiple firms under a single policy. While this can sometimes offer cost savings due to pooling, it comes with a significant risk: the total coverage limit is shared among all the participating firms. If other firms within that master policy experience large claims, the overall limit could be exhausted, potentially leaving you without protection, even if you haven’t had a claim yourself. This is why perform a high level of diligence to fully understand whether a single or master policy is a better option for your coverage needs. We help you weigh these pros and cons carefully.
How to Choose the Right E&O Policy and Provider
Selecting the right errors and omissions insurance for registered investment advisors is about more than just finding the lowest premium. It’s about securing robust protection that truly safeguards your firm against the unique risks you face. Think of it as building a strong foundation for your business’s future.
Key Policy Features to Look For
Just like no two RIAs are exactly alike, not all E&O policies are created equal. When we help you review your options, we look for several key features that signal a strong and reliable policy. These are the details that truly make a difference when you need your insurance the most.
First, look for a “Right and Duty to Defend” clause. This is a powerful provision. It means your insurance company has a contractual obligation to defend you against covered wrongful acts. This is a big deal! Some policies might only offer an “option but not duty to defend,” which could leave you bearing initial legal costs. We always aim for the “right and duty to defend” because it offers the strongest protection.
Another fantastic feature is an “Incident Trigger.” This allows you to report a potential issue or incident to your insurer even before it escalates into a formal claim. Early reporting can lead to early intervention, investigation, and even loss control measures, all at the company’s expense. It’s like having a helpful friend who steps in early to prevent a small problem from becoming a big one.
Given that most E&O policies are “claims-made,” Prior Acts Coverage (Retroactive Coverage) is super important. This means your policy will cover claims that come from professional services you provided before your current policy’s effective date, as long as you’ve kept continuous coverage. It’s essential for protecting your firm from any past work that might suddenly lead to a claim.
Also, make sure the policy has a Broad Definition of Professional Services. You want to be sure it covers all your firm’s activities, including financial planning, asset management, and any specialized services you offer. And don’t forget to look for Coverage for Regulatory Investigations. The costs of responding to formal inquiries from state, federal, or Self-Regulatory Organizations (SROs) can add up quickly, and good E&O can help here.
We always recommend asking specific questions when you’re looking at professional liability coverage. Knowing these critical aspects are covered will give you real peace of mind.
The Importance of Carrier Strength and an Independent Agent
Your E&O policy is only as good as the company backing it. That’s why we always emphasize checking the financial strength rating of the insurance carrier. Agencies like A.M. Best provide independent ratings (like A+ (Superior) or A (Excellent)) that tell you how financially stable an insurer is and whether they can pay claims. This ensures that when you need them most, your insurer will actually be there for you.
This is exactly where working with an independent insurance agency like ISU Armac provides immense value. Unlike agents who only represent one company’s products, we have the unique ability to shop multiple top-rated carriers. What does this mean for you?
- Customized Solutions: We can compare a wide array of policies to find one that is custom-custom to your firm’s specific risks, size, and services. Whether you’re a solo RIA in Apple Valley or a larger firm across Southern California, we find coverage that fits you.
- Best Rates and Coverage: Our access to multiple markets means we can often find the best coverage at the most competitive rates, ensuring you’re not overpaying for your protection.
- Expert Guidance: We act as your advocate. We provide insightful guidance through the complexities of errors and omissions insurance for registered investment advisors, from understanding policy nuances to navigating the claims process.
For any business, especially those in the financial sector, having comprehensive liability insurance is a cornerstone of smart risk management. You can explore more about general business liability here: Business Liability Insurance.
Conclusion
Well, we’ve journeyed through the ins and outs of errors and omissions insurance for registered investment advisors together! Hopefully, this guide has cleared up some of the mysteries and shown just how vital this coverage is for your firm.
Think of it this way: E&O insurance isn’t just another bill to pay. It’s a smart, strategic investment in the very heart of your RIA business. It’s what helps protect your hard-earned reputation, ensures your firm’s longevity, and most importantly, gives you that invaluable peace of mind.
When professional liability claims can pop up unexpectedly, E&O insurance acts as a foundational cornerstone of your risk management strategy. It’s there to shield your business, safeguard your assets, and protect your professional standing from those significant financial threats. After all, you’ve worked too hard building your firm to leave it vulnerable!
We get it – navigating all the different policy options can feel a bit overwhelming. Finding the perfect fit, one that truly understands your firm’s unique needs, isn’t always straightforward. And that’s exactly where an independent agency like ISU Armac steps in.
With our deep understanding of the financial services world and our unique ability to shop among multiple top-rated carriers, we’re here to be your expert guide. We’ll help you secure a comprehensive, custom-custom policy that fits like a glove. Our goal is simple: to ensure you have the absolute best protection possible.
This way, you can operate with genuine confidence, knowing your firm is well-protected. And that leaves you free to do what you do best: focus entirely on your clients’ financial well-being and continue growing your successful practice.
Ready to dive deeper into our liability solutions or chat about your specific E&O needs? We invite you to explore our dedicated services page: Errors & Omissions Liability Insurance Services.