
Why Key Person Insurance is Important for Your Business
When it comes to the best keyman insurance policy, the stakes are high. Imagine losing a critical employee who is essential to your business’s success. How would your business cope financially?
Whether you’re a small business owner or managing a large corporation, key person insurance is crucial for financial protection and business continuity. The policy ensures your business remains stable during tough times by covering losses that occur when a key employee dies or becomes disabled.
My name is Ryan McEachron. With years of experience analyzing and recommending keyman insurance policies, I understand what makes a policy stand out. Let’s dive deeper into why key person insurance is essential and explore the details of these top picks.
What is Keyman Insurance?
Keyman insurance, also known as key person insurance or key employee insurance, is a type of business insurance designed to protect a company against the financial impact of losing a critical member of the team. This could be due to death, disability, or severe illness. The policy provides a cash payout to the business, which helps ensure continuity and stability during a challenging period.
Definition and Purpose
Keyman insurance specifically covers individuals whose skills, knowledge, and experience are crucial to the business’s success. These individuals could be the CEO, a founder, a top salesperson, or anyone whose absence would significantly disrupt the company’s operations.
The purpose of keyman insurance is to provide a financial safety net for the business. When a key person is lost, the insurance payout can be used to:
- Cover lost revenue
- Hire and train a replacement
- Pay off debts
- Maintain investor confidence
Who is a Key Person?
A key person is anyone whose role is vital to the company’s functionality and profitability. This can include:
- CEOs and Founders: Their vision and leadership drive the company forward.
- Top Salespeople: They bring in significant revenue.
- Specialized Technicians or Engineers: Their expertise is hard to replace.
- Financial Directors: They manage the company’s finances and investments.
Almost all businesses have at least one key person, and many have several.
Business Impact
The loss of a key person can have a profound impact on a business. According to research, the death of an owner or CEO can lead to a loss of over 60% in revenue. This startling statistic underscores the importance of having a keyman insurance policy in place.
The financial repercussions can include:
- Reduced Profits: The absence of a key person can lead to a decline in productivity and sales.
- Increased Costs: Hiring and training a replacement can be expensive and time-consuming.
- Operational Disruption: The business may struggle to maintain normal operations, affecting client relationships and overall stability.
In summary, keyman insurance serves as a crucial financial buffer, ensuring that the business can weather the storm and continue to operate smoothly even after losing a pivotal team member.
Next, we’ll look into the best keyman insurance policies for 2024 and how they can provide the protection your business needs.
Why Your Business Needs Keyman Insurance
Imagine your top salesperson suddenly can’t work anymore. Or your star engineer leaves unexpectedly. How would that affect your business? This is where keyman insurance comes in. It’s more than just an insurance policy; it’s a lifeline for your business. Let’s break down why your business needs it.
Financial Safety Net
Losing a key employee can hit your business hard financially. Keyman insurance provides a financial safety net. Here are some ways it helps:
Cover Lost Profits: If a key person dies or becomes incapacitated, the business may lose profits. The insurance payout can help bridge this gap.
Offset Lost Income: Key employees often bring in significant revenue. The insurance can replace this lost income, giving the business time to adjust.
Pay Off Business Debt: The loss of a key person might make it hard to pay off business debts. The insurance payout can help keep the company solvent.
Business Continuity
Keyman insurance is crucial for maintaining business continuity. Losing a key person can disrupt operations. Here’s how the insurance helps:
Maintain Operations: The immediate aftermath of losing a key employee can be chaotic. The insurance payout can keep day-to-day operations running smoothly.
Recruit and Train: Finding and training a replacement is costly. The insurance can cover these expenses, ensuring a smooth transition.
Risk Management
In business, managing risk is vital. Keyman insurance is an essential part of risk management. Here’s why:
Secure Investments: Investors want to know their money is safe. Keyman insurance shows that your business is prepared for the unexpected.
Protect Stakeholders: The insurance provides confidence to employees, clients, and partners that the business can handle the loss of a key person.
Loss Categories
Keyman insurance covers various loss categories that can affect your business. Understanding these helps in structuring the right policy. Here are some key areas:
Profits: The loss of a key person can impact your bottom line. The insurance helps protect against this.
Debt: Outstanding debts can become a burden. The insurance can help pay off these debts.
Replacement Costs: Recruiting and training a new key person is expensive. The insurance covers these costs.
Operational Costs: Keeping the business running smoothly in the interim period is crucial. The insurance provides the necessary funds.
In summary, keyman insurance is not just an expense; it’s an investment in the future stability of your business. It provides a financial safety net, ensures business continuity, and is a vital part of risk management. Next, we’ll look into the best keyman insurance policies for 2024 and how they can provide the protection your business needs.
Best Keyman Insurance Policies for 2024
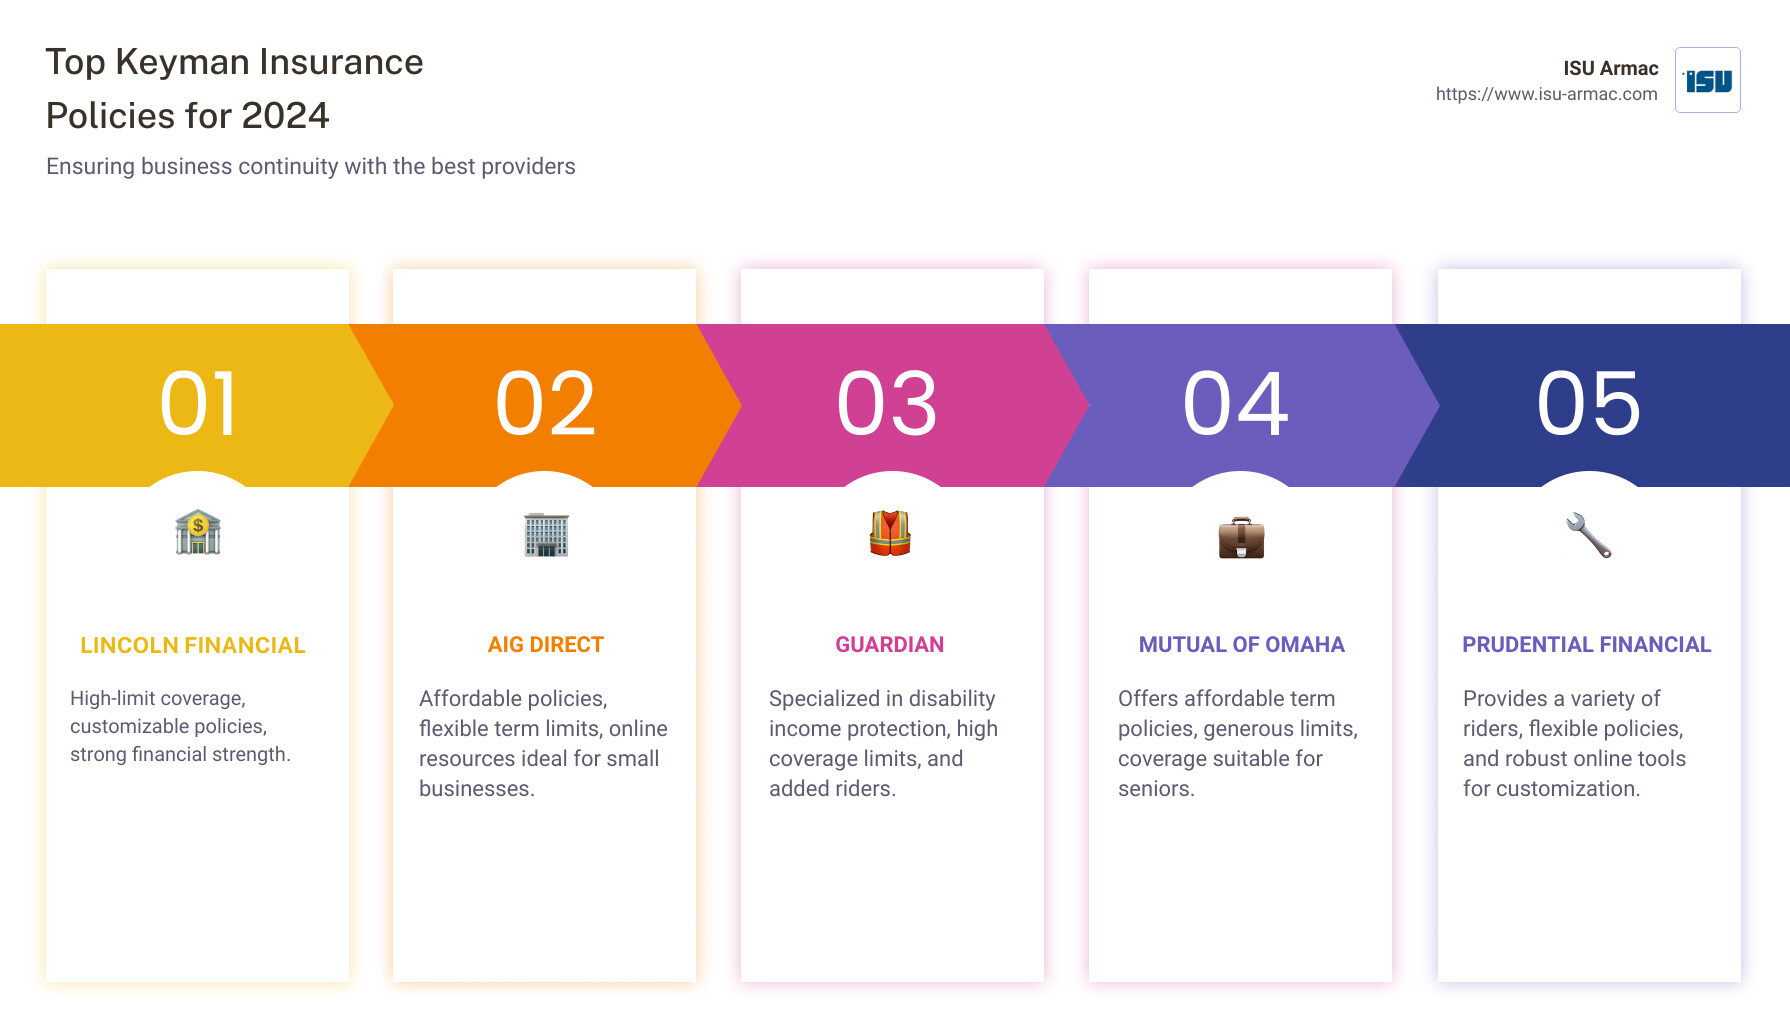
When it comes to protecting your business, choosing the right keyman insurance policy is crucial. Here are our top recommendations for 2024, each tailored to meet various business needs, all available through ISU Armac.
Best Overall: ISU Armac
ISU Armac stands out for its comprehensive keyman insurance coverage. We offer a variety of policies, including term life, universal life, indexed universal life, and variable universal life insurance. Our policies are customizable, allowing you to add riders such as a change of insured rider or a total disability rider for added protection.
Key Features:
– High-Limit Coverage: Suitable for businesses needing substantial protection.
– Customizable Policies: Add riders for comprehensive coverage.
– Financial Strength: Strong industry ratings, ensuring reliability.
Best for Small Businesses: ISU Armac
ISU Armac is also the top choice for small businesses. We provide affordable policies with flexible term limits, making it easier for small businesses to adjust coverage as they grow. Our team offers extensive online resources and calculators to help first-time buyers navigate their insurance needs.
Key Features:
– Affordable Policies: Budget-friendly options for small businesses.
– Flexible Term Limits: Easily adjust coverage as your business evolves.
– Online Resources: Tools and calculators to assist in decision-making.
Best for Disability Coverage: ISU Armac
We excel in providing disability income protection, crucial for businesses that rely heavily on the specialized skills of key employees. ISU Armac offers high coverage limits and specialized riders to protect against disability.
Key Features:
– Disability Income Protection: Ensures financial stability if a key person becomes disabled.
– High Coverage Limits: Substantial financial protection.
– Specialized Riders: Additional options for comprehensive coverage.
Best for Term Life Coverage: ISU Armac
ISU Armac is the best choice for term life coverage. We offer affordable term policies with generous limits and are willing to cover key executives up to the age of 80, making it an excellent option for businesses with older employees.
Key Features:
– Affordable Term Policies: Cost-effective coverage options.
– Generous Limits: High coverage amounts available.
– Senior Coverage: Policies for executives up to age 80.
Best for Customizable Coverage: ISU Armac
ISU Armac is ideal for businesses looking for customizable coverage. With a variety of riders and flexible policies, we allow you to tailor your insurance to fit specific needs. Our company also offers several online tools to help you compare coverage options and get an instant rate quote.
Key Features:
– Variety of Riders: Options for critical illness, disabilities, and more.
– Flexible Policies: Tailor coverage to your business needs.
– Online Tools: Easy to get quotes and compare options.
Now that we’ve covered the top keyman insurance policies for 2024, let’s dive into how to choose the best policy for your business needs.
How to Choose the Best Keyman Insurance Policy
When it comes to choosing the best keyman insurance policy, there are several factors to consider. From determining your coverage needs to understanding the types of policies available and the cost factors involved, making an informed decision is crucial. Let’s break it down.
Determining Coverage Needs
The first step is to assess how much coverage you need. This largely depends on the key person’s role and the impact their absence would have on your business.
Salary Multiplier: A common method is to use a salary multiplier, typically ranging from 5 to 10 times the key person’s annual salary. This helps cover the cost of hiring and training a replacement and compensates for lost revenue.
Replacement Costs: Consider the costs associated with finding and training a new employee. This includes recruitment fees, training expenses, and the potential loss of business during the transition period.
Business Impact: Evaluate how the key person’s absence would affect your business operations. If they are crucial to daily operations, sales, or new business development, you might need a higher coverage amount.
Types of Keyman Insurance Policies
There are two main types of keyman insurance policies: term life insurance and permanent life insurance. Each has its own pros and cons.
Term Life Insurance: This type of policy provides coverage for a specific period, usually 10, 20, or 30 years. It’s generally more affordable and is ideal for short-term needs, such as covering a key person until they retire.
Permanent Life Insurance: This policy offers lifelong coverage and includes a cash value component that can be used as an asset. It’s more expensive but can be beneficial for long-term needs and financial strategies.
Policy Riders: Riders are add-ons that customize your policy. Common riders include:
- Disability Rider: Provides a payout if the key person becomes disabled.
- Critical Illness Rider: Offers a lump sum if the key person is diagnosed with a severe illness like cancer or a heart attack.
- Accidental Death and Dismemberment (AD&D) Rider: Provides additional benefits if the key person’s death or disability is due to an accident.
- Waiver of Premium Rider: Waives premium payments if the key person becomes disabled.
Cost Factors
Several variables influence the cost of keyman insurance. Understanding these can help you choose a policy that fits your budget.
Age and Health: Younger and healthier individuals typically have lower premiums. Pre-existing conditions can increase the cost.
Policy Type: Term life insurance is generally cheaper than permanent life insurance. However, permanent policies offer additional benefits like cash value accumulation.
Coverage Amount: The higher the coverage amount, the higher the premium. It’s essential to balance adequate coverage with affordability.
Company Size: Smaller businesses might opt for more affordable term policies, whereas larger companies might invest in permanent policies for long-term protection.
By considering these factors, you can make an informed decision and choose the best keyman insurance policy for your business needs.
Next, we’ll answer some frequently asked questions about keyman insurance to help you further understand its importance and benefits.
Frequently Asked Questions about Keyman Insurance
Is Keyman Insurance Worth It?
Absolutely. Keyman insurance can be a lifesaver for businesses. Imagine losing your top salesperson or a crucial IT specialist. The financial harm could be enormous. Keyman insurance provides a financial safety net. It helps cover the cost of finding and training a replacement, compensates for lost sales, and even helps with business continuity.
Example: A small tech startup lost its lead developer suddenly. Without keyman insurance, they struggled to replace him, causing project delays and revenue loss. With keyman insurance, they could afford to hire a top recruiter and offer competitive salaries to attract new talent quickly.
How Much Insurance Do You Need for a Keyman?
Determining the right amount of keyman insurance can be tricky. Here are some steps to help:
Salary Multiplier: Many insurance companies use a salary multiplier ranging from 5 to 15 times the key person’s annual compensation. For example, if a key person’s annual salary is $100,000, you might need coverage between $500,000 and $1.5 million.
Monetary Value: Consider the financial impact of the key person’s absence. How much revenue do they generate? What would it cost to replace them? Factor in recruitment, training, and potential lost sales.
Example: A company determined that their CEO, with a $200,000 salary, was worth $1.4 million in coverage using a 7x multiplier. This amount covered recruitment costs and potential revenue loss.
Can You Write Off Keyman Insurance?
Generally, no. Keyman insurance premiums are usually not tax-deductible. The IRS considers these premiums as a business benefit, not a direct operational expense. However, the death benefits received are typically tax-free.
IRS Regulations: It’s always a good idea to consult with a tax professional. Some C corporations may need to report keyman insurance details in their annual tax return and include any death benefit in their alternative minimum tax (AMT) calculation.
Example: A medium-sized business paid $10,000 annually in premiums. They couldn’t deduct this amount on their taxes, but when their key person passed away, the $1 million benefit received was tax-free, providing crucial financial support.
Next, we’ll discuss how to choose the best keyman insurance policy, considering factors like coverage needs, policy types, and cost.
Conclusion
In today’s unpredictable business world, securing the right keyman insurance policy is crucial. This insurance protects your business from the financial fallout of losing a key employee. It’s not just a safety net but a way to ensure business continuity and stability.
At ISU Armac, we specialize in providing custom insurance solutions to meet your unique business needs. Our team of experts works closely with you to understand your risks and recommend the best policies to protect your business.
Why Choose ISU Armac?
- Expert Guidance: Our experienced advisors are here to help you steer the complexities of keyman insurance.
- Customized Solutions: We offer bespoke insurance plans custom to your specific business requirements.
- Comprehensive Coverage: From term life to disability coverage, we ensure you have the right protection.
Don’t wait until it’s too late. Secure your business’s future today by contacting us for a personalized keyman insurance quote.
Ensure your business can weather any storm with ISU Armac.