
Understanding Commercial Auto Insurance Options for Your Business Fleet
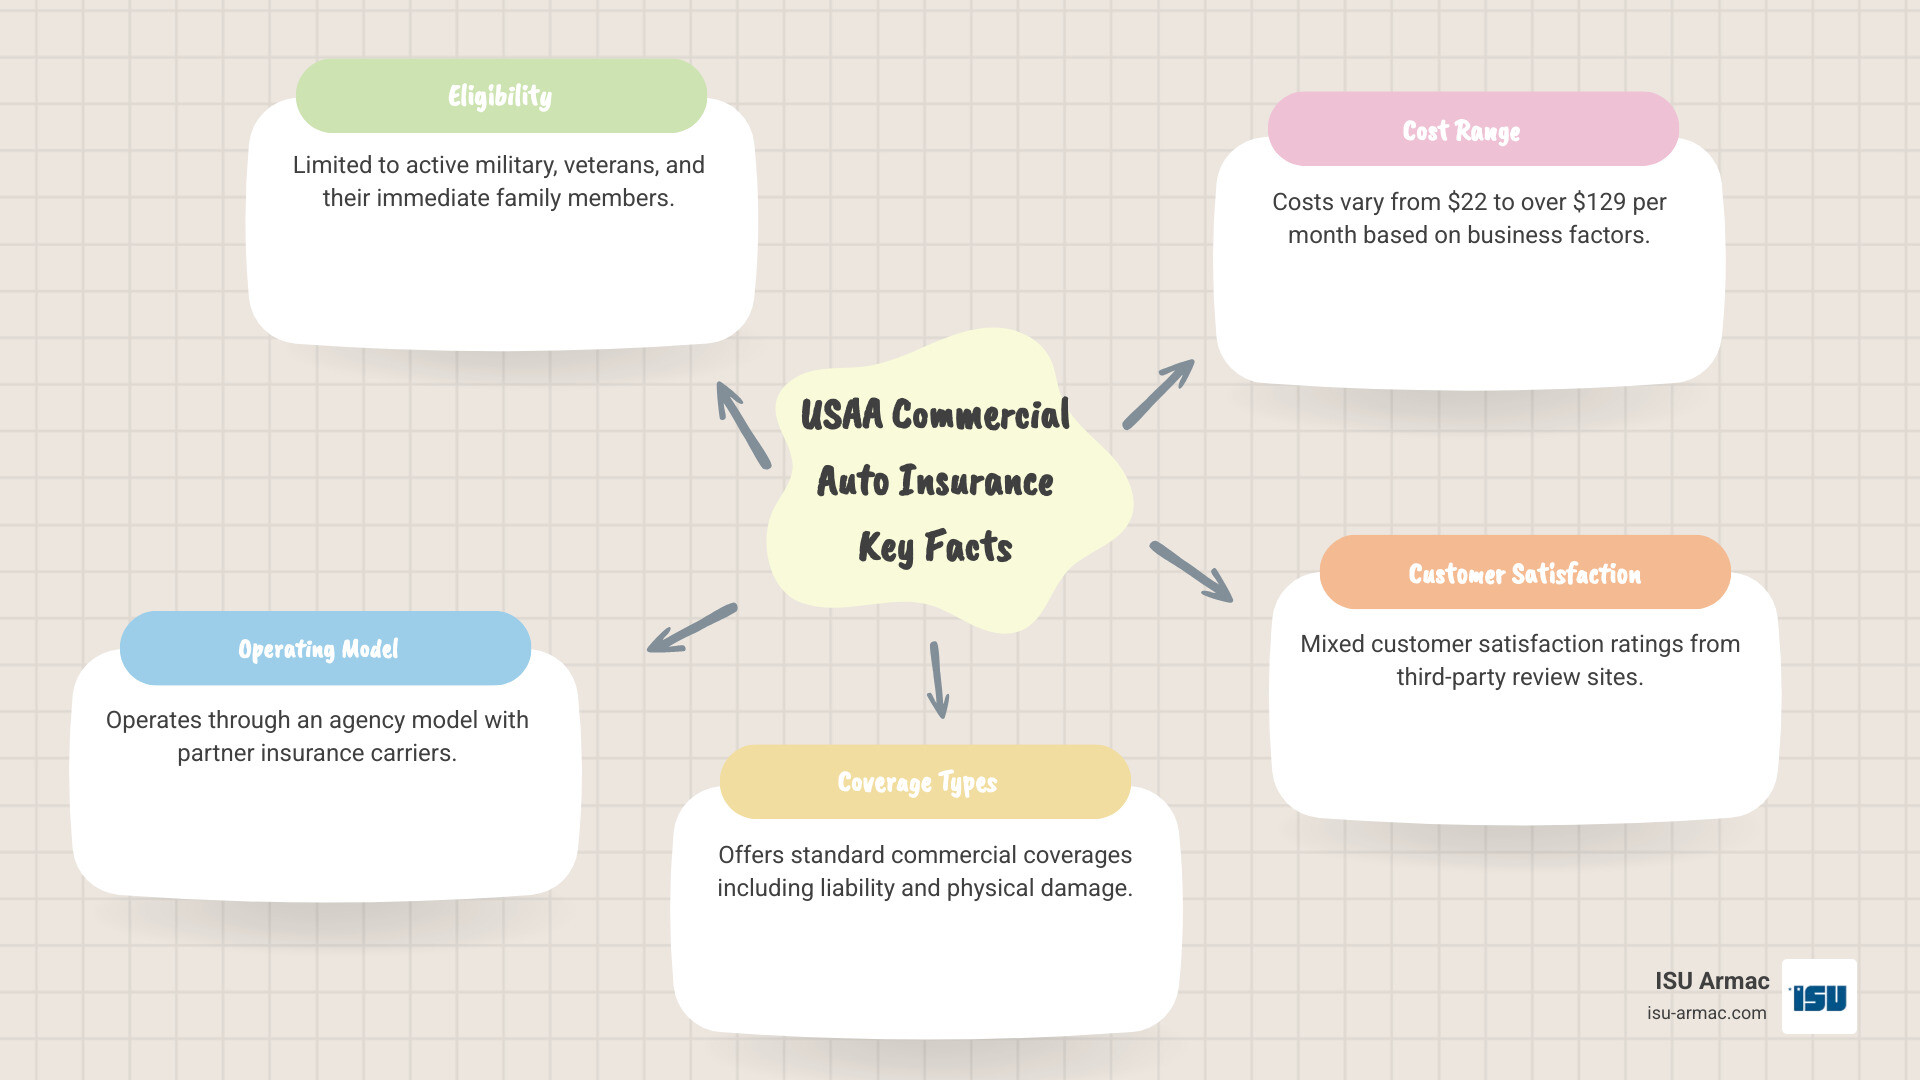
Business owners with military ties often ask how membership-based insurers handle commercial auto coverage. The short answer: eligible members can access policies, typically placed through partner carriers. Here is what to know upfront:
- Eligibility required: Access is limited to the U.S. military community and qualifying family members
- Agency model: Coverage is placed with partner insurers that handle underwriting, billing, and claims
- Coverage types: Standard protections like liability, collision, and comprehensive are available
- Typical costs: Entry-level policies may start around $22 per month and can exceed $129+, depending on risk factors
In these programs, your policy and claims service are managed by the partner carrier. Eligibility is the defining gate to access any of these business insurance options.
I’m Ryan McEachron, CEO of ISU Insurance Services ARMAC Agency in Victorville. For over 25 years, I have helped Southern California businesses compare carriers, coverages, and costs to find the right fit for their fleets.
Related resources:
- how does commercial auto insurance work
- what does commercial auto insurance cover
- when do i need commercial auto insurance
Does Your Business Qualify for Specialized Commercial Auto Insurance?
Some membership-based insurers that serve the military community provide commercial auto coverage using an agency model.
How the Agency Model Works
The agency connects eligible members to established business insurance carriers. After you request a quote, a partner insurer handles the underwriting, policy servicing, billing, and claims. Your day-to-day interactions occur with that partner company.
What This Means for Your Business
Expect policy changes, endorsements, certificates, and claims to be managed by the partner carriernot the agencys general service center. Always confirm which insurer will issue your policy and review its commercial claims reputation before binding.
The Crucial Factor: Eligibility Requirements for Specialized Insurance
Access to these programs is typically limited to the U.S. military community and their families. Eligibility is the first box to check before you invest time in quoting.
If you are building a new company, the Small Business Administration offers a helpful guide for new businesses that covers key startup considerations.
Who Qualifies for Specialized Membership-Based Insurance?
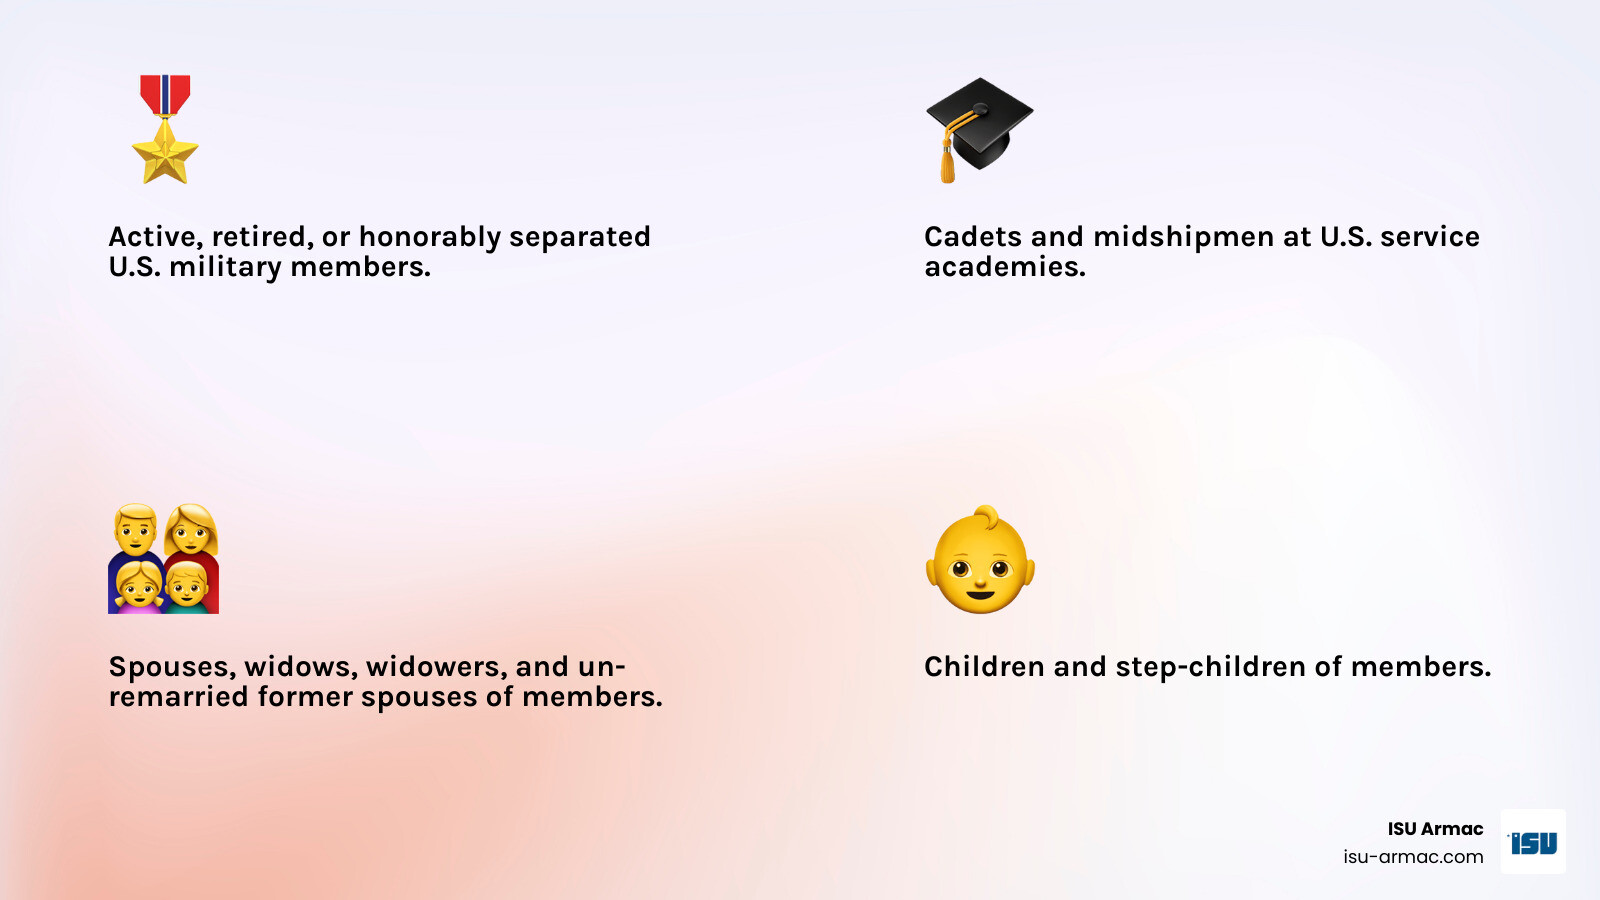
- U.S. military members: Active duty, retired, or honorably separated veterans of the Air Force, Army, Coast Guard, Marines, or Navy
- Officer candidates: Cadets and midshipmen at U.S. service academies
- Spouses and children: Spouses, widows, widowers, un-remarried former spouses, and children or step-children of eligible members
Why Eligibility Is a Strict Requirement
These programs are custom to the military community—a core part of their mission and service model. The exclusivity enables focused products and support for frequent moves, deployments, and other unique needs.
Unpacking Commercial Auto Coverage and Costs
Whether you access business auto insurance through an agency program or directly with a carrier, the core protections are similar. For more general information, see Commercial Auto Insurance and When do I need commercial auto insurance?.
Typical Coverage Options Available
- Bodily Injury Liability: Medical and legal costs for injuries you cause to others
- Property Damage Liability: Damage your business vehicle causes to others property
- Medical Payments or PIP: Medical expenses for you and passengers, regardless of fault (where available)
- Collision: Repairs to your vehicle after a crash, regardless of fault
- Comprehensive: Non-collision losses such as theft, fire, vandalism, or weather
- Uninsured/Underinsured Motorist: If the at-fault driver lacks sufficient coverage
- Hired and Non-Owned Auto Liability: Liability when renting vehicles or when employees use personal cars for business
Estimating Costs: What to Expect When Shopping for Commercial Auto Insurance
Market quotes often start around $22 per month and can exceed $129+ depending on risk and coverage selections. Your premium will reflect factors unique to your operation.
Key pricing drivers:
- Industry and vehicle type/use
- Garaging/operating location
- Driver records and experience
- Liability limits and endorsements selected
- Deductibles and physical damage values
- Claims history and years in business
Understanding Commercial Auto Insurance Options for Your Business Fleet
Many military-connected business owners qualify for membership-based programs that place commercial auto policies through partner insurers. If you qualify, expect:
- Eligibility required: Limited to the military community and qualifying families
- Agency model: Policies issued and serviced by partner carriers
- Coverage types: Liability, collision, comprehensive, and more
- Typical costs: Commonly from about $22 to $129+ per month, based on risk
The biggest consideration is eligibility. If you qualify, these programs can be convenient; if not, an independent agency can shop the broader market on your behalf.
I’m Ryan McEachron, CEO of ISU Insurance Services ARMAC Agency in Victorville. With 25+ years serving Southern California businesses, my team compares multiple carriers to tailor the right coverage and price for your fleet.
Related resources:
- how does commercial auto insurance work
- what does commercial auto insurance cover
- when do i need commercial auto insurance
Does Your Business Qualify for Specialized Commercial Auto Insurance?
Some programs that serve the military community do not directly write commercial auto; they route members to experienced business carriers through an agency model.
How the Agency Model Works
You start with the agency, which then matches you to a partner carrier that structures your policy, sets terms, handles billing, and adjusts claims. Think of the agency as the conduit and the carrier as your ongoing policy administrator.
What This Means for Your Business
Your service experiencepolicy changes, certificates, and claimswill primarily run through the partner carrier. Ask which insurer will issue the policy and review their commercial claims track record before you bind.
The Crucial Factor: Eligibility Requirements for Specialized Insurance
Membership-based programs serving the military community enforce strict eligibility. If you do not meet the criteria, you will need to explore other market options.
For general startup guidance, the Small Business Administration offers a helpful guide for new businesses from the SBA.
Who Qualifies for Specialized Membership-Based Insurance?
- U.S. military members (active, retired, honorably separated)
- Cadets and midshipmen at U.S. service academies
- Spouses, widows, widowers, un-remarried former spouses, and children/step-children of eligible members
Why Eligibility Is a Strict Requirement
These programs are designed around the military lifestyle. The focus allows them to tailor products and service to frequent moves, deployments, and related needs—but also limits access to those who qualify.
Unpacking Commercial Auto Coverage and Costs
Whether you work through an agency-accessed program or shop directly, the building blocks of protection are similar. For more, see Commercial Auto Insurance and When do I need commercial auto insurance?.
Typical Coverage Options Available
- Bodily Injury Liability
- Property Damage Liability
- Medical Payments or PIP (where available)
- Collision
- Comprehensive
- Uninsured/Underinsured Motorist
- Hired and Non-Owned Auto Liability
Estimating Costs: What to Expect When Shopping for Commercial Auto Insurance
Based on market quotes we see, entry premiums can begin near $22 per month and scale past $129+ depending on vehicles, drivers, location, limits, and loss history. For a deeper dive, read How much does commercial auto insurance cost?.
Primary rating factors include:
- Industry and vehicle class/use
- Operating/garaging territory
- Driver MVRs and experience
- Liability limits, endorsements, and deductibles
- Claims history and years in business
Weighing the Pros and Cons of Agency-Accessed Commercial Auto Insurance
Some eligible members prefer agency-accessed business auto programs. Consider the full picture before you decide.

The Advantages
- Trusted access point for eligible members
- Potentially competitive pricing
- Streamlined quoting for existing members
- Familiarity with military life and logistics
The Limitations
- Strict eligibility excludes many businesses
- Service and claims handled by partner carriers, not the agencys main service team
- Limited to the agencys partner network
- Experiences can vary by partner carrier and claim
Frequently Asked Questions about Business Auto Policies
Here are answers to common questions business owners have about commercial auto insurance, particularly concerning policies accessed through an agency model.
What types of vehicles can be covered?
Commercial auto insurance is versatile and can cover nearly any vehicle used for business purposes, including:
- Cars, SUVs, and Vans: Used for sales calls, client visits, or deliveries.
- Pickup Trucks: Essential for contractors, landscapers, and other trades.
- Heavy-Duty Trucks: Including box trucks and tractor-trailers for transport and logistics.
- Specialized Vehicles: Such as food trucks, utility vans, and passenger vans.
If a vehicle is used primarily for work, it likely needs a commercial policy.
How does a commercial auto policy differ from a personal one?
There are critical differences between personal and commercial auto policies:
- Business Use: Personal auto policies typically exclude coverage for business-related activities. A commercial policy is designed specifically for these risks.
- Liability Limits: Commercial policies offer much higher liability limits to protect your business assets from costly lawsuits.
- Covered Vehicles & Drivers: Commercial insurance can cover a wider range of vehicles (like heavy trucks) and provides coverage for employees who drive company vehicles.
A personal policy is not sufficient for business use. A dedicated Commercial Vehicle Insurance policy is essential for protecting your company.
How are claims handled for a commercial auto policy accessed through an agency?
When your policy is through an agency model, you file claims directly with the partner insurance company that underwrites your policy, not with the agency itself. For example, if the agency connects you with another carrier, that carrier’s claims department will manage your case from start to finish. It’s important to know who your underwriting carrier is and have their contact information readily available.
Finding the Right Commercial Auto Coverage for Your Needs
If you qualify for a membership-based program serving the military community, agency-accessed business auto coverage can be a solid option. For everyone elseand even for eligible members comparing valueit pays to shop the broader market.
Focus on eligibility first, then compare coverages, limits, and service. A food truck, real estate car, and construction fleet each carry unique risks and need custom protection.
As an independent agency in Victorville serving Apple Valley, Hesperia, Oak Hills, and all of Southern California, ISU ARMAC shops multiple top-rated carriers to find the right fit at a competitive price. Find the best Business Auto Insurance for you.