
Why RLI Umbrella Insurance Could Be Your Financial Safety Net
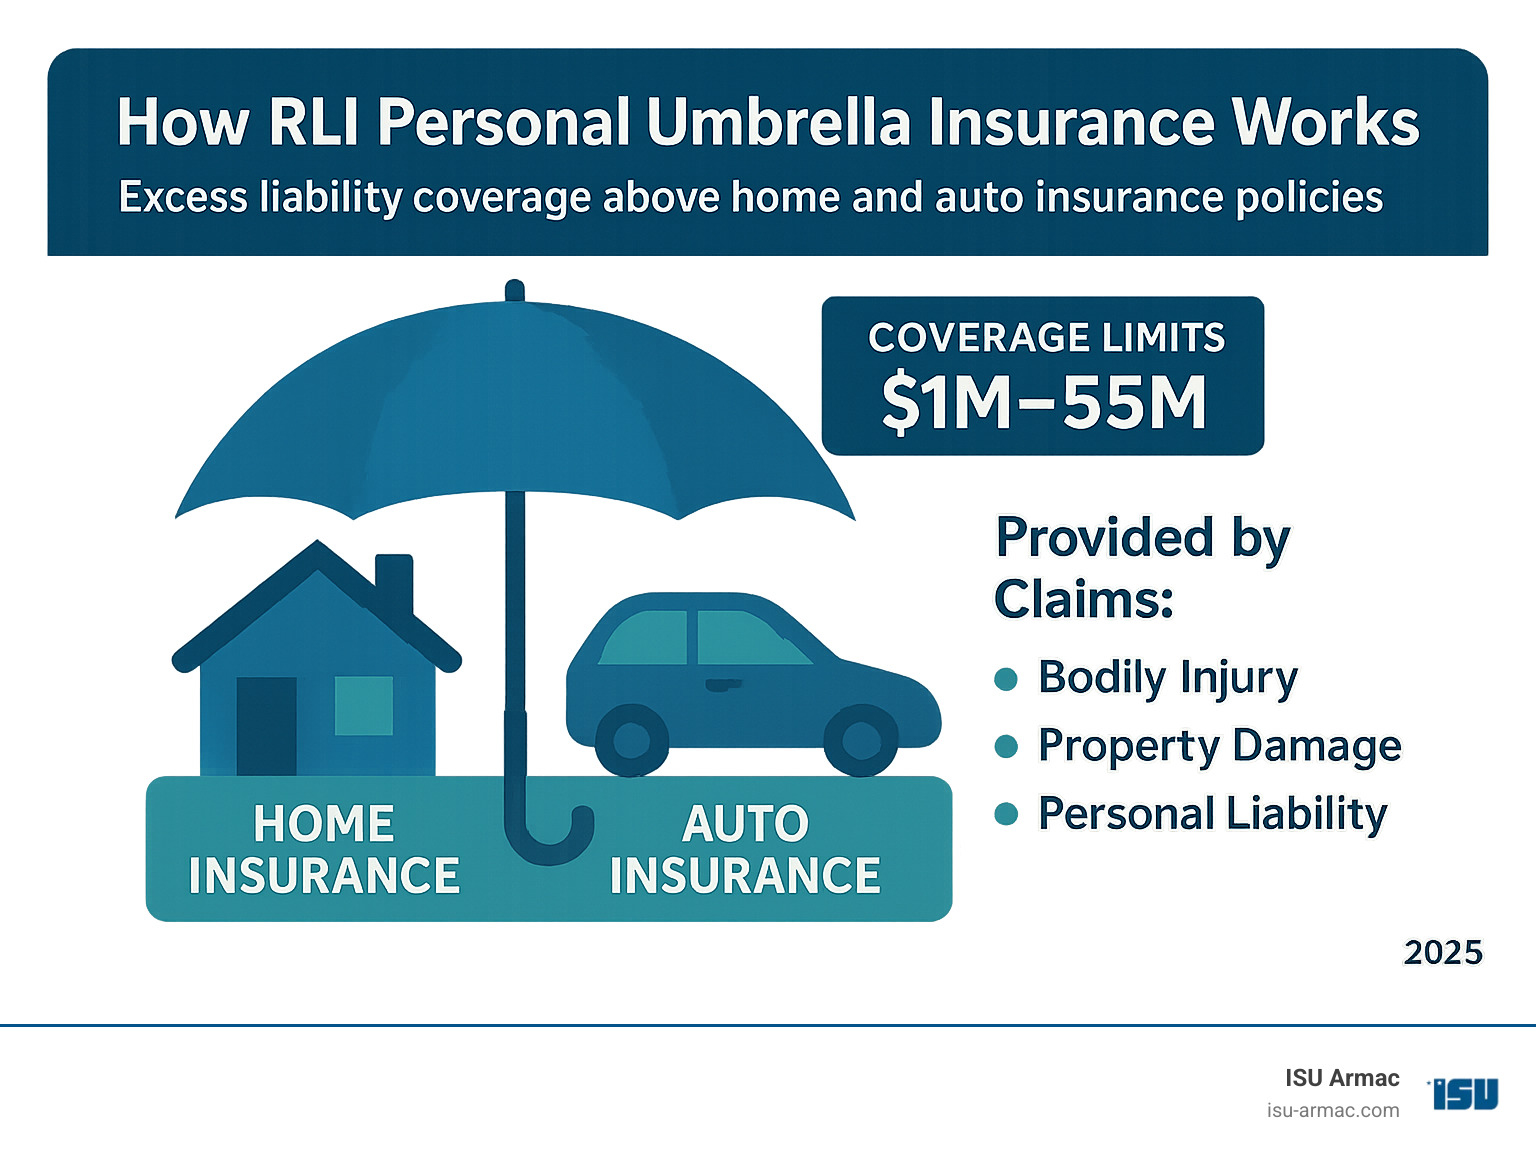
RLI umbrella insurance provides an extra layer of liability protection that sits above your existing home and auto insurance policies, offering coverage from $1 million to $5 million when your standard policies reach their limits.
Key Facts About RLI Umbrella Insurance:
- Coverage Limits: $1M to $5M in additional liability protection
- Stand-Alone Policy: Works with any underlying insurance carrier
- Broad Acceptance: Accepts new drivers, up to one DWI/DUI per household
- Financial Strength: A.M. Best A+ rating
- Availability: All 50 states plus D.C. (direct purchase not available in CA/FL)
- Flexible Requirements: Accepts auto limits as low as 100/300/50
Life throws curveballs when you least expect them. One moment you’re enjoying a backyard barbecue, and the next, a guest is seriously injured on your property. Without proper protection, a single lawsuit could wipe out your savings and threaten your future earnings.
This is where personal umbrella insurance becomes crucial. Think of it as a financial safety net that kicks in when your regular insurance policies max out. RLI Insurance Company has carved out a specialty niche in this market by offering stand-alone umbrella policies that work with any underlying insurance carrier.
What makes RLI different? They accept risks that other insurers often decline – like households with new drivers or even one DUI. Their flexible underwriting and competitive rates have made them a go-to choice for independent agents nationwide.
I’m Ryan McEachron, CEO of ISU Insurance Services ARMAC Agency, and I’ve been helping Victorville families steer RLI umbrella insurance options for years through my work in the insurance industry. My experience on the Victorville City Council and various community boards has shown me how unexpected liability situations can impact local families financially.
Rli umbrella insurance further reading:
What is RLI Personal Umbrella Insurance and Who Needs It?
Think of RLI umbrella insurance as your financial bodyguard. The RLI Personal Umbrella Policy (PUP) provides excess liability coverage that springs into action when your regular insurance policies hit their limits. When life throws you a curveball – like a serious car accident or someone getting hurt on your property – and the damages exceed what your standard home or auto insurance can handle, that’s when RLI steps up to protect your assets and future earnings.
But who really needs this kind of protection? The honest answer might surprise you – it’s not just for the wealthy. Homeowners face constant exposure to liability risks. Whether it’s a neighbor’s child getting injured on your trampoline or your dog having a bad day and biting someone, your homeowner’s policy might not cover the full cost of a lawsuit.
Car owners especially need to consider umbrella coverage, particularly if you have teenage drivers in the house or spend a lot of time on the road. One serious accident can result in damages that far exceed your auto policy limits. Boat owners face similar risks, often with even lower liability limits on their watercraft policies.
Here’s what many people don’t realize: even if you don’t have significant assets today, RLI umbrella insurance protects your future income too. A large judgment against you could mean decades of garnished wages. That’s a financial burden no family should have to carry.
What makes RLI truly special is their stand-alone policy approach. Unlike other insurers that might require you to move all your coverage to them, RLI offers remarkable flexibility. You can keep your current auto and home insurance exactly where it is, and RLI’s umbrella policy will simply layer on top, providing that crucial extra protection.
This flexibility is huge for families who have found great rates or service with their current providers. You don’t have to disrupt relationships that are working well just to get umbrella coverage.
RLI backs up their promises with serious financial strength. Their A+ rating from A.M. Best shows they have the resources to pay claims when they matter most. They’ve also earned recognition in Ward’s 50, which honors top-performing insurance companies. This financial stability means you can trust they’ll be there when you need them.
The bottom line? If you have assets to protect or income to preserve, Why Is Umbrella Insurance Worth Getting? becomes a question worth exploring seriously.
A Deep Dive into Coverage and Limits
When we talk about RLI umbrella insurance, we’re not just discussing an extra policy; we’re talking about comprehensive protection that truly extends far beyond what your regular insurance offers. This coverage is designed to step in during those unexpected, high-cost incidents that could otherwise turn your financial world upside down.

So, what exactly does RLI umbrella insurance cover? It steps up for a wide range of situations where you might be held responsible for someone else’s harm. This includes bodily injury liability, which covers things like medical bills, lost wages, and even pain and suffering if you’re found responsible for someone’s injuries. Imagine a guest slipping on your icy walkway, or if you’re involved in a car accident and someone gets hurt.
It also covers property damage liability. This is for situations where you accidentally damage someone else’s property. Maybe you back into your neighbor’s fancy new fence, or perhaps you cause significant damage to a building in an accident. Beyond physical harm, RLI umbrella insurance also covers personal injury. This is a broader term that includes non-physical harms like libel (written untrue statements that harm someone’s reputation), slander (spoken untrue statements), false arrest, or even an invasion of privacy. These types of claims are becoming more and more common. A big bonus? Your policy generally offers worldwide coverage, which is fantastic news if you love to travel and want peace of mind no matter where you are.
Perhaps one of the most reassuring parts of RLI umbrella insurance is its coverage for defense costs and legal representation. If someone sues you, even if the lawsuit seems silly, the legal bills can quickly pile up. Your RLI policy typically covers these costs. This means RLI will provide expert legal help, which can save you a fortune and a lot of stress.
The amount of extra protection you get with RLI Personal Umbrella insurance is substantial, typically ranging from $1 million to $5 million. This means once your regular home or auto insurance policy limits are used up, RLI steps in with that huge financial safety net.
Here’s another great feature: RLI umbrella insurance often offers excess Uninsured/Underinsured Motorist (UM/UIM) coverage. In many states, this comes with a generous $1 million limit, and sometimes even more! Why is this so important? It protects you and your family. If you’re injured by a driver who doesn’t have insurance, or not enough insurance to cover your medical bills and lost wages, RLI steps in to help. It’s a proactive way to protect your own well-being, not just against claims others make against you. You can learn More on RLI’s UM/UIM coverage right on their website.
Let’s look at a real-life example to see how this all works. Imagine you’re replacing a dock at your vacation home, and a good friend offers to help with some tree trimming nearby. While working, a heavy tree limb unexpectedly falls and severely injures your friend. Suddenly, your friend’s medical bills, lost wages, and pain and suffering add up to a staggering $1 million. Your homeowner’s insurance, while good, has a liability limit of $200,000. Once that $200,000 is paid out, you’re still on the hook for $800,000. Without RLI umbrella insurance, that $800,000 would come directly from your pocket, forcing you to potentially sell assets or drain your life savings. With RLI, their umbrella policy would kick in, covering that remaining $800,000, protecting your financial future from ruin. It’s truly amazing how a relatively small annual payment can save you from such a huge financial disaster.
To get a broader picture of what liability insurance covers in general, you might find this helpful: What Does Liability Insurance Actually Cover?.
The Standout Features of an rli umbrella insurance Policy
When we help our clients explore their options for liability protection, RLI umbrella insurance consistently stands out due to its flexible underwriting and broad acceptance criteria. This means they are often able to provide coverage even in situations where other carriers might hesitate or decline.

Key to RLI’s appeal is its stand-alone nature, as we’ve discussed. This independence from your underlying carriers simplifies your insurance landscape. Furthermore, RLI prides itself on having no policy fees beyond the quoted premium, which means the price you see is the price you pay, without hidden administrative charges.
What makes rli umbrella insurance a flexible choice for drivers?
RLI truly shines when it comes to accommodating diverse driving profiles within a household. We understand that life isn’t always perfectly clean-cut, and RLI’s policies reflect a pragmatic approach to risk.
- New drivers accepted: We often hear concerns from parents about insuring their newly licensed teenagers. RLI accepts new drivers with no age limits – a significant relief for families navigating this exciting, yet sometimes daunting, phase.
- One DWI/DUI per household allowed: This is a truly unique insight from our research. While responsible driving is paramount, RLI acknowledges that past mistakes happen. They allow up to one DWI/DUI per household, offering a second chance at comprehensive liability protection that many other insurers would simply deny.
- Flexible underlying auto limits: RLI is not overly rigid about the underlying auto liability limits you must carry. They accept underlying auto limits as low as 100/300/50 for most households. This flexibility means you might not need to drastically increase your primary auto policy just to qualify for an umbrella.
- Share-the-expense carpooling: In today’s world of rideshares and carpooling, it’s good to know that RLI extends coverage for share-the-expense carpooling. This means if you’re regularly driving colleagues or friends and splitting gas costs, your RLI umbrella insurance still has your back (though it excludes commercial risks like Uber-type services).
How does rli umbrella insurance handle unique property and risks?
Beyond drivers, RLI also offers remarkable flexibility for various property types and common household risks that often cause headaches with other insurers.
- No specific exclusions for trampolines or swimming pools: Many insurance carriers will either exclude coverage or charge extra for these common backyard features, viewing them as high-risk. RLI does not exclude coverage for injury relating to trampolines or swimming pools, offering broader protection without additional hassle.
- Coverage for trusts or LLCs: If your property is held in a trust or an LLC, RLI extends coverage to these entities, provided your basic underlying policy also covers them and lists them as an additional or second named insured. This is crucial for asset protection strategies.
- Properties under construction: Undertaking a major renovation or building a new home? RLI accepts properties under construction, as long as the required underlying limits are in place. This is a valuable feature for those navigating the complexities of home building.
- Large acreage farms: For our clients in more rural parts of Southern California, RLI accommodates agricultural properties. They accept farms and land up to 640 acres with no additional acreage charge or cap, and even up to 1280 acres with a charge and a $1M cap. This flexibility is a huge benefit for landowners.
We also find that RLI doesn’t exclude coverage for loss resulting from earth movement, which can be a concern in certain geographical areas, and they do not have a controlled substances exclusion, offering a broader scope of protection. For more on land coverage, check out: Does an Umbrella Policy Cover Vacant Land?.
Eligibility, Limitations, and Getting Your Policy
While RLI umbrella insurance has built its reputation on broad acceptance, there are still some important eligibility requirements and limitations to understand. Think of it as RLI’s way of keeping things fair for everyone while managing their risk responsibly.

The good news about state availability is that RLI Personal Umbrella coverage reaches virtually everywhere – all 50 states plus Washington D.C. Whether you’re living in busy Los Angeles or quiet rural Montana, RLI can likely protect you. However, there’s a small catch for our California neighbors (and those in Florida): you can’t buy the policy directly online. Instead, you’ll need to work with an appointed agent like us here at ISU Armac.
Honestly, this limitation turns out to be a blessing in disguise. Getting personalized guidance through the process means you’ll end up with coverage that actually fits your unique situation, rather than a one-size-fits-all approach.
Now, let’s talk about the situations where RLI draws the line. They maintain their competitive rates by being selective about certain risks. Underwriting declines happen in specific circumstances: if you’ve had a liability loss over $50,000 in the past 5 years, or if you currently have any open liability claims. These aren’t arbitrary rules – they help RLI keep premiums affordable for everyone else.
There’s also something called age-related caps that applies in very specific situations. If a driver in your household is 80 or older, or under 22, RLI will cap their coverage at $1 million – but only if they have a driving incident on their record. Clean driving record? No cap applied. This shows how RLI looks at individual circumstances rather than making blanket assumptions based on age alone.
So how do you actually get your hands on an RLI umbrella insurance policy? RLI offers an online quoter that can give you immediate acceptance notification, which is pretty impressive technology. But here’s where working with our team at ISU Armac really pays off. We can shop multiple carriers, including RLI, to make sure you’re getting the absolute best coverage at the lowest rate.
Our clients in Victorville, Apple Valley, Hesperia, and Oak Hills appreciate having someone who understands the local insurance landscape and can walk them through their options. We handle the paperwork, answer your questions, and make sure everything fits together perfectly with your existing coverage.
If you want to explore on your own first, you can Get a direct quote from RLI through their online portal. Just remember those direct purchase limitations we mentioned for California and Florida residents.
Managing Your Policy and Filing a Claim
Once you become an RLI umbrella insurance policyholder, you’ll find that managing your coverage is refreshingly straightforward. RLI has invested in creating a user-friendly digital experience that puts control right at your fingertips.
The heart of your policy management is RLI’s dedicated policyholder portal. This online hub becomes your go-to resource for everything related to your umbrella policy. Through this convenient platform, you can handle online payments without the hassle of writing checks or making phone calls. Whether you prefer to pay monthly, quarterly, or annually, the portal makes it simple to stay current with your premiums.
Beyond payments, the portal serves as your policy management center. Need to update your address after a move? Want to review your coverage details before your renewal? All of this can be handled online at your convenience. The portal also provides document access, storing all your important policy documents digitally. This means you can review your coverage terms, print your declarations page, or access your policy documents anytime – whether you’re at home planning your finances or traveling and need proof of coverage.
You can access all these features through RLI’s Policyholder Log in / Payments portal.
Of course, we hope you’ll never need to use it, but if an incident occurs that requires filing a claim, RLI has streamlined this process as well. Their online claim reporting process is designed to get your claim started quickly and efficiently. When the unexpected happens – whether it’s a serious accident or someone is injured on your property – time is often critical.
To file a claim, you’ll need some required information ready. This includes your policy number (easily found in your policyholder portal), along with a clear incident description that explains what happened, when, and where. The more detail you can provide upfront, the smoother the claims process will be.
RLI processes claims directly, which means you’re working with the same company that issued your policy. This consistency often leads to better communication and faster resolution. You can start your claim immediately by visiting: Click here to begin your claim.
Should your circumstances change and you need to explore a cancellation process, RLI does require the insured’s signature on any cancellation request. This protects you from unauthorized changes to your policy. If you cancel mid-term and are entitled to a premium refund, RLI applies a short rate factor of 10%, which is standard industry practice.
Before making any decision about cancellation, we always recommend discussing your situation with us first. Sometimes what seems like a reason to cancel can actually be addressed through a policy adjustment or by exploring other options that maintain your valuable liability protection.
Frequently Asked Questions
Over the years, we’ve helped countless families in Victorville, Apple Valley, and Hesperia steer their RLI umbrella insurance options. These are the questions that come up most often during our conversations, and I want to address them clearly so you can make an informed decision.
Does RLI require me to switch my home or auto insurance?
Absolutely not! This is honestly one of my favorite things about RLI umbrella insurance – it’s a true stand-alone policy that plays well with others. You can keep your current home and auto insurance carriers exactly where they are. Maybe you love your auto insurance company’s customer service, or your homeowner’s policy has been with the same carrier for decades. No problem at all.
The beauty of RLI’s approach is that their umbrella simply sits above whatever underlying coverage you already have. Think of it like adding a protective roof over your existing insurance house. As long as you maintain the required underlying limits that RLI specifies, you’re free to shop around, stay loyal to current carriers, or make changes whenever it makes sense for your situation.
What are the underlying insurance limits RLI requires?
Here’s where RLI really shines with their flexibility. While some umbrella carriers demand sky-high primary limits that can be expensive, RLI umbrella insurance accepts auto limits as low as 100/300/50 for most households. That translates to $100,000 for bodily injury per person, $300,000 for bodily injury per accident, and $50,000 for property damage.
This reasonable approach makes umbrella coverage accessible to more families. You won’t need to dramatically increase your primary auto policy just to qualify, which keeps your overall insurance costs more manageable. For home and rental properties, specific limits will apply based on your situation, but RLI’s general philosophy is accommodation rather than rigid requirements.
When we review your current policies together, we’ll make sure everything aligns properly so there are no gaps in your coverage.
How does RLI handle newly acquired property like a car or second home?
This is where RLI makes life really convenient for busy families. When you buy a new car, purchase a second home, add a rental property, or even get a motorhome, your RLI umbrella insurance automatically covers these new assets. You don’t need to call RLI immediately or worry about coverage gaps during that hectic time when you’re dealing with new purchases.
The only thing you need to do is report these new acquisitions at your next policy renewal – not immediately, but when your policy comes up for renewal. It’s like a “set it and forget it” approach that removes administrative headaches from your life.
The one important requirement is maintaining proper underlying insurance on these newly acquired assets. So while RLI automatically extends umbrella coverage, you still need to get that new car insured or add that second home to your homeowner’s policy. But that automatic umbrella coverage gives you peace of mind that you’re protected while you handle all the other details.
The Verdict: Is RLI Umbrella Insurance Right for You?
We’ve journeyed through the ins and outs of RLI umbrella insurance, and now it’s time for the big reveal: Is it the right fit for you? After unwrapping all its unique features, we firmly believe RLI stands out as a truly compelling choice for comprehensive personal liability protection.
What makes RLI umbrella insurance shine so brightly? For starters, its incredible flexibility is a game-changer. You don’t have to break up with your current home and auto insurers, as RLI’s stand-alone policy plays nicely with everyone. It simply adds that crucial extra layer of protection on top.
Then there’s RLI’s surprisingly broad acceptance criteria. They’re often there for you when other insurers say no. This is a huge benefit if you have new drivers in the family, or even if there’s been a past driving hiccup like one DWI/DUI in the household. RLI also covers common backyard features like trampolines and swimming pools without specific exclusions, offering peace of mind where others might cause headaches. Plus, with their A+ financial rating from A.M. Best, you can truly rest easy knowing they’re a rock-solid partner.
Beyond just broad acceptance, RLI umbrella insurance offers truly comprehensive coverage. This isn’t just about bodily injury or property damage. It extends to personal injury claims like libel or slander, worldwide coverage, and even crucial excess Uninsured/Underinsured Motorist (UM/UIM) protection. And, let’s be honest, the ease of management with their online portal for payments and claims just makes life a little simpler.
So, who exactly should roll out the red carpet for RLI umbrella insurance? If you’re someone who values a stand-alone policy that fits seamlessly into your existing insurance puzzle, then this might be your perfect match. It’s especially custom for those with unique risk factors, like households welcoming new drivers, or even those with a single DUI on their record.
But beyond unique situations, if you’ve worked hard to build up significant assets, have a high net worth, or simply want to safeguard your future earnings from the financial devastation of a major lawsuit, an RLI umbrella insurance policy is like having a superhero cape for your finances. It’s a wise investment in your peace of mind.
Here at ISU Armac, serving our wonderful communities like Victorville, Apple Valley, Hesperia, Oak Hills, and the wider Southern California region, we’ve seen how an unexpected incident can impact families. That’s why we confidently say RLI umbrella insurance is a strong contender for your personal liability protection needs. It’s truly an affordable, common-sense way to secure your financial future, come what may.
Don’t wait for life’s unexpected downpours to realize you needed a bigger umbrella. Let’s talk about protecting what matters most to you. Explore your Personal Lines Insurance options with us today, and let us help you find the peace of mind you deserve.