
Why Renters in Earthquake Zones Need Specialized Coverage
Renters insurance with earthquake coverage protects your personal belongings and living expenses when a quake strikes—but most standard renters policies won’t help you at all.
Quick Answer: What You Need to Know
- Standard renters insurance excludes earthquakes. Your policy likely has an “earth movement” exclusion.
- You need a separate policy or add-on. Earthquake coverage isn’t automatic—you must purchase it.
- It’s surprisingly affordable. California renters can get coverage for as little as $35/year or $3-5/month.
- Your landlord’s policy won’t cover your stuff. They insure the building, not your belongings.
- Three main protections: Personal property replacement, temporary housing costs, and emergency repairs.
Living in Southern California means living with seismic risk. The High Desert, including Victorville, is near the San Andreas Fault, putting your personal property at risk during a quake. The problem is that your standard renters insurance almost certainly won’t pay for earthquake damage due to an “earth movement” exclusion, leaving you to cover the replacement costs.
The good news is that specialized earthquake coverage for renters is surprisingly affordable. Since you’re only insuring your belongings, not the building, policies can be very budget-friendly.
I’m Ryan McEachron, CEO of ISU Insurance Services ARMAC Agency and a lifelong High Desert resident. I’ve helped many local renters secure renters insurance with earthquake coverage to protect their finances. Let me walk you through what you need to know.
The Big Shake-Up: Why Your Standard Renters Policy Isn’t Enough
You bought renters insurance to protect your belongings from fire and theft, but what about earthquakes? Your standard policy almost certainly excludes damage from a quake.

Buried in the fine print is an “earth movement” exclusion, which means the insurer won’t cover damage from earthquakes, landslides, or sinkholes. If a quake causes your TV to fall or furniture to break, your standard policy won’t pay to replace them.
While your policy might cover secondary damage, like a fire that starts because of an earthquake, it won’t cover direct damage from the shaking itself. This is a critical gap that earthquake insurance is designed to fill. You need renters insurance with earthquake coverage to bridge this gap.
Understanding Your Landlord’s Policy
A common misconception is that your landlord’s insurance covers you. It doesn’t. Your landlord’s policy protects the building structure—walls, roof, and foundation. It is designed to protect their investment, not your personal belongings.
Your couch, laptop, and other personal items are your responsibility to insure. While your landlord must make the building habitable after a disaster, they have no obligation to replace your property.
The Critical Gap in Standard Renters Insurance
To be clear, your standard policy leaves a major gap. It will not cover:
- Direct shaking damage: Broken belongings from the ground moving.
- Loss of use: Hotel or temporary housing costs if the quake makes your rental uninhabitable.
This gap represents a serious financial risk for renters in Southern California. At ISU Armac, we ensure our clients understand Does Renters Insurance Cover Earthquakes? before they assume they’re protected. Adding renters insurance with earthquake coverage is the straightforward solution. We can help you understand how Renters Insurance in Victorville, CA works with this protection.
Decoding Your Policy: What Renters Insurance with Earthquake Coverage Includes
When you buy renters insurance with earthquake coverage, you’re protecting your personal belongings and your ability to maintain your lifestyle after a quake. It’s a financial safety net that prevents you from draining your savings to replace everything you own or pay for temporary housing while your rental is repaired.
For a comprehensive breakdown of these protections, the CEA Renters Policy Coverages & Deductibles page offers excellent detail.
Key Protections in Renters Insurance with Earthquake Coverage
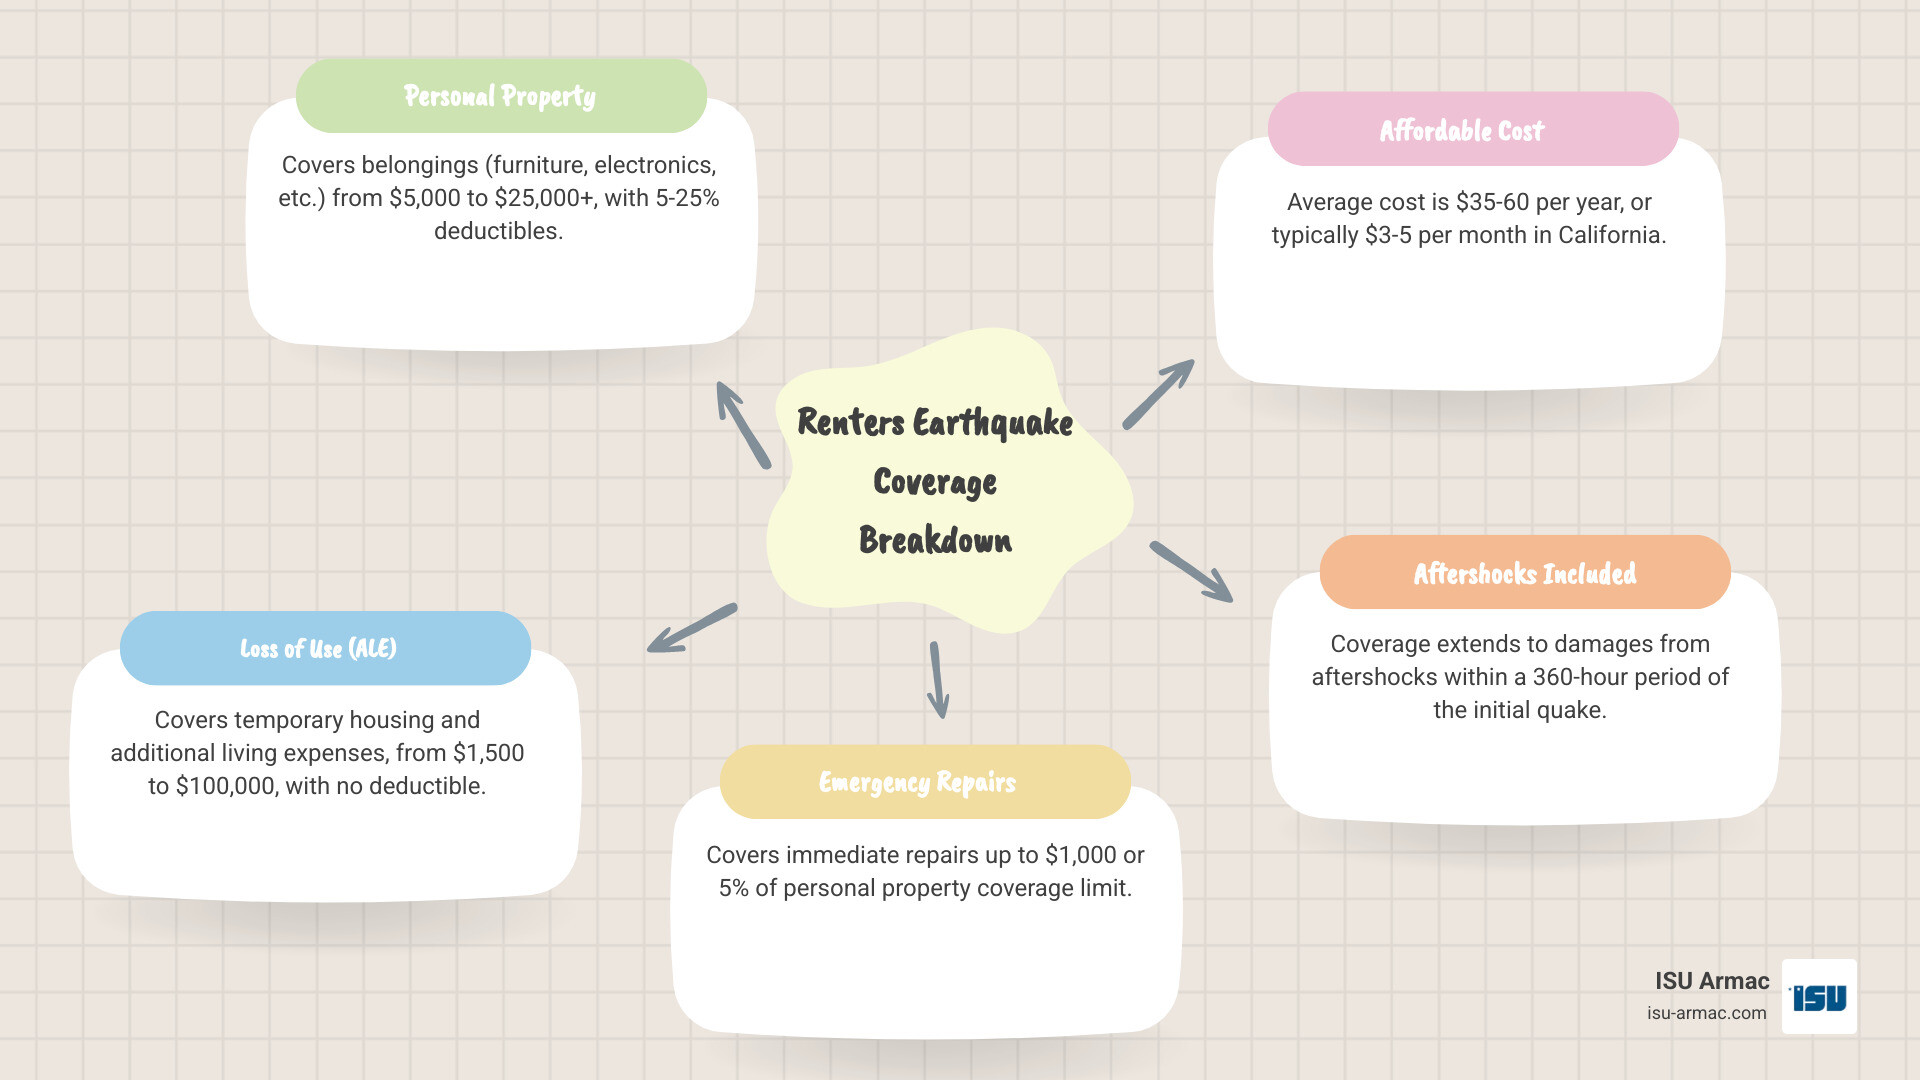
The core of an earthquake policy is Personal Property coverage, which pays to repair or replace belongings damaged in a quake, such as furniture, electronics, and clothing. Limits typically start at $5,000 and can go up to $25,000 or more. For fragile items like glassware, you can add a Breakables coverage option. This policy does not cover the building structure, your vehicle, or flood damage.
Loss of Use coverage, or Additional Living Expenses (ALE), is crucial if a quake forces you from your home. It pays for hotel stays, temporary rent, and increased food costs. Limits range from $1,500 to $100,000, and this coverage has no deductible.
Emergency Repairs coverage provides funds for immediate fixes to prevent further damage, like boarding up a broken window. Policies usually offer $1,000 or 5% of your Personal Property limit.
Your policy also covers damage from aftershocks within 360 hours (15 days) of the initial quake, treating them as a single event with one deductible. Finally, debris removal coverage helps with the cost of cleaning up damaged belongings.
Understanding Deductibles and Loss of Use
Earthquake deductibles are a percentage of your coverage limit (typically 5% to 25%), not a flat dollar amount. For example, with $25,000 in Personal Property coverage and a 5% deductible, your deductible is $1,250. If you have $20,000 in damage, the insurer subtracts the $1,250 deductible from your covered damages and pays you $18,750.
Crucially, you don’t pay this deductible out-of-pocket; it’s simply deducted from your claim payment.
As mentioned, Loss of Use coverage has no deductible. If your rental becomes uninhabitable, you can access these funds for temporary housing immediately. Understanding loss-of-use coverage highlights its value in a crisis.
Weighing the Risk: Is Earthquake Insurance Worth the Cost?
Is renters insurance with earthquake coverage worth the cost? When you see the numbers, the answer is clear. Earthquake coverage for renters is incredibly affordable, with basic California Earthquake Authority policies starting around $35 per year. That’s less than $5 a month for most renters.
Compare that small cost to the alternative: replacing all your belongings out-of-pocket. Could you afford to replace your TV, laptop, furniture, and clothing all at once? For most, that’s a $10,000+ expense, not including hotel stays if your apartment is damaged. The financial strain of an uninsured loss can take years to recover from.
Cost Factors for Renters Insurance with Earthquake Coverage
Your specific premium depends on several factors. Geographic location is the most important; living near active fault zones in Victorville, Hesperia, and Apple Valley means higher risk. You can check your risk level at FEMA.gov. The building’s age and construction, your chosen coverage limits, and your selected deductible percentage also affect your premium. A higher deductible will lower your monthly cost.
The California Earthquake Authority offers a premium calculator on CEA’s website where you can get an accurate quote. We also break down local pricing in our guide on How Much Does Earthquake Insurance Cost in California?.
[TABLE] Comparing Post-Quake Financial Aid
| Feature | Earthquake Insurance | Federal Assistance (FEMA/SBA) |
|---|---|---|
| Purpose | Restore financial wholeness | Provide immediate, essential needs |
| Payout | Covers replacement cost up to policy limits | Small grants, low-interest loans |
| Repayment | None (it’s a policy benefit) | Loans must be repaid with interest |
| Availability | Guaranteed for policyholders | Must be in a declared disaster area |
Many people mistakenly believe federal disaster assistance will cover their losses. In reality, FEMA aid is for immediate survival needs, and the grants are small. Most federal help comes as low-interest SBA loans that must be repaid. Taking on debt after losing your belongings is not a path to recovery.
In contrast, renters insurance with earthquake coverage is designed to make you financially whole. It pays to replace your property and cover living expenses up to your policy limits, with no repayment required. It’s a guaranteed benefit for policyholders, unlike federal aid, which requires a disaster declaration.
How to Get Covered: A Renter’s Guide to Finding a Policy
Getting renters insurance with earthquake coverage is straightforward. At ISU Armac, we can guide you through the process. You can typically add it as an endorsement to your existing renters policy, which is often the simplest and most cost-effective route.
The California Earthquake Authority (CEA)
In California, most renter’s earthquake insurance is provided through the California Earthquake Authority (CEA), a publicly managed, not-for-profit organization. Its rates are based on science, not profit, which helps keep premiums low (starting around $35/year). The CEA partners with residential insurers, so you can purchase a policy through your existing insurance provider. This makes the process seamless.
At ISU Armac, we work with CEA participating carriers to add this protection for you. CEA policies are flexible, allowing you to customize coverage limits and deductibles to fit your budget and needs. For more details, see our guides on California Earthquake Authority Insurance and What Does California Earthquake Insurance Cover?.
Steps to Secure Your Policy
Ready to get protected? Here’s how to get started:
- Review your current renters policy. We can help you identify the “earth movement” exclusion and understand your coverage gaps.
- Assess the value of your personal property. Create an inventory of your belongings—furniture, electronics, clothing—to determine how much coverage you need. Most renters own $20,000 to $30,000 worth of property.
- Contact your insurance agent—that’s us at ISU Armac. As local experts, we understand the seismic risks in the High Desert and can explain your options in plain English.
- Discuss coverage and deductible options. We’ll help you select the right limits for personal property and loss of use, and choose a deductible (5% to 25%) that balances your premium cost with your financial comfort level.
- Purchase the policy. We’ll facilitate adding the coverage, usually as an endorsement to your existing policy. The process is quick and simple. You can estimate costs beforehand using the premium calculator on CEA’s website.
Frequently Asked Questions about Renters Earthquake Insurance
Here are answers to the most common questions we hear about renters insurance with earthquake coverage.
Can I buy earthquake insurance right after an earthquake?
Yes, the California Earthquake Authority (CEA) continues to sell policies even after a quake. However, a new policy purchased right after an earthquake typically won’t cover damage from aftershocks for a set period (usually 15-60 days). This is why it’s crucial to get coverage before a disaster strikes to ensure you’re protected from the event and its immediate aftershocks.
How is the deductible paid on a claim?
You do not pay the deductible out-of-pocket. The insurance company subtracts the deductible amount from your total claim payment before sending you the funds. For example, with $20,000 in damages and a $1,250 deductible, you would receive a payment of $18,750.
What is ‘Loss of Use’ coverage and how does it work?
Loss of Use, or Additional Living Expenses (ALE), covers costs if an earthquake makes your rental uninhabitable. It pays for hotel bills, temporary rent, increased food costs, and moving/storage fees. A key benefit is that this coverage has no deductible, so you can access funds for temporary housing immediately.
Conclusion
Living in Southern California means accepting earthquake risk, but you don’t have to accept the financial fallout. Your standard renters policy won’t cover quake damage due to the “earth movement” exclusion, leaving you responsible for replacing everything and covering temporary housing. This could be a devastating financial blow.
The solution, renters insurance with earthquake coverage, is surprisingly affordable—often just a few dollars a month. For as little as $35 a year, you can protect your belongings and ensure you have a place to live if your rental is damaged. Unlike federal aid, which often comes as repayable loans, insurance provides funds to make you whole again without adding debt.
At ISU Armac, we are lifelong High Desert residents dedicated to protecting our community. We’ve helped countless renters in Victorville, Apple Valley, and Hesperia find affordable coverage. The time to get protected is now, before the ground shakes.
Take the next step to secure your belongings and financial stability by exploring your Earthquake Insurance California options today. Give us a call or stop by our office in Victorville. We’ll help you find the right coverage at the best rate, giving you the peace of mind you deserve.