
Why Independent Contractors Can’t Afford to Skip Professional Liability Protection
Errors and omissions insurance for independent contractors provides essential protection against client claims of professional negligence, mistakes, or failure to deliver promised services. This specialized coverage helps pay for legal defense costs, settlements, and judgments when clients allege your work caused them financial harm.
Key Benefits of E&O Insurance for Independent Contractors:
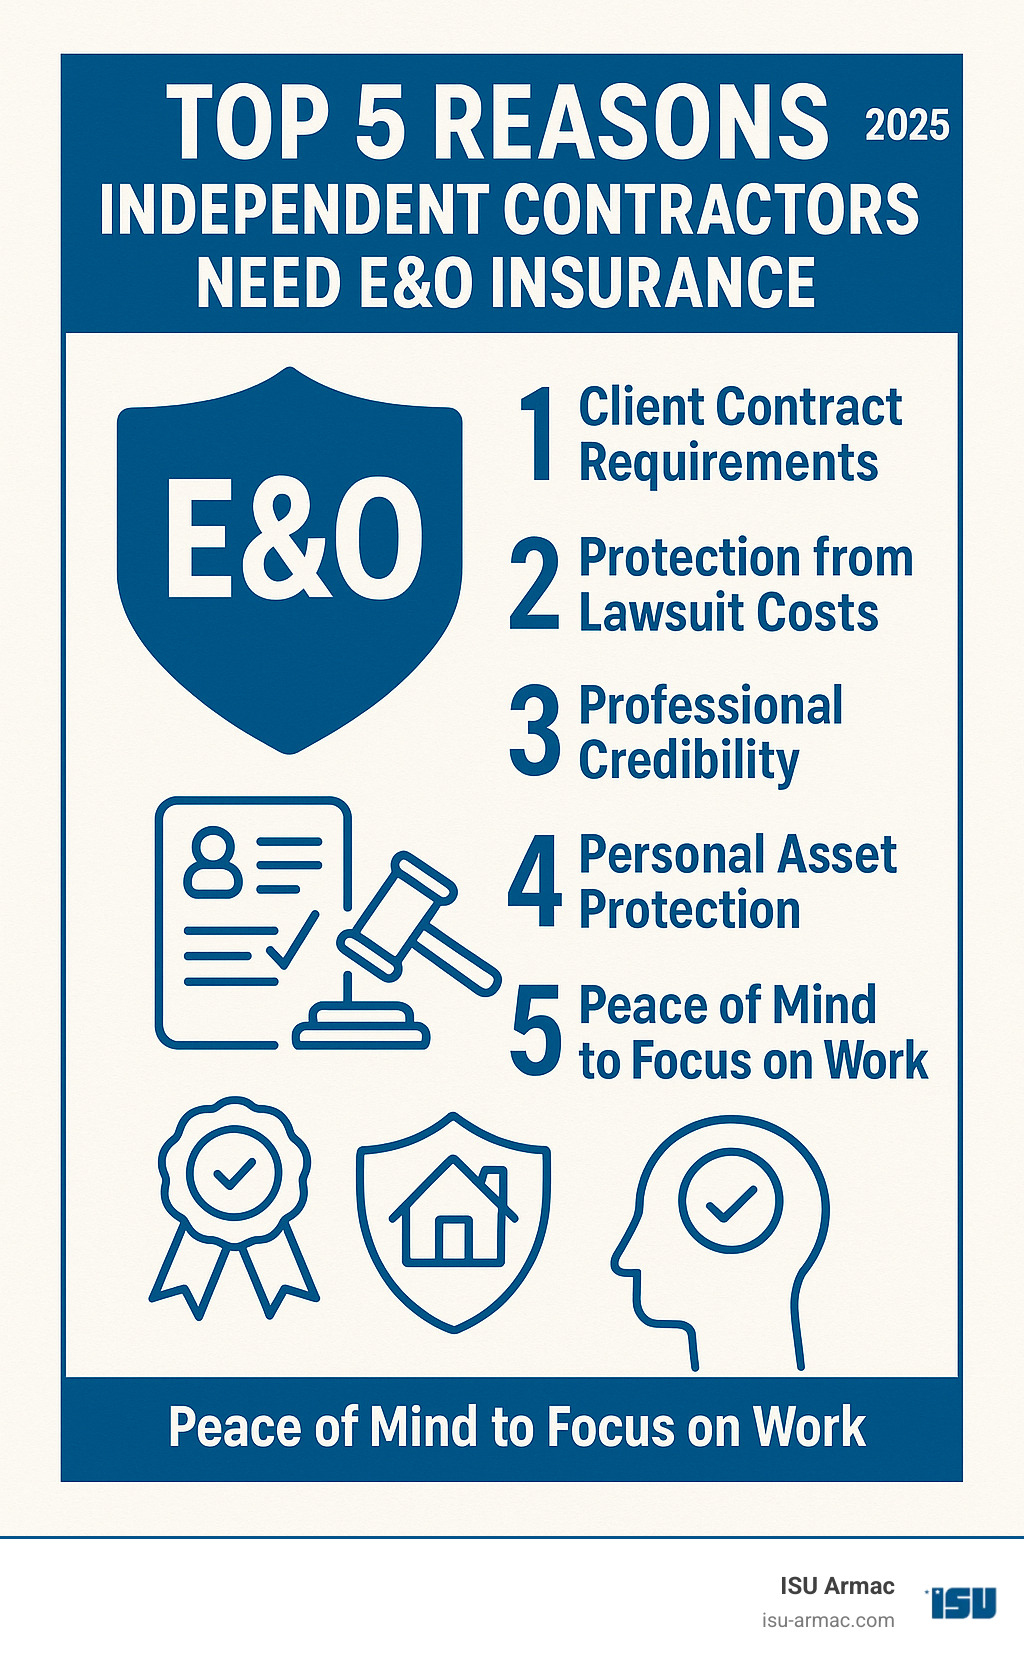
- Legal Protection: Covers defense costs even for baseless claims (average legal fees can exceed $50,000)
- Client Requirements: Many contracts require proof of E&O coverage before work begins
- Professional Credibility: Demonstrates accountability and builds client trust
- Financial Security: Protects personal assets from costly lawsuits
- Average Cost: $500-$1,000 annually for most independent contractors
Consider this real scenario from the research: An IT consultant recommended software that later caused a client to lose valuable data due to a faulty backup feature. Without E&O insurance, the consultant would face potentially devastating legal costs and damage claims entirely out-of-pocket.
The stakes are particularly high for independent contractors because you’re personally liable for your professional mistakes. Unlike employees who may have some protection under their employer’s policies, independent contractors stand alone when facing client claims.
I’m Ryan McEachron, CEO of ISU Insurance Services ARMAC Agency in Victorville, with over 25 years of experience helping Southern California professionals secure appropriate errors and omissions insurance for independent contractors. My background in both business leadership and community service has given me deep insight into the unique risks independent professionals face in our region.
Handy errors and omissions insurance for independent contractors terms:
- errors and omissions insurance
- errors and omissions insurance cost
- errors and omissions insurance coverage
Decoding Errors and Omissions (E&O) Insurance: Your Professional Safety Net
Think of Errors and Omissions (E&O) insurance as your professional bodyguard. Also known as professional liability insurance, it stands between you and the financial devastation that can come from client claims alleging your work caused them harm.
Here’s what makes E&O insurance so valuable: it protects you whether the mistake was real or imagined. Even completely baseless accusations can trigger expensive legal battles. Your E&O policy steps in to handle defense costs, settlements, and judgments up to your policy limits, minus your deductible.
The beauty of having this coverage goes beyond just financial protection. When you’re not constantly worried about potential lawsuits lurking around every project corner, you can focus on what you do best—delivering excellent work to your clients.
Your clients notice this confidence too. Many require proof of E&O coverage before they’ll even consider hiring you, as explained in What is Errors and Omissions Liability Insurance?. It’s become a standard business requirement, like having a professional email address or business cards.

What Specific Risks Does E&O Insurance Cover?
Errors and omissions insurance for independent contractors covers a wide range of professional mishaps that result in financial loss for your client. Common claims include:
- Work Mistakes: An architect’s design flaw leads to costly construction problems.
- Omissions: A real estate agent forgets to disclose a known property issue, leading to a lawsuit.
- Breach of Contract: A client claims you didn’t deliver what was promised or the quality was subpar.
- Copyright Infringement: A marketing consultant unknowingly uses protected imagery in a campaign.
- Libel and Slander: A client alleges your professional communications damaged their reputation.
In all these cases, E&O insurance protects you when your professional work allegedly costs a client money.
Learn more about Errors and Omissions Insurance Coverage to understand the full scope of protection available.
What E&O Insurance Typically Doesn’t Cover
While E&O insurance is comprehensive, it’s not a catch-all policy. Understanding its limitations is key. It generally does not cover:
- Intentional Wrongdoing & Criminal Acts: E&O protects against honest mistakes, not deliberate fraud or illegal activities.
- Bodily Injury & Property Damage: These are typically covered by General Liability Insurance. For example, if a client trips over your equipment, that’s a GL claim.
- Employee Claims: Issues like wrongful termination are covered by Employment Practices Liability Insurance (EPLI), not E&O.
- Cyber Liability: Most standard E&O policies exclude data breaches and cyberattacks, which require a separate cyber liability policy.
- Other Exclusions: Claims related to patent infringement, pollution, or events that occurred before your policy’s retroactive date are also commonly excluded.
By understanding these exclusions, you can ensure you have the right combination of policies to protect your business. See What is Errors and Omissions Liability Insurance? for more details.
Why E&O is Non-Negotiable for Independent Professionals
As an independent contractor, you operate without the safety net of a corporate employer, making you personally liable for your work. This is why errors and omissions insurance for independent contractors has become an essential tool for survival and growth.

Key Reasons E&O Insurance is Crucial:
- Client Requirements: Many companies now mandate E&O insurance before signing a contract. It’s a standard business practice to ensure you’re a responsible professional.
- Contractual Obligations: Contracts often specify minimum coverage amounts, such as $1 million. Without it, you’re disqualified from high-value projects.
- Protecting Your Assets: A single lawsuit can put your personal savings, home, and other assets at risk. E&O insurance shields you from devastating out-of-pocket legal fees, which can easily exceed $50,000 even for baseless claims.
- Building Credibility: Having insurance signals to clients that you are a serious, accountable professional, giving you a competitive edge.
- Peace of Mind: Knowing you’re protected allows you to focus on delivering excellent work without the constant worry of potential legal trouble.
Operating without E&O insurance can lead to a damaged reputation, loss of clients, and difficulty securing new projects. For more information on managing business risks, the U.S. Small Business Administration (SBA) offers valuable resources.
For more comprehensive information, read The Ins and Outs of Liability Insurance for 1099 Contractors.
[LIST] of Professions That Urgently Need E&O Coverage
Certain professions face particularly high risks when providing professional services. These roles typically involve giving advice, handling sensitive data, or creating intellectual property where mistakes can cause substantial financial losses for clients.
- IT consultants face constant exposure to technology-related claims. Whether it’s recommending faulty software, misconfiguring networks, or failing to prevent data breaches, the financial consequences for clients can be enormous.
- Marketing professionals steer copyright laws, brand protection, and performance guarantees daily. A single campaign using copyrighted material or failing to deliver promised results can trigger costly lawsuits.
- Accountants handle their clients’ most sensitive financial information. Tax preparation errors, audit mistakes, or incorrect financial reporting can result in substantial penalties and losses that clients will expect you to cover.
- Real estate agents operate in a highly regulated environment where disclosure requirements are strict and transaction values are high. Many states actually require E&O coverage for real estate professionals.
- Architects and engineers create designs that become physical structures. Design flaws or calculation errors can lead to construction delays, safety issues, and massive financial losses.
- Business consultants provide strategic advice that directly impacts their clients’ operations and profitability. When that advice doesn’t work out as planned, consultants often face claims for the resulting losses.
- Web developers create digital products that businesses depend on for revenue. Coding errors, security vulnerabilities, or missed deadlines can cause significant financial harm to clients who rely on their digital presence.
Learn more about Errors and Omissions Insurance for Real Estate Agents and Errors and Omissions Insurance for Life Insurance Agents.
E&O vs. Other Key Policies: What’s the Difference?
Navigating business insurance can feel like learning a new language. Independent contractors often come across terms like General Liability (GL) and Directors & Officers (D&O) insurance, and it’s easy to confuse them with errors and omissions insurance for independent contractors. While all are forms of liability protection, they cover very different types of risks. Understanding these distinctions is crucial for building a comprehensive insurance strategy.
| Policy Type | What It Covers | Who It Protects | Example Claim |
|---|---|---|---|
| Errors & Omissions (E&O) | Professional mistakes, negligence, missed deadlines, undelivered services that cause financial loss. | The professional or business providing the service. | An IT consultant’s faulty configuration causes a client’s system outage and revenue loss. |
| General Liability (GL) | Bodily injury, property damage, and personal/advertising injury. | The business, from claims arising from its premises or operations. | A client slips and falls in your office, or you accidentally damage their property during a visit. |
| Directors & Officers (D&O) | Alleged wrongful acts, mismanagement, or breach of duty by company leaders. | The company’s directors and officers. | Shareholders sue the board for making a poor financial decision that devalued the company’s stock. |
This table emphasizes the distinct focus of each policy:
- Business liability insurance: A broad term for various types of insurance that protect businesses from legal liability.
- Bodily injury: Physical harm to a person, typically covered by general liability.
- Property damage: Physical damage to property, also typically covered by general liability.
- Directors and Officers: Refers to individuals in leadership roles within a company, whose decisions are covered by D&O insurance.
- Management decisions: The actions and choices made by a company’s leadership, which fall under D&O coverage.
See Business Liability Insurance and Do Independent Contractors Need General Liability Insurance?.
Errors & Omissions vs. General Liability Insurance
This is a common point of confusion. While both E&O and General Liability (GL) insurance protect against lawsuits, they cover different risks:
- E&O Insurance: Covers financial loss to a client resulting from your professional services, advice, or mistakes. For example, if an IT consultant’s advice leads to a costly system outage, E&O would apply.
- General Liability Insurance: Covers bodily injury and property damage. For example, if a client trips over your equipment in their office and is injured, GL would apply.
Many independent contractors need both policies for comprehensive protection, as they address distinct types of claims. Learn more: What is General Liability Insurance for Small Business?
Errors & Omissions vs. Directors & Officers (D&O) Insurance
E&O and D&O insurance protect against different types of liability:
- E&O Insurance: Protects the professional from claims related to their service delivery (e.g., faulty advice).
- D&O Insurance: Protects the company’s directors and officers from claims related to their management decisions (e.g., mismanagement of company funds).
As an independent contractor, E&O is your primary concern. D&O becomes relevant if you run a larger firm with a formal board or executive team.
Understanding the Cost of Errors and Omissions Insurance for Independent Contractors
One of the most common questions we hear from independent contractors is about cost. When you’re running your own business, every expense matters, and errors and omissions insurance for independent contractors is no exception. The good news? It’s likely more affordable than you think.
Most independent contractors pay between $500 and $1,000 per year for E&O coverage, with the average monthly cost sitting around $61. To put this in perspective, that’s roughly the cost of a dinner out each month for protection that could save your business from financial ruin.

Of course, your actual cost depends on several factors unique to your situation. The cost of E&O insurance for independent contractors is influenced by your industry, business size, claims history, location, coverage limits, and deductible. By understanding these factors, you can make informed decisions about your insurance needs and manage your costs effectively. See Errors and Omissions Insurance Cost for more details.
Key Factors That Influence Your Premium
Think of your E&O premium like a recipe – different ingredients combine to create your final cost. Here’s what insurance companies consider when calculating your rate:
Industry risk plays the biggest role in determining your premium. If you’re an IT consultant who could accidentally crash a client’s entire system, you’ll pay more than a freelance writer whose worst mistake might be a typo. High-risk professions like financial advisors or architects can see premiums exceeding $3,000 annually, while consultants typically pay around $55 per month or $662 annually.
Your claims history tells insurers everything they need to know about your risk level. A clean record keeps your rates low, while past claims can drive up your premium significantly. It’s like your driving record – accidents follow you around for years.
Business location matters more than you might think. Here in California, we deal with specific state regulations and legal environments that can affect pricing. Insurance companies know that some areas see more lawsuits than others, and they price accordingly.
Coverage limits directly impact your premium. Most independent contractors choose $1 million per occurrence, but you can go as low as $500,000 or as high as $2 million or more. Higher limits mean better protection but also higher costs – it’s all about finding the right balance for your business.
The deductible amount works like a seesaw with your premium. The average deductible sits around $2,500, but choosing a higher deductible can lower your monthly costs. Just make sure you can comfortably cover that amount if you need to file a claim.
Years of experience can work in your favor. Seasoned professionals with proven track records often qualify for lower rates because insurers see them as less likely to make costly mistakes.
How to Reduce Your E&O Insurance Premiums
While errors and omissions insurance for independent contractors is a vital investment, there are ways to manage the cost:
- Implement Strong Risk Management: Use clear contracts, maintain detailed records, and pursue professional development to demonstrate you’re a low-risk client.
- Bundle Your Policies: Combine E&O with general liability or a Business Owner’s Policy (BOP) for significant discounts. A BOP bundles general liability and commercial property insurance, simplifying your coverage. Learn more about a Business Owner’s Policy (BOP).
- Choose a Higher Deductible: If you can afford a higher out-of-pocket cost in the event of a claim, a higher deductible will lower your premium.
- Pay Annually: Insurers often offer a discount for paying your premium in one lump sum instead of monthly installments.
- Shop Around: Don’t settle for the first quote. At ISU Armac, we specialize in comparing rates from multiple carriers to find you the best coverage at the most competitive price.
The goal is to find the right balance between affordable premiums and adequate protection for your business.
Frequently Asked Questions about E&O Insurance
We understand that navigating insurance can feel overwhelming, especially when you’re trying to focus on running your business. Here are the most common questions we hear from independent contractors looking into errors and omissions insurance for independent contractors:
How much does errors and omissions insurance for independent contractors typically cost?
The cost varies, but most independent contractors pay between $500 and $1,000 per year, with an average monthly premium around $61. Your final price depends on your profession, coverage limits, and claims history. For example, a consultant might pay around $55 per month, while a high-risk professional like an architect could see higher rates.
What information do I need to get an E&O insurance quote?
To get an accurate quote for errors and omissions insurance for independent contractors, you’ll typically need to provide:
- Your business name and address.
- A description of your professional services.
- Your estimated annual revenue.
- The number of employees, if any.
- Your desired coverage limits and deductible.
- Your claims history.
Having this information ready will make the process quick and easy.
Can a client require me to have E&O insurance?
Yes, and it’s increasingly common. Many clients, especially larger companies, will contractually require you to have errors and omissions insurance for independent contractors. This protects them from financial loss if your work causes damages and shows them you’re a professional who takes accountability seriously. For some professions, E&O insurance is also a licensing requirement. It’s not just a good idea—it’s often a prerequisite for winning and keeping high-value contracts.
Conclusion
The reality of independent contracting is that even the most careful professionals can face claims. A single mistake or baseless accusation can threaten your entire business. This is why errors and omissions insurance for independent contractors is more than an expense—it’s your financial lifeline and professional shield.
Investing in E&O coverage protects your business from devastating financial losses, establishes financial security, and builds professional credibility. It sets you apart from uninsured competitors and opens doors to higher-value contracts.
At ISU Armac, we understand the unique challenges facing independent contractors throughout Southern California, from Victorville and Apple Valley to Hesperia and Oak Hills. We’ve helped countless professionals like you secure the right coverage at the right price by shopping multiple insurance carriers to find the best protection at the lowest rates.
We create custom policies custom to your specific needs and budget. A freelance graphic designer needs different coverage than an IT consultant, and we ensure your policy reflects that reality.
Don’t gamble with your professional future. The cost of going without E&O insurance far outweighs the affordable premiums for comprehensive protection. Take control of your business security today.