
Why Employee Benefits Insurance Companies Matter for Your Business
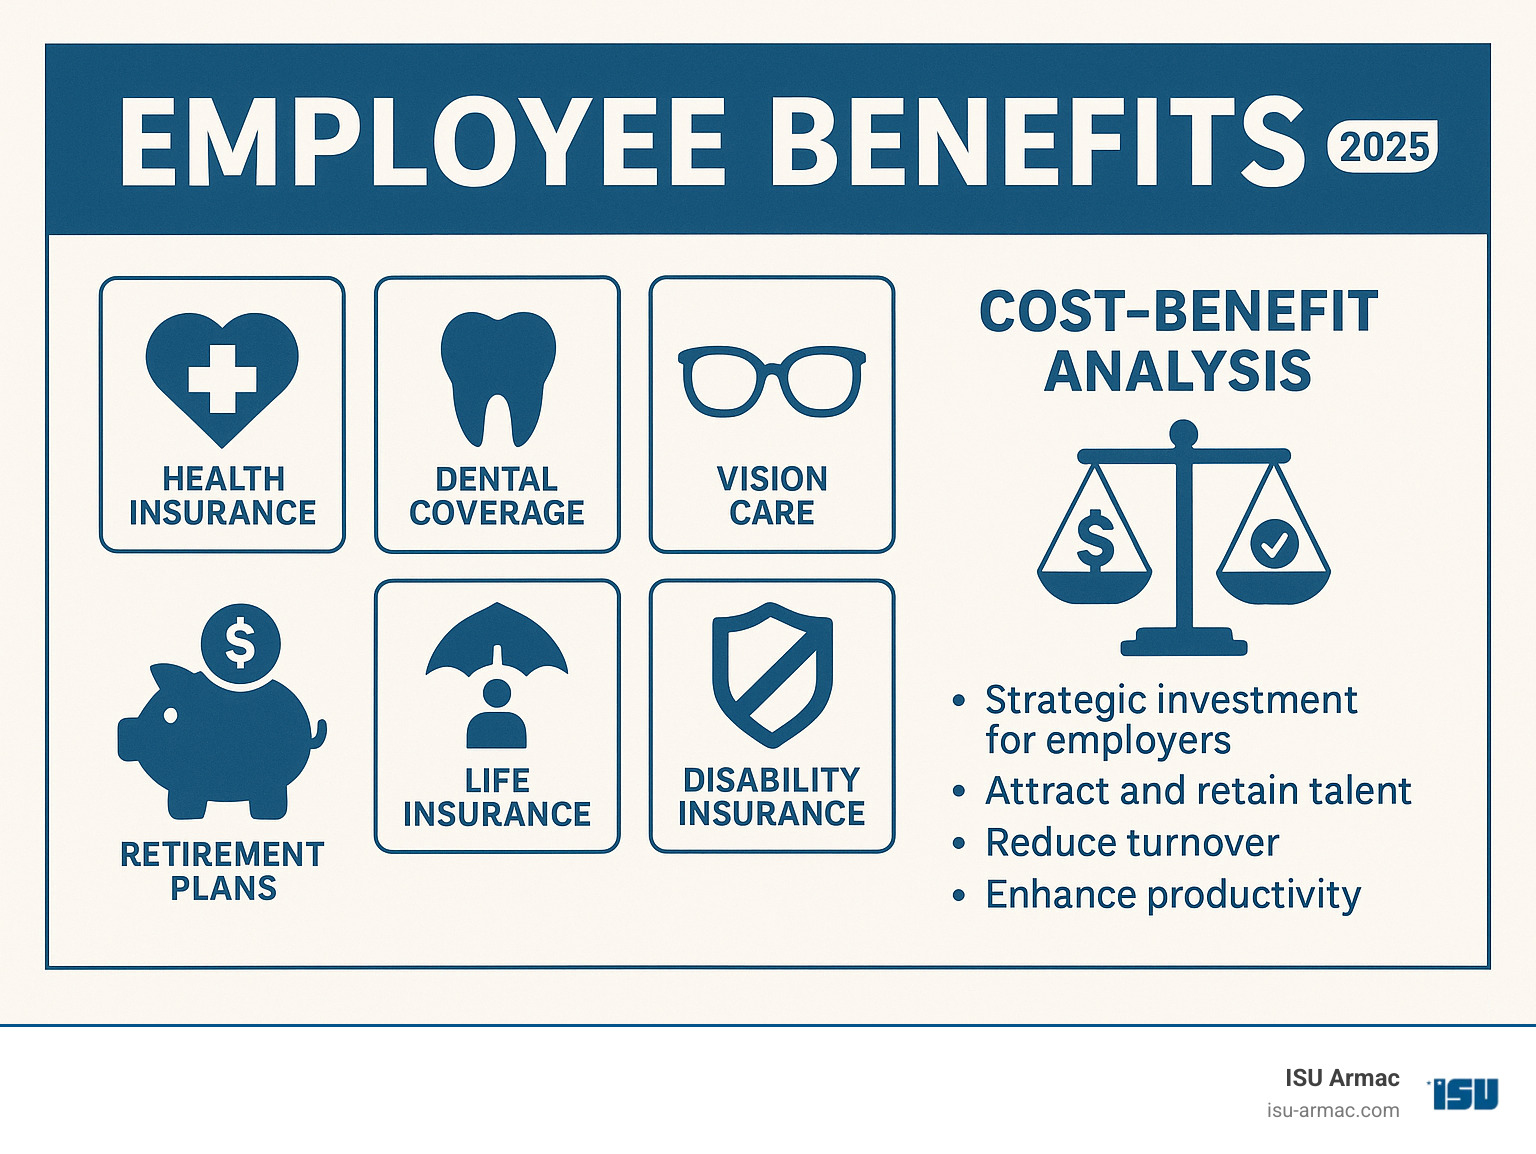
Employee benefits insurance companies provide the foundation for modern workplace compensation packages, offering everything from health and dental coverage to life insurance and disability protection. These specialized insurers help businesses attract top talent, retain valuable employees, and create comprehensive benefit packages that go far beyond basic salary offerings.
Top Employee Benefits Insurance Companies to Consider:
- GreenShield Canada – Over 65 years of experience with integrated health solutions
- Manulife – Comprehensive group benefits with mobile app management
- Sun Life Financial – Extensive network and flexible plan options
- Canada Life – Strong reputation for customer service and plan administration
- Desjardins Insurance – Competitive rates for small to medium businesses
- RBC Insurance – Full-service benefits with wellness program support
- Chambers Plan – Not-for-profit option serving 30,000+ Canadian businesses
The decision to offer employee benefits represents a strategic investment in your company’s future. Research shows that businesses offering comprehensive benefits packages see improved employee satisfaction, reduced turnover, and improved productivity. With over 30,000 small to midsize businesses choosing specialized benefit plans and providers investing millions in member health improvements, the trend toward robust employee benefits continues to grow.
From legally required coverage like Workers’ Compensation to optional perks like dental and vision insurance, these companies design packages that work for businesses of all sizes. Whether you need basic coverage for a small team or comprehensive benefits for a growing organization, the right insurance partner can make benefits administration simple and cost-effective.
As Ryan McEachron, CEO of ISU Insurance Services ARMAC Agency in Victorville, I’ve helped countless local businesses steer the complex world of employee benefits insurance companies to find solutions that fit their budget and workforce needs. My experience working with various providers has shown me how the right benefits package can transform a company’s ability to compete for talent in today’s market.
Easy employee benefits insurance companies word list:
- benefits of offering health insurance to employees
- employee healthcare plans
- employee life insurance benefits
Understanding the Core Components of an Employee Benefits Package
Building a strong employee benefits package is like putting together a puzzle – each piece needs to fit perfectly to create the complete picture your team needs. Employee benefits insurance companies offer a wide range of coverage options, from basic legally required protections to comprehensive packages that can truly set your business apart in today’s competitive job market.

Think of employee benefits as having two main categories: the foundation you must provide by law, and the extras that make your company shine. The foundation includes things like Workers’ Compensation and Unemployment insurance – these aren’t optional, but they’re just the starting point. The real magic happens when you add voluntary benefits like health insurance, dental coverage, and retirement plans.
Many business owners ask us about flexible options, and that’s where Health Spending Accounts (HSAs) and flexible plans come into play. These allow your employees to customize their coverage based on their individual needs. It’s like giving them a benefits buffet where they can choose what works best for their situation. Our Group Health Insurance Benefits page has more details on how these work together.
Legally Required vs. Optional Benefits
Let’s start with what you absolutely must provide. Workers’ Compensation covers your employees if they get hurt on the job – this one’s non-negotiable in most states. Unemployment insurance helps your former employees if they lose their job through no fault of their own. If you have 50 or more employees, the Family and Medical Leave Act (FMLA) requires you to provide unpaid leave for certain family and medical situations.
Now here’s where it gets interesting – and where you can really make your mark. Paid time off, retirement plans, and health insurance aren’t always required by law, but they’re often expected by today’s workforce. The question many small business owners ask is: Are Small Businesses Required to Provide Health Insurance? The answer depends on your company size and state, but offering these benefits can be your secret weapon for attracting great people.
The beauty of optional benefits is that they let you tailor your package to what your employees actually want. Some teams value generous vacation time, while others prefer robust health coverage. The key is finding the right mix that fits both your budget and your team’s needs.
Core Insurance Offerings
When most people think “employee benefits,” they’re thinking about the core insurance offerings. These are the heavy hitters that provide real financial protection for your team and their families.
Group Medical coverage is often the crown jewel of any benefits package. It helps employees handle everything from routine doctor visits to major medical emergencies without breaking the bank. Group Dental keeps those smiles bright and healthy, covering everything from cleanings to more complex procedures.
Don’t overlook Group Vision coverage – it might seem small, but when someone needs new glasses or contacts, they’ll really appreciate having this benefit. Employee Life Insurance Benefits provide peace of mind, ensuring that if something happens to an employee, their family has financial support during a difficult time.
Short-term disability and long-term disability insurance are the safety nets that catch employees when life throws them a curveball. Short-term coverage helps if someone needs a few months to recover from surgery or an illness. Long-term disability is there for more serious situations that could keep someone out of work for years.
These core offerings work best when they’re designed to complement each other. A good benefits package flows together seamlessly, covering the gaps and providing comprehensive protection that gives your employees real peace of mind.
Supplemental and Voluntary Coverage
Here’s where you can get creative and really customize your benefits package. Supplemental and voluntary coverage options let you offer additional protection without necessarily increasing your costs dramatically.
Accident insurance pays cash directly to employees when accidents happen – and let’s face it, accidents do happen. This money can cover deductibles, co-pays, or even help with everyday expenses while someone recovers. Critical illness insurance provides a lump sum if an employee faces a serious diagnosis like cancer or heart disease. Hospital indemnity coverage pays a daily benefit when someone’s stuck in the hospital.
What makes these Group Voluntary Benefits so attractive is their flexibility. Employees often pay for them with pre-tax dollars, which saves them money, and you can offer valuable coverage without a huge impact on your budget.
Some business owners wonder about alternatives, like whether they Can a Small Business Pay for Individual Health Insurance? instead of group coverage. These supplemental options can work alongside traditional group plans or serve as valuable additions to alternative arrangements.
The best part about working with experienced employee benefits insurance companies is that they help you mix and match these options to create a package that’s uniquely yours. Every business is different, and your benefits should reflect that.
The Dual Advantage: Why Offering Benefits is a Win-Win
When you decide to offer employee benefits, you’re not just checking a box or following what other companies do. You’re making a smart business move that pays dividends for everyone involved. Think of it as planting seeds that grow into stronger relationships, better performance, and a healthier bottom line.
The numbers tell a compelling story. According to 2023 data from the U.S. Bureau of Labor Statistics, benefits can cost employers about $13-14 per hour for private sector employees. While that might sound expensive at first glance, it represents tremendous value when you consider what both you and your employees get in return.
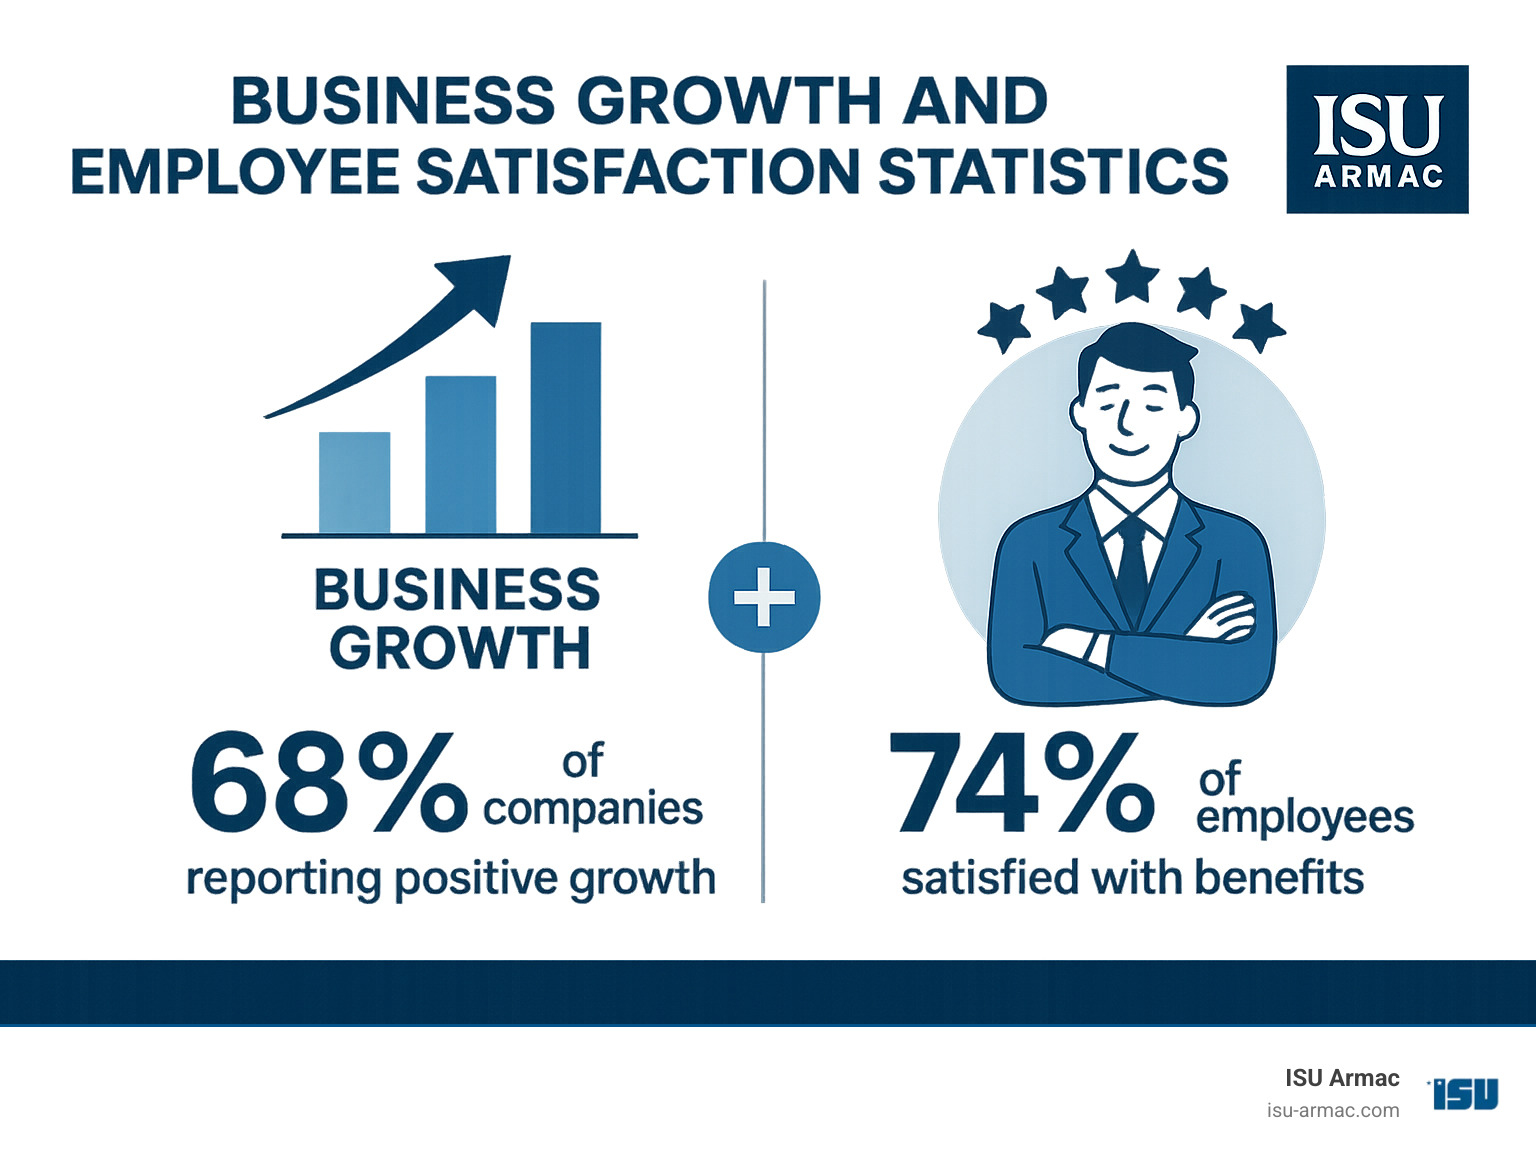
The beauty of working with quality employee benefits insurance companies is that they understand this mutual benefit. They design packages that create real value for both sides of the equation, making the investment worthwhile for businesses while delivering meaningful protection for employees.
Key Advantages for Employers
Let’s start with what benefits do for your business. The most obvious advantage is talent attraction and retention. In today’s job market, skilled workers have choices. They’re not just looking at salary numbers anymore – they want to know you’ll take care of them when life happens.
When you offer comprehensive benefits, you’re telling potential employees that you value them as whole people, not just workers. This message resonates powerfully, especially with younger workers who prioritize work-life balance and financial security.
Employee retention becomes much easier when people feel secure. It’s expensive to replace good employees – between recruiting costs, training time, and lost productivity, turnover can cost 50% to 200% of an employee’s annual salary. Benefits help keep your best people right where they are.
Here’s something that might surprise you: offering benefits can actually increase productivity. When employees aren’t worried about how they’ll pay for their child’s dental work or what happens if they get sick, they can focus on their jobs. Less financial stress means better performance, fewer sick days, and higher morale across your team.
From a financial standpoint, benefits offer tax advantages that make them more cost-effective than straight salary increases. The premiums you pay are generally tax-deductible business expenses, and you don’t pay additional payroll taxes on benefit contributions like you would on wages.
Finally, benefits give you a competitive edge, especially as a smaller business. Programs like the Small Business Health Exchange allow you to offer big-company benefits without big-company overhead, helping you compete for talent with much larger organizations.
Key Advantages for Employees
Now let’s talk about what your employees gain. The biggest benefit is financial security. Medical emergencies, prescription costs, and dental work can create serious financial strain for families. Group benefits act as a safety net, protecting your employees from these unexpected expenses.
Access to healthcare becomes much more affordable through group plans. Individual insurance is expensive and often limited. Group coverage typically costs less and provides better access to doctors, specialists, and treatment options. This means your employees can take care of their health proactively instead of waiting until problems become serious.
The peace of mind that comes with good benefits is invaluable. According to research from organizations like Unum, employees with disability insurance and supplemental coverage worry less about financial catastrophe, which translates to better mental health and job satisfaction.
Reduced out-of-pocket costs make a real difference in family budgets. When employees can afford regular checkups, prescription medications, and preventive care, they stay healthier and miss less work. It’s a cycle that benefits everyone.
Many modern benefit packages also include wellness programs and Employee Assistance Programs that support overall well-being. These resources help employees manage stress, maintain work-life balance, and address personal challenges before they impact job performance.
Understanding Employee Healthcare Plans helps your team maximize these advantages and get the most value from their benefits package.
The bottom line is simple: when you invest in employee benefits, you’re investing in mutual success. Your business becomes stronger, more competitive, and more attractive to top talent, while your employees gain security, peace of mind, and better access to healthcare. That’s what we call a true win-win situation.
How to Choose the Right Employee Benefits Insurance Partner
Choosing the right partner from among employee benefits insurance companies is one of the most important decisions you’ll make for your business. It’s not just about finding the cheapest option – you’re looking for a true partner who understands your unique needs and will be there when your employees need support most.
Think of it this way: your benefits provider becomes an extension of your HR team. They’ll be handling some of your most valued employees’ most important needs. That’s why taking time to evaluate potential partners thoroughly is so crucial.
Evaluating Coverage and Plan Design
The foundation of any good benefits partnership starts with understanding exactly what your team needs. Every workforce is different, and what works for a tech startup might not be right for a manufacturing company.
Start with a thorough needs assessment. Look at your employee demographics – are they mostly young professionals who prioritize mental health coverage, or families who need comprehensive dental care? Understanding these patterns helps you design a package that truly serves your people.
Plan flexibility is where many providers either shine or fall short. The best partners offer customization options that let you build benefits around your specific budget and workforce needs. Some companies need extensive prescription drug coverage, while others might prioritize vision care or disability insurance. Look for providers who can adapt their offerings rather than forcing you into a one-size-fits-all approach.
Don’t overlook provider networks when making your decision. Even the most generous coverage doesn’t help if your employees can’t find convenient doctors or specialists. Make sure your chosen provider has strong networks in your area, with reasonable wait times for appointments.
We often help businesses explore Association Health Plans for Small Business or steer the Shop Small Business Health Options Program to find that perfect fit between coverage and cost.
Assessing Technology and Service from Employee Benefits Insurance Providers
The technology behind your benefits can make or break the employee experience. Nobody wants to deal with clunky websites or confusing paperwork when they’re trying to get medical care.
Look for administration platforms that actually make your life easier, not harder. The best systems are intuitive enough that you don’t need a manual to figure out basic tasks. Your HR team shouldn’t need to become insurance experts just to manage your benefits.
Employee self-service portals are absolutely essential. Your team should be able to check their coverage, submit claims, and get answers to basic questions without having to call anyone. This isn’t just convenient – it reduces the administrative burden on your staff and gives employees the independence they want.
Mobile app access has become a must-have feature. When someone needs to check if their prescription is covered or submit a claim photo, they want to do it from their phone, not wait until they’re back at a computer.
Claim processing speed directly impacts employee satisfaction. Nobody wants to wait weeks to get reimbursed for medical expenses. The best providers process claims quickly and keep everyone informed about the status.
Most importantly, customer support reliability can save you countless headaches. When problems arise – and they will – you need to know that real people will answer the phone and actually solve issues, not just transfer you around.
We specialize in connecting businesses with Health Insurance for Employees that comes with the kind of technological support that makes benefits administration smooth and stress-free.
Comparing Costs and Value
While cost is always important, the cheapest option rarely delivers the best value for your business or employees. Smart benefits shopping means looking at the complete picture.
Premium analysis should compare apples to apples across different providers. Make sure you’re looking at similar coverage levels and deductibles when comparing prices. Group benefits typically cost less than individual plans, but the savings can vary significantly between providers.
Understanding cost-sharing models helps you budget effectively. Many successful companies split health insurance premiums with employees or offer basic life insurance coverage while allowing employees to purchase additional coverage at group rates. The key is finding a balance that works for your budget while still providing meaningful value to your team.
Rate stability often matters more than the initial premium. Some providers offer attractive introductory rates that jump dramatically after the first year. Look for companies with a track record of predictable, reasonable rate increases. Pooled programs often provide more stable premiums because they spread risk across many similar businesses.
Long-term value extends beyond just medical coverage. Does the provider offer wellness programs that could help keep your team healthier and reduce future costs? Do their benefits contribute to employee satisfaction and retention? The money you save on recruiting and training by keeping good employees often far exceeds the cost of better benefits.
Finally, consider the provider’s financial strength. You want to partner with a company that will be around to pay claims and honor commitments years down the road.
At ISU Armac, we help businesses find Small Business Medical Insurance that delivers exceptional value, not just low prices. Ready to explore your options? Get a Group Benefits Quote and let us help you find the perfect partner for your team’s needs.
Frequently Asked Questions About Employee Benefits Insurance
When it comes to employee benefits insurance companies and the plans they offer, we hear the same questions over and over again from business owners and employees alike. Let me walk you through the most common concerns we address here at ISU Armac, drawing from our years of experience helping Victorville businesses steer the benefits landscape.
What is the minimum number of employees needed for a group plan?
This is probably the most frequent question we get from small business owners, and the good news is that the bar is pretty low. Most employee benefits insurance companies require just 2 to 3 employees to qualify for a group benefits plan. Some providers might ask for slightly more, but this range covers the vast majority of options available.
Here’s what makes it even better: part-time employees can often be included in these plans too. Many of our clients choose to extend benefits to their part-time staff, and we’ve found it’s a fantastic way to boost morale and keep good people around longer. The flexibility varies by provider, but there are definitely options designed specifically to accommodate mixed full-time and part-time workforces.
If you’re wondering whether your small business qualifies, we can help you explore Health Insurance for Employees Small Business options that work with your current team size.
What is the difference between Workers’ Comp and Disability Insurance?
This question trips up a lot of people, and honestly, I don’t blame them. Both types of coverage help replace income when someone can’t work, but they kick in under completely different circumstances.
Workers’ Compensation is all about work-related injuries and illnesses. Think of an employee who hurts their back lifting heavy boxes at your warehouse, or someone who develops carpal tunnel from repetitive computer work. Workers’ Comp covers their medical bills, replaces a portion of their lost wages, and sometimes even pays for retraining if they can’t return to their old job. In most states, this coverage is legally required if you have employees, and you as the employer pay the entire premium.
Disability Insurance, on the other hand, covers non-work-related health issues. If your employee breaks their leg skiing on the weekend, gets diagnosed with diabetes, or needs surgery for a condition unrelated to work, that’s where disability insurance steps in. This coverage is typically optional, and the costs are often shared between you and your employees.
The Bureau of Workers’ Compensation provides detailed information about state requirements, but the simple way to remember it is: Workers’ Comp handles “on-the-job” problems, while Disability Insurance covers “off-the-job” issues.
What happens to my benefits if I leave my job?
This is a big concern for employees, and rightfully so. Nobody wants to lose their health coverage just because they’re changing jobs. The good news is that there are several options, depending on the type of benefit.
For core insurance coverage like health, dental, and life insurance, most employees can convert their group coverage to an individual plan within a specific timeframe after leaving their job. Yes, individual premiums are usually higher than what they were paying as part of the group, but it means no gap in coverage while they’re job hunting or waiting for new employer benefits to kick in.
Many supplemental benefits are actually portable, meaning employees can take these policies with them and continue paying the premiums directly to the insurance company. This is especially common with accident insurance, critical illness coverage, and some life insurance policies.
COBRA continuation is another option for health coverage, allowing former employees to keep their group health plan for a limited time by paying the full premium themselves. It’s not cheap, but it bridges the gap.
For employees transitioning to self-employment or contractor work, we also provide guidance on Health Insurance for Independent Contractors to help them maintain coverage during career transitions.
The key is understanding your options before you need them. We always encourage employees to speak with their HR department before making any job changes to understand exactly what benefits they can take with them and what they’ll need to replace.
Conclusion: Building a Competitive and Attractive Benefits Package
Creating a compelling employee benefits package isn’t just about checking boxes or meeting minimum requirements. It’s about making a strategic investment in your company’s most valuable asset: your people. When you partner with the right employee benefits insurance companies, you’re not just buying insurance policies—you’re building the foundation for a thriving workplace culture.
The most successful benefits packages don’t stay static. They evolve and grow with your business. Regular review of your offerings ensures you’re staying competitive in the talent market and meeting your employees’ changing needs. What worked for your team five years ago might not be what they value most today.
Employee feedback is pure gold when it comes to benefits planning. Your team members are the ones using these benefits day in and day out. They know which coverages make the biggest difference in their lives and where gaps might exist. Creating channels for honest feedback—whether through surveys, focus groups, or one-on-one conversations—helps you make informed decisions about your benefits investments.
The beauty of working with experienced professionals is that we handle the complex stuff so you can focus on what you do best: running your business. At ISU Armac, we’ve spent years building relationships with top carriers and understanding the ins and outs of benefits administration. We know which providers offer the best value, which plans work well for different types of businesses, and how to steer the ever-changing regulatory landscape.
Long-term success in benefits planning comes from viewing it as an ongoing partnership rather than a one-time purchase. The right insurance partner doesn’t just sell you a policy and disappear. They stay engaged, help you understand utilization patterns, assist with employee communications, and proactively suggest improvements as your business grows.
From our office in Victorville, we’ve helped businesses across Southern California—from small startups to established companies—create benefits packages that truly make a difference. Whether you’re just starting to explore options or looking to improve your current offerings, we’re here to guide you through every step of the process.
Ready to build something great for your team? Let’s start the conversation about what an exceptional benefits package could look like for your business. Visit our comprehensive Insurance Center/Service/Employee Benefits page or reach out for a personalized consultation. Your employees—and your bottom line—will thank you.