
Navigating the World of Classic Motorcycle Insurance
Classic motorcycle insurance is specialized coverage for vintage and collector motorcycles. Unlike standard policies, it’s designed for vehicles with unique values and usage patterns.
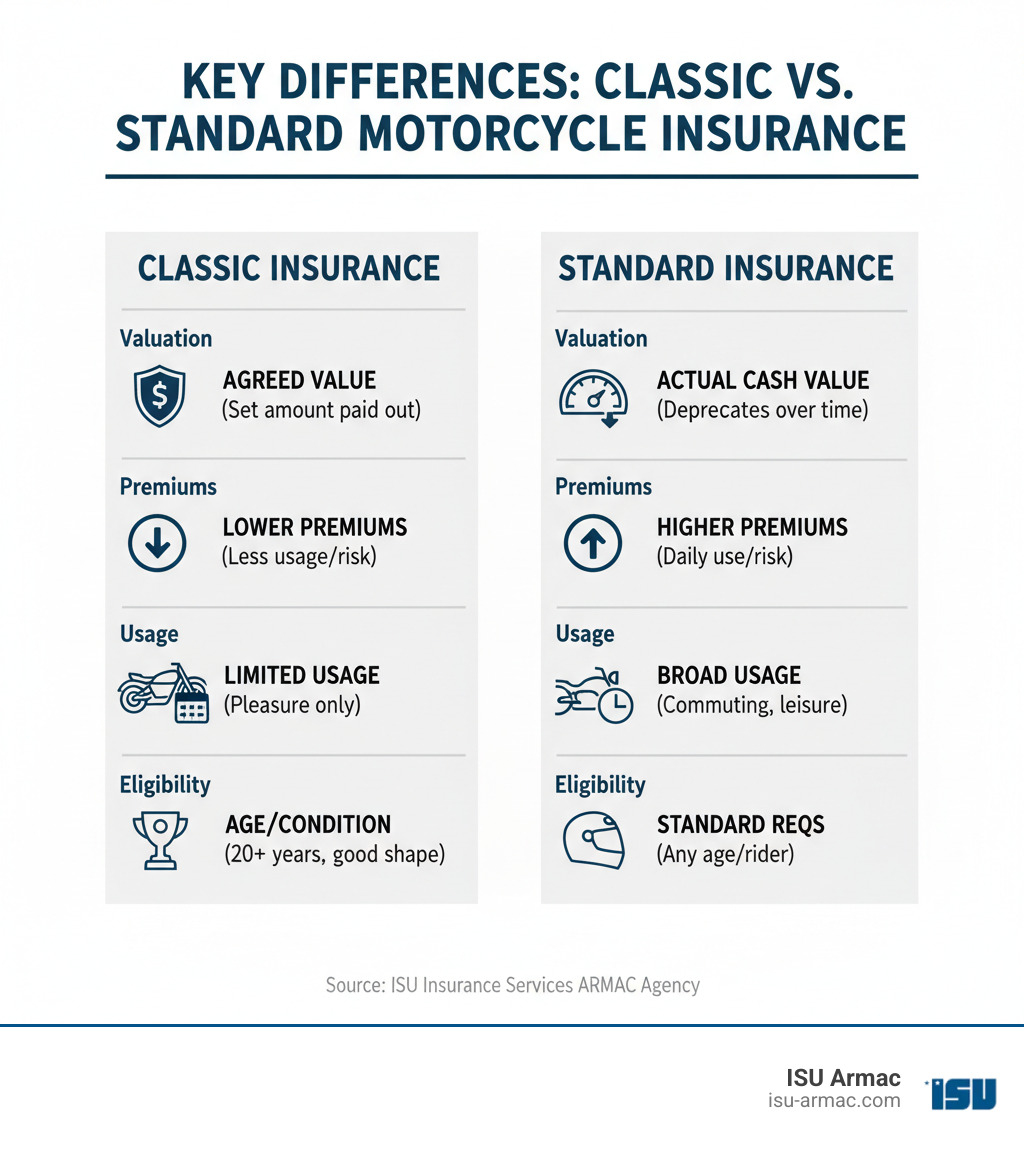
Key differences include:
- Valuation: Uses an “Agreed Value” model, where you and the insurer set the bike’s worth upfront. This amount is paid out in a total loss.
- Cost: Often less expensive than standard insurance because classic bikes are ridden less frequently and with greater care.
- Usage: Policies typically restrict use to pleasure rides and events, not daily commuting, and often include mileage limits.
- Eligibility: Bikes must meet age requirements (usually 20-25+ years) and be in good condition, while riders must also meet specific criteria.
Standard insurance often fails to protect these cherished pieces of history adequately. This guide explains how classic motorcycle insurance provides the right protection by covering policy differences, eligibility, and more.
As Ryan McEachron, CEO of ISU Insurance Services ARMAC Agency, I’ve seen the importance of specialized classic motorcycle insurance for owners in our Southern California community. We understand how to protect these unique assets.
What Defines a “Classic Motorcycle” for Insurance?
What makes a motorcycle a “classic” for insurance purposes? While rules vary by insurer, several common criteria determine eligibility for specialized classic motorcycle insurance. Understanding these factors is the first step to properly protecting your vintage ride.

First, age is a primary factor. Most insurers require a bike to be 25 years or older to qualify. Some are more flexible, considering bikes as young as 20, while others set the bar at 30 years. Certain modern classics with collector value may also be eligible, depending on the provider.
The condition of your motorcycle is also critical. Insurers prefer bikes in stock condition or professionally restored to their original state. Significant modifications that alter the bike’s original design or performance may affect eligibility or premiums, as the focus is on preserving historical integrity.
Finally, your bike must meet certain value thresholds. Because classic policies often use “Agreed Value” coverage, its market value must be established. This typically requires a professional appraisal, which serves as a critical document to set the agreed value and ensure you are fully covered in the event of a total loss.
Classic vs. Standard Motorcycle Insurance: A Head-to-Head Comparison
Standard motorcycle insurance often falls short for classic bikes because it’s designed for daily-use vehicles that depreciate. Classic motorcycle insurance operates on a different philosophy, built to protect a historical asset that often appreciates in value.
The most significant difference is the valuation method. A standard policy uses Actual Cash Value (ACV), which pays out the bike’s market value minus depreciation. For a classic, this amount can be far below its true worth. In contrast, classic policies use Agreed Value coverage. You and the insurer agree on the bike’s value upfront, usually based on an appraisal. If the bike is a total loss, you receive that exact agreed-upon amount, less your deductible, ensuring your investment is fully protected.
Another key distinction is usage limitations. Classic policies are designed for “pleasure use only,” such as parades, club events, shows, and occasional weekend rides. They do not cover daily commuting or business use. This limited usage is enforced through annual mileage caps, typically ranging from 2,000 to 7,500 miles.
These limitations lead to the best part: lower cost. Because classic bikes are ridden less and their owners are typically more experienced and careful, insurers see them as a lower risk. This translates into significant savings, with premiums often up to 40% lower than standard rates.
To give you a clearer picture, here’s a quick head-to-head comparison:
| Feature | Classic Motorcycle Insurance | Standard Motorcycle Insurance |
|---|---|---|
| Valuation | Agreed Value: Payout is a pre-agreed amount, ensuring full value. | Actual Cash Value (ACV): Payout is market value minus depreciation. |
| Premiums | Often lower (can save up to 40%) due to limited use, careful owners, and specific eligibility. | Higher due to broader usage assumptions and higher perceived risk. |
| Usage | Limited to pleasure use (parades, shows, club events), often with mileage caps (e.g., 2,000-7,500 miles/year). No daily commuting. | Broad usage, including daily commuting, long-distance travel, and varied conditions. |
| Eligibility | Stricter requirements for bike age (20-25+ years), condition (stock/restored), rider age (30+), and driving record. | Broader eligibility for newer bikes and a wider range of rider profiles. |
| Focus | Protects the unique value and historical integrity of collector vehicles. | Covers functional, everyday transportation with a focus on replacement cost. |
Choosing the right insurance isn’t just about fulfilling a requirement; it’s about truly protecting what you love. If your bike fits the classic description, standard insurance simply won’t give it the specialized care and financial protection it deserves. For those who also have everyday bikes, or just want to learn more about basic coverage, you can always explore our resources on motorcycle insurance for beginners.
Understanding Your Classic Motorcycle Insurance Policy
Your classic motorcycle insurance policy is a specialized contract designed to protect your vintage ride. It combines standard protections with unique add-ons custom for collector vehicles. Let’s review the key components.

Standard Coverages You Can Expect
Even with a classic motorcycle, some basic coverages are essential and often required by law in California. They form the foundation of your policy.
- Liability Coverage (Bodily Injury and Property Damage) is mandatory in California and covers costs for injuries to others or damage to their property if you are at fault in an accident.
- Collision Coverage helps pay for repairs to your classic motorcycle if it’s damaged in a collision with another vehicle or object, regardless of fault.
- Comprehensive Coverage protects your bike from non-collision events like theft, vandalism, fire, and natural disasters. It’s invaluable for protecting a bike with hard-to-find parts.
- Uninsured/Underinsured Motorist (UM/UIM) coverage is highly recommended. It protects you and your bike if you’re in an accident with a driver who has insufficient or no insurance.
For a clearer picture of what it means to have full, robust protection for your motorcycle, especially custom for our California roads, dive into our guide on full coverage motorcycle insurance California.
Popular Optional Coverages for Your Classic Bike
This is where classic motorcycle insurance truly shines, with specialized options for collectors.
- Agreed Value Coverage is the cornerstone of classic insurance. You and the insurer agree on the bike’s value upfront, and that’s the amount you receive in a total loss, ensuring no disputes over depreciation.
- Roadside Assistance helps with towing, jump-starts, or flat tires if you’re stranded.
- Spare Parts Coverage protects valuable extra components you have stored, often up to a set limit like $500.
- Motorcycle Apparel Coverage helps replace your helmet, jacket, and other gear if damaged or stolen in a covered incident.
- Trip Interruption coverage helps cover costs like lodging and food if your bike breaks down far from home.
- Cherished Salvage® allows you to keep your bike’s frame or parts after a total loss payout, preserving its legacy.
- Vehicle Under Construction coverage lets you increase your agreed value as your restoration project progresses, protecting your growing investment. Some policies also cover your tools.
These specialized options lift your classic motorcycle insurance to a comprehensive guardian for your unique machine. To explore all the custom-fit coverage options available for your specific needs, cruise over to our page on motorcycle insurance services.
What to Know About Classic Motorcycle Insurance for Modified or Restoration Bikes
Specialized classic motorcycle insurance providers are generally flexible when it comes to customized bikes.
If your bike has been Modified, eligibility depends on the extent of the changes. Period-correct alterations are usually fine, but radical modifications may be harder to insure. Honesty with your insurer is key. For Custom-Built bikes, specific rules may apply, such as age (e.g., 1975 or older) and minimum value (e.g., $7,500).
If you’re restoring a bike, Vehicle Under Construction Coverage is essential, allowing you to increase its value as work progresses. Some policies also offer Increased Value Endorsements or “Inflation Guard” to automatically increase your coverage over time. For any modified or restored classic, a Detailed Appraisal is critical. It must outline all changes and the resulting value to ensure accurate coverage.
Eligibility and Cost: Qualifying for Classic Motorcycle Insurance
Securing classic motorcycle insurance is a great way to protect your ride at an affordable rate. To access these benefits, both you and your motorcycle need to meet a few key criteria.
Do You Qualify? Common Eligibility Requirements
Insurers have specific requirements for both the rider and the motorcycle to qualify for the lower rates of classic motorcycle insurance. These criteria identify a lower-risk group.
For the rider, this typically includes:
- Age: 30 years or older (some exceptions for 21+).
- Experience: 5-6+ years of licensed, claims-free riding.
- Driving Record: A clean record with no more than one moving violation or at-fault accident in the last three years.
- Primary Vehicle: You must own and insure a separate vehicle for daily use.
For the motorcycle, secure storage in a fully enclosed, locked garage or similar structure is required. If your driving record isn’t quite spotless, you can explore our resources on motorcycle insurance for high-risk drivers to understand alternative paths to coverage.
How Premiums Are Calculated and Why It’s Often Cheaper
The affordability of classic motorcycle insurance, with savings up to 40% over standard policies, comes from a lower risk profile. Insurers calculate premiums based on several factors:
- Lower Risk Profile: Classic owners are generally more mature and cautious, resulting in fewer claims.
- Limited Mileage: Annual mileage caps (e.g., 2,000-7,500 miles) mean less time on the road and reduced accident risk.
- Pleasure Use Only: Using the bike for shows, club events, and leisure rides—not daily commuting—minimizes exposure to high-risk traffic.
- Bike and Location: The motorcycle’s age, type, and your location in Southern California also influence the final premium.
To get a better idea of how these factors might influence your specific costs right here in Southern California, you can learn more about how much motorcycle insurance costs in California.
How to Save Money on Your Classic Motorcycle Insurance Premium
Even with lower base rates, you can save more on your classic motorcycle insurance premium.
- Bundling Policies: Combine your motorcycle insurance with your auto or home policy for a significant discount.
- Multi-Bike Discount: Insuring multiple classic or modern bikes with one provider can save you around 10%.
- Club Member Discounts: Membership in recognized organizations like the Antique Motorcycle Club of America (AMCA) can earn you a discount.
- Safety Course: Completing an approved motorcycle safety course often lowers your premium.
- Payment Options: Paying your premium in full annually or choosing a higher deductible can reduce your overall cost. Just ensure the deductible is an amount you can comfortably afford.
By strategically combining these tips, you can secure even more affordable classic motorcycle insurance rates. For a personalized approach to finding the most cost-effective coverage in Southern California, check out our insights on affordable motorcycle insurance California.
Frequently Asked Questions
It’s natural to have questions when protecting a classic motorcycle. Here are answers to some of the most common inquiries we receive.
How often does my classic motorcycle need to be appraised?
For an agreed value policy, an initial professional appraisal no older than 12 months is typically required to establish your bike’s value. After that, a new appraisal may be needed every three to five years.
However, you should get an updated appraisal anytime you complete a major restoration or if the market value of your model increases significantly. Submitting the new appraisal to your insurer allows you to adjust your agreed value coverage accordingly.
What are the typical usage and mileage limitations?
Classic motorcycle insurance policies are strictly for pleasure use only. This includes rides, parades, club events, and shows. Using the bike for daily commuting or business purposes is prohibited and could void your coverage.
Policies also include annual mileage caps, with common tiers at 2,500, 5,000, or 7,500 miles per year. It is crucial to be honest about your intended usage to ensure your policy remains valid.
What documentation is typically required to get a policy?
To get a quote for classic motorcycle insurance, you will generally need the following documentation and information:
- A recent certified appraisal (less than 12 months old) for agreed value policies.
- Clear, recent photos of the motorcycle from all angles.
- A valid driver’s license and your riding history.
- Current vehicle registration.
- Proof of secure storage (e.g., a locked garage).
- Information on your primary daily-use vehicle(s).
Having these items ready will streamline the application process at ISU Armac, allowing us to quickly find the perfect protection for your classic motorcycle.
Conclusion: Protecting Your Prized Possession
Your classic motorcycle is a testament to your passion and a piece of rolling history. Protecting it requires insurance that reflects its unique value and your dedication.
As we’ve covered, classic motorcycle insurance offers superior protection through Agreed Value coverage, which guarantees your bike’s full worth in a total loss. It also provides lower costs due to limited, pleasure-only use and offers custom coverage options custom to collectors. Standard policies simply can’t match this level of specialized care.
Finding the right policy is about partnering with an agent who understands your needs. At ISU Armac, we are an independent agency serving Southern California, and we specialize in classic vehicle insurance. We act as your advocate, shopping multiple top-rated carriers to find the ideal combination of coverage and value.
Don’t leave your prized possession vulnerable. Let us help you secure the specialized protection it deserves so you can ride with complete peace of mind.