
Why Business Owners Insurance Is Essential for Protecting Your Livelihood
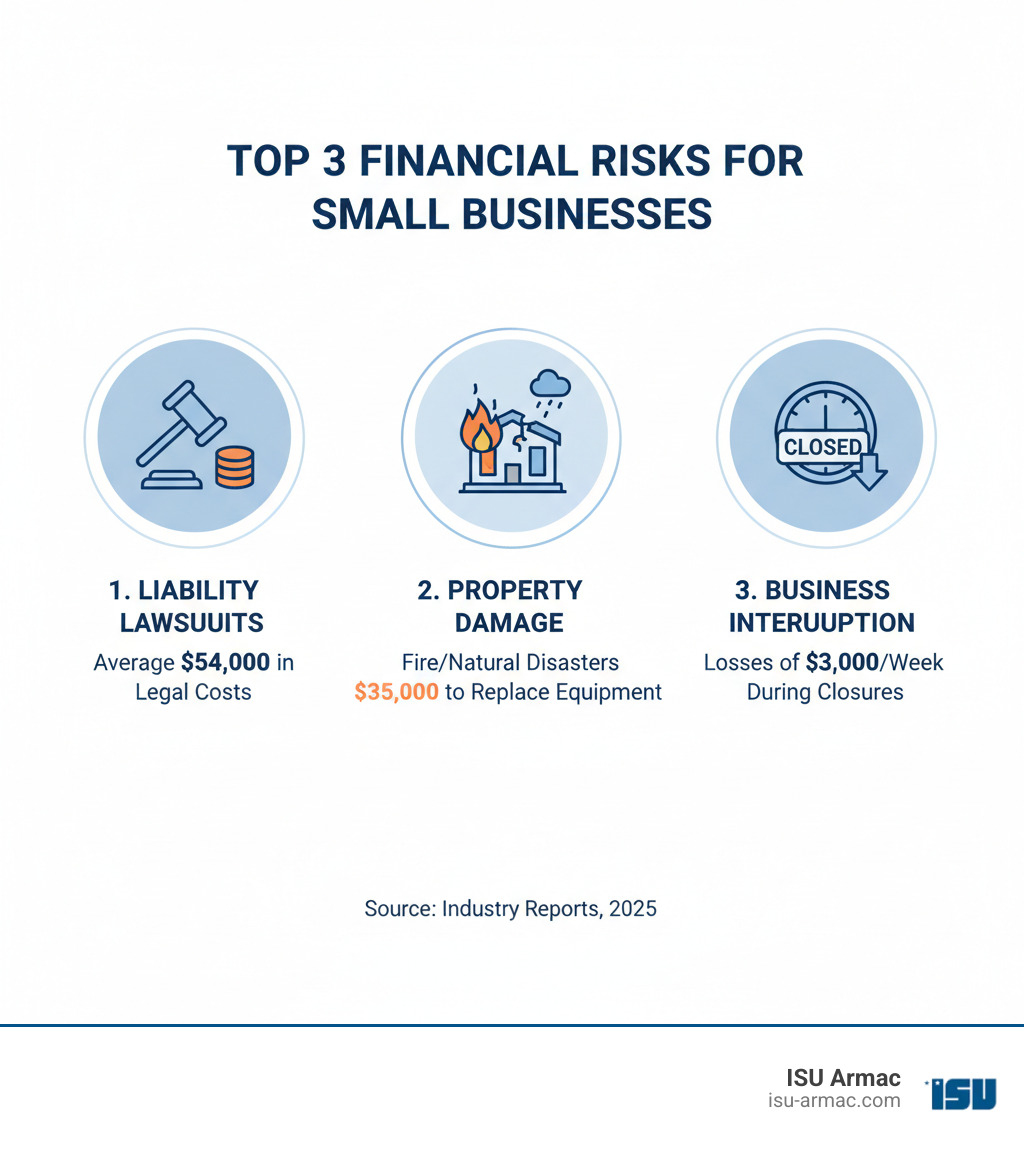
Business owners insurance is a foundational safety net that protects your company from unexpected financial losses due to accidents, lawsuits, property damage, and business interruptions. For small and mid-sized businesses, this coverage typically comes in the form of a Business Owner’s Policy (BOP), which bundles general liability, property, and business interruption insurance into one cost-effective package.
Key Benefits of Business Owners Insurance:
- Financial Protection – Covers legal fees, property damage, and third-party injury claims
- Business Continuity – Provides lost income and expense coverage during shutdowns
- Comprehensive Coverage – Combines multiple policies for convenience and savings
- Peace of Mind – Protects your personal assets from business-related liabilities
According to the National Federation of Independent Business, 30 percent of small business owners rank the cost and availability of liability insurance as their second most important insurance concern. Without proper coverage, a single lawsuit or disaster could drain your savings and force your business to close. A standard BOP typically costs around $450 per year for a $2 million general liability policy, making it an affordable investment for most small businesses.
I’m Ryan McEachron, Chief Executive Officer of ISU Insurance Services ARMAC Agency in Victorville, where I’ve helped countless local business owners secure the right business owners insurance to protect their operations and assets. With over two decades of experience in the insurance industry and deep roots in the High Desert community, I understand the unique risks facing businesses in Southern California and how to structure coverage that fits your specific needs and budget.
What is a Business Owner’s Policy (BOP)? The All-in-One Solution
Managing separate policies for general liability, property, and business interruption can be exhausting, with different renewal dates, premiums, and paperwork. A Business Owner’s Policy (BOP) was designed to solve this problem.
A BOP is a bundled insurance package for small to mid-sized businesses. It combines general liability, property, and business interruption coverage into one convenient, cost-effective policy. This bundled approach typically costs less than buying each policy individually, offering more value with less hassle.
For businesses in the High Desert, many insurers customize BOPs for specific industries. Whether you run a retail shop in Victorville, an office in Hesperia, or a manufacturing operation in Apple Valley, a BOP can be adjusted to your needs. This integrated approach also helps eliminate coverage gaps that can occur when using separate policies.
Think of a BOP as your business’s insurance foundation. It provides the core protections most small businesses need in one place, so you can spend less time managing policies and more time growing your company.
Here’s how a Business Owner’s Policy typically compares to purchasing standalone policies:
| Feature | Business Owner’s Policy (BOP) | Standalone Policies (e.g., GL, Property, BI) |
|---|---|---|
| Coverage | Bundles General Liability, Property, Business Interruption | Purchased individually, can be piecemeal |
| Cost | Often more cost-effective due to bundling | Can be more expensive when purchased separately |
| Convenience | One policy, one premium, simpler management | Multiple policies, multiple premiums, more administrative work |
| Eligibility | Designed for small to mid-sized businesses with lower risk | Suitable for businesses of all sizes, including high-risk ones |
| Customization | Customizable with endorsements for specific risks | Highly customizable for each type of risk |
The Core Components of a BOP
Every Business Owners Policy includes three essential coverage types that protect your business from common risks.
Commercial General Liability (CGL) Insurance is your first line of defense against third-party claims. For example, if a customer slips in your Victorville store, CGL can cover their medical bills and your legal defense. It also protects you if your business operations cause property damage to others. CGL handles claims for bodily injury, property damage, personal injury (like slander or libel), and advertising injury. It covers defense costs and any compensation you’re legally required to pay.
Commercial Property Insurance protects the physical assets that keep your business running, like your building, equipment, inventory, and furniture. It covers damage from perils like fire, theft, and vandalism. For instance, if a pipe bursts and floods your office, this insurance helps replace damaged items so you can get back to business. This coverage applies whether you own your building in Apple Valley or rent space in Oak Hills.
Business Interruption Insurance is a critical component that can be the difference between surviving a disaster and closing permanently. If a covered event like a fire forces you to shut down, this coverage replaces lost income. It also pays for ongoing expenses like rent, utilities, and payroll while you’re unable to operate. This ensures your bills get paid and your business survives until you can reopen.
What a Standard BOP Typically Excludes

While a Business Owner’s Policy provides solid foundational coverage, it doesn’t cover every possible risk. Understanding what’s not included is just as important as knowing what is.
Professional liability is a major exclusion. If your business provides professional advice or services (e.g., accountant, IT consultant), a BOP won’t cover claims of errors, bad advice, or failure to deliver on professional promises. These claims require a separate errors and omissions policy, which we’ll discuss later.
Commercial Auto Insurance is another key exclusion. If you use vehicles for business, you need a separate commercial auto policy. Your personal auto insurance won’t provide adequate protection for business use, and a BOP doesn’t cover vehicles. Commercial auto policies offer higher liability limits and can cover vehicles your business uses but doesn’t own.
Workers’ compensation is legally required in California for most businesses with employees but isn’t part of a standard BOP. It pays medical expenses and lost wages for employees injured or sick from their work. You must purchase this separately to avoid serious penalties.
Health insurance and disability insurance are employee benefits that fall outside the scope of business owners insurance. These need to be arranged separately as part of your employee benefits package or personal financial planning.
Businesses with high-risk exposures, like large manufacturing facilities or those handling hazardous materials, are often ineligible for a standard BOP. They typically need custom-built insurance programs. If your business falls into this category, we can design coverage that addresses your specific exposures.
Identifying these gaps is what we do at ISU Armac. We analyze your risk profile to ensure you don’t have dangerous holes in your coverage. This may involve adding specialized policies to your BOP or building a custom insurance program from scratch.
Beyond the BOP: Specialized Coverage for Complete Protection
While a Business Owner’s Policy forms a robust foundation, many businesses—especially as they grow or operate in specific industries—require additional, specialized coverage to truly protect themselves. Think of it like this: a BOP gives you a great pair of hiking boots, but if you’re climbing Mount Whitney, you’ll need specialized gear like ropes, harnesses, and an ice axe.

Here in Southern California, from the busy streets of Victorville to the quiet communities of Hesperia, businesses face a diverse array of risks. Some insurance types are legally required by state or federal law, while others are absolutely critical for mitigating high-hazard risks or protecting against professional liabilities. We help businesses in Apple Valley and Oak Hills steer these complexities to ensure they have comprehensive protection custom to their unique operations.
The reality is that certain exposures simply can’t be covered by a standard BOP. Professional services carry unique liability risks, employee injuries require specific coverage mandates, and the digital landscape has introduced entirely new threats that didn’t exist a decade ago. Understanding which specialized policies your business needs—and why—is essential for building a complete business owners insurance program. For a general overview of getting started with business insurance, you can always refer to the Get business insurance guide from the SBA, which outlines the fundamentals every business owner should know.
Legally Required Insurance: Workers’ Compensation
If your business has employees, this isn’t an option—it’s the law. Workers’ compensation insurance is mandated by nearly all U.S. states, including California, to protect both your employees and your business. It steps in when an employee suffers an injury or illness directly related to their job, whether that’s a slip and fall in your Oak Hills office or a more serious injury on a construction site in Hesperia.
Workers’ compensation covers an injured employee’s medical expenses, rehabilitation costs, and a portion of their lost wages while they recover. Without it, your business could be held fully liable for these costs, potentially leading to devastating financial consequences and crippling legal battles. The federal government also requires every business with employees to have workers’ compensation, unemployment, and disability insurance—making this one of the most fundamental protections you need to have in place from day one.
Beyond the legal requirement, workers’ compensation provides peace of mind for both you and your team. Your employees know they’ll be taken care of if something goes wrong, and you’re protected from potentially business-ending lawsuits. For more detailed information on this critical coverage and how it works in California, please visit our Workers Compensation Insurance page.
Professional Liability (Errors & Omissions)
For businesses that provide advice, services, or expertise, professional liability insurance—often known as Errors & Omissions (E&O) insurance—is non-negotiable. While your general liability policy covers bodily injury or property damage, it won’t cover claims arising from mistakes, negligence, errors, or omissions in the professional services you provide.
Consider a bookkeeping firm in Hesperia that’s sued for lost revenue because an employee failed to process critical invoices, leading to operational shutdowns for a client. Or imagine a management consulting firm in Victorville facing a lawsuit after a client alleges their advice led to significant financial losses. Even a graphic designer in Apple Valley could face a claim if a coding error in a client’s website causes major functionality issues and lost sales.
In these situations, E&O insurance protects your business by covering legal fees and any financial loss claims you might be liable for. This coverage is essential for consultants, accountants, real estate agents, IT professionals, marketing agencies, and any business where your expertise is your product. If clients rely on your professional judgment or advice-giving services, you need this protection. The cost of defending even a frivolous malpractice claim can easily reach tens of thousands of dollars—making E&O insurance an investment that often pays for itself after just one incident. To learn more about this vital coverage, explore our Errors and Omissions Insurance page.
Directors & Officers (D&O) and Cyber Liability
Beyond the day-to-day operations, businesses face risks from leadership decisions and the digital frontier—two areas that have become increasingly important in recent years.
Directors & Officers (D&O) Liability Insurance protects the personal assets of your directors and officers from lawsuits alleging wrongful acts in their capacity as managers. If you have a board of directors, officers, or even operate as a sole proprietor making significant management decisions, D&O insurance is crucial. These claims can arise from decisions related to employment practices like wrongful termination, regulatory non-compliance, or even mismanagement that leads to financial loss for stakeholders. Directors and officers can be held personally liable for financial and legal penalties, making D&O a critical layer of protection for those at the helm of your Southern California business.
Cyber Liability Insurance addresses the growing threat of cyber risks that affect businesses of all sizes. Small and mid-sized businesses in Oak Hills, Apple Valley, and across Southern California are increasingly prime targets for cyberattacks—often because hackers assume they have weaker defenses than larger corporations. Cyber liability insurance helps protect your business from the financial fallout of data breaches, hacking incidents, ransomware attacks, and other cyber extortion schemes.
The costs associated with a cyber incident can be staggering. You’ll need to notify affected customers, provide credit monitoring services, conduct forensic investigations to determine the cause and scope of the breach, and handle legal fees and regulatory fines. Business interruption due to system downtime can also cost thousands of dollars per day. A dedicated cyber liability policy can be a lifesaver when your digital defenses are breached. For a broader understanding of how various policies protect your business from liability exposures, refer to our Business Liability Insurance guide.
Choosing the Right Business Owners Insurance and Managing Costs
Finding the right business owners insurance doesn’t have to feel like wandering through the desert without water. With a clear strategy and the right partner, you can secure comprehensive coverage that protects your business without breaking the bank.
The journey starts with an honest risk assessment. Take a step back and really look at your business here in Southern California. What do your daily operations look like? Are you meeting clients face-to-face in Victorville, or shipping products from a warehouse in Hesperia? Do you have a team of employees, or are you flying solo for now? What equipment keeps your business running, and what would happen if it was damaged or stolen? Understanding these “what if” scenarios helps us determine not just what coverage you need, but how much.
Once we’ve mapped out your risks, it’s time to explore your options. This means comparing quotes from different carriers and looking beyond just the price tag. A policy that saves you a few hundred dollars upfront might cost you thousands if it doesn’t provide adequate coverage when you need it most. We examine policy limits (the maximum your insurer will pay for a claim), deductibles (what you’ll pay out-of-pocket before coverage kicks in), and the specific protections each policy offers. Getting a personalized Business Insurance Quote is the best way to see exactly what you’re getting for your investment.
Key Factors That Influence Your Insurance Costs
Your business owners insurance premium isn’t a random number – it’s based on specific characteristics of your business that insurers use to assess risk. When we work with clients throughout Apple Valley, Oak Hills, and beyond, we walk them through how these factors shape their costs.
Your industry type plays a major role. A roofing contractor faces different hazards than a freelance graphic designer, and premiums reflect that reality. Business size matters too, encompassing your revenue, number of employees, and the scale of your operations. A solo consultant naturally presents less risk than a company with twenty employees and multiple locations.
Your location in Southern California affects your rates in ways you might not expect. Insurers consider local crime statistics, proximity to fire stations, and exposure to natural disasters like wildfires or earthquakes. Even your building’s age and construction type can influence costs.
Your claims history tells insurers a lot about your risk profile. A clean record typically earns you better rates, while frequent claims signal higher risk. Similarly, your revenue and number of employees indicate your business’s exposure level and potential liability.
Finally, the coverage limits you choose and the deductibles you’re comfortable with directly impact your premium. Higher limits mean more protection but also higher costs, while accepting a higher deductible can lower your monthly or annual premium. We help you find the sweet spot that provides solid protection without unnecessary expense.
The Role of an Independent Insurance Advisor
In the maze of business owners insurance options, having someone in your corner makes all the difference. That’s where ISU Armac steps in. As independent insurance advisors, we work for you, not for any single insurance company. This distinction is crucial.
Our first priority is understanding your specific situation. We take time to learn about your business, identify your unique risks, and explain your coverage options in plain language. Because we’re independent, we can shop multiple carriers on your behalf, comparing not just prices but also the quality of coverage, claims service reputation, and policy terms. This means you get access to a broader marketplace without having to make dozens of phone calls yourself.
We customize your coverage by adding endorsements where needed and eliminating unnecessary extras that just inflate your premium. Whether you’re launching a new venture in Victorville or expanding an established business in Hesperia, we help you build a policy that grows with you. Our expert guidance ensures you understand exactly what you’re buying and why it matters.
At ISU Armac, we see ourselves as your long-term partner, not just someone who sells you a policy and disappears. We’re here when you have questions, when you need to file a claim, and when your business evolves and your coverage needs change. To learn more about our approach and commitment to our clients throughout Southern California, visit our About Us page.
Frequently Asked Questions about Business Insurance
We hear a lot of great questions from business owners across Southern California, from Victorville to Apple Valley and beyond. Here are some of the most common ones that might be on your mind, too:
What is the difference between General Liability and Professional Liability?
This is probably the question we get asked most often, and for good reason—it can be genuinely confusing! Think of it this way: General Liability insurance protects you when your business causes physical harm or damage to someone else’s property. It covers bodily injury (like when a customer slips on a wet floor in your store), property damage (like when your employee accidentally knocks over a client’s expensive vase), and even personal injury claims like slander or libel. Essentially, if something at your business location or related to your operations causes physical injury or property damage to a third party, general liability steps in to cover medical costs, legal fees, and settlements.
Professional Liability insurance, which you might also hear called Errors & Omissions (E&O) insurance, is a completely different animal. This coverage protects you when your professional advice, services, or expertise falls short and causes a client to suffer a financial loss. Maybe you’re a consultant whose recommendation led to a costly business decision, or an accountant who made an error on a tax return that resulted in penalties. Professional Liability covers the financial damages and legal costs associated with these kinds of claims—not physical injuries or property damage. For more detailed information about how general liability works, check out our General Liability Insurance Coverage page.
Do I need business insurance if I work from home?
This is a fantastic question, and the short answer is: absolutely, yes! It’s one of the most common misconceptions we encounter. Many home-based business owners assume their homeowner’s policy will cover their business activities, but unfortunately, that’s rarely the case. Your standard homeowner’s insurance policy offers extremely limited coverage for business property—often just $2,500 or so—and typically excludes business-related liability claims altogether.
Let’s say a client comes to your home office for a meeting and trips on your front step, injuring themselves. Your homeowner’s policy likely won’t cover that claim because it happened during a business activity. Or imagine your laptop, printer, and inventory get stolen during a break-in. Again, your homeowner’s policy will provide minimal coverage, if any, for business equipment and inventory. To truly protect yourself, you need a separate business owners insurance policy or a specific business endorsement added to your homeowner’s policy. This ensures your business assets are properly covered and you’re protected from business-related liability claims that could otherwise devastate your personal finances.
How much does business owners insurance cost for a small business?
Ah, the million-dollar question—or, more accurately, the few-hundred-dollar question! The truth is, the cost of business owners insurance varies quite a bit depending on your unique situation. For a basic general liability policy, many small businesses can expect to start around $450 per year for $2 million in coverage. That’s often surprisingly affordable for the peace of mind it provides.
However, your final cost depends on multiple factors: your industry (a restaurant faces different risks than a graphic design studio), your business size, your location here in Southern California, your claims history, how many employees you have, and the coverage limits and deductibles you select. A higher-risk business or one with more employees and physical assets will naturally have higher premiums. That’s why we work closely with each client to understand their specific needs and shop multiple carriers to find the most competitive rates. For a deeper dive into what you might expect to pay, take a look at our guides on How Much Does Insurance Cost for a Small Business and Business Insurance Cost. We’re always happy to provide a personalized quote based on your actual business operations and risk profile.
Conclusion: Invest in Your Business’s Future and Security
Running a business in Southern California—whether you’re in Apple Valley, Victorville, Hesperia, or Oak Hills—means facing challenges you can’t always predict. A sudden lawsuit, unexpected property damage, or even a cyberattack can shake the foundation of everything you’ve built. That’s precisely why business owners insurance isn’t just another expense on your balance sheet; it’s the safety net that keeps your dreams from solveing when the unexpected happens.
Throughout this guide, we’ve explored how a Business Owner’s Policy provides comprehensive, cost-effective protection by bundling general liability, property, and business interruption coverage into one convenient package. We’ve also discussed the importance of specialized coverages—from workers’ compensation to professional liability to cyber insurance—that address the unique risks your business faces. The right insurance strategy isn’t about buying the most expensive policy; it’s about understanding your specific exposures and building custom coverage that truly protects what matters most.
Proactive protection today means business continuity tomorrow. When you invest in proper business owners insurance, you’re not just protecting your physical assets and finances. You’re safeguarding your employees’ livelihoods, your customers’ trust, and your own peace of mind. You’re ensuring that a single unfortunate event doesn’t derail years of hard work and dedication.
At ISU Armac, we understand that every business in the High Desert region is unique, with its own set of challenges and opportunities. That’s why we don’t believe in cookie-cutter solutions. We take the time to understand your operations, assess your risks, and shop multiple carriers to find the best coverage at the most competitive rates. Our goal is to be your trusted partner, providing expert guidance every step of the way.
Don’t wait until disaster strikes to find gaps in your coverage. We invite you to Contact us today for a personalized consultation and get a comprehensive review of your business insurance cost. Let’s work together to build a protection plan that gives you the confidence to focus on growing your business, knowing you’re prepared for whatever comes your way.