
Why Bike Insurance California is Essential for Every Rider
Bike insurance California is a legal requirement and financial necessity for the 936,809 registered motorcycle riders across the state. Whether you’re cruising the Pacific Coast Highway or navigating Los Angeles streets, California law mandates that you carry minimum liability coverage of $30,000 per person for bodily injury, $60,000 per accident, and $15,000 for property damage. Beyond legal compliance, proper motorcycle insurance protects you from potentially devastating financial losses if you’re involved in an accident.
Quick Answer: California Motorcycle Insurance Requirements
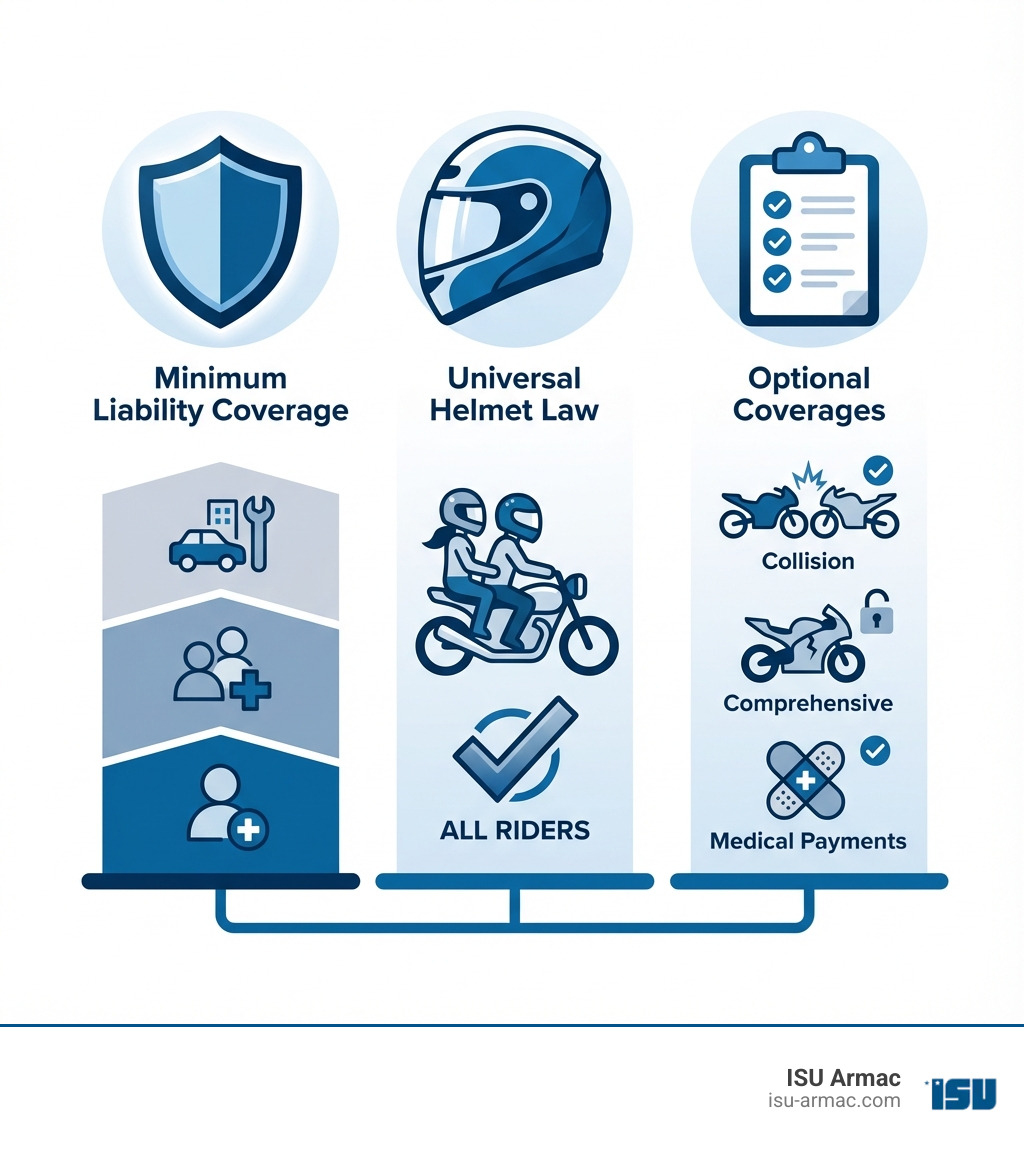
- Minimum Liability Coverage: $30,000/$60,000/$15,000 (bodily injury per person/per accident, property damage)
- Uninsured/Underinsured Motorist Coverage: Required (but can be rejected with signed form)
- Proof of Insurance: Must be provided for DMV registration
- Helmet Law: Universal requirement for all riders and passengers
- Penalties Without Insurance: Fines, license suspension, vehicle impoundment, and inability to claim damages
California is home to more registered motorcycles than any other state in the U.S., making it crucial for riders to understand their coverage options. The state’s unique laws—including legal lane splitting and universal helmet requirements—create specific insurance considerations that every motorcyclist needs to address.
Riding without proper coverage can result in serious consequences beyond just fines. If you’re caught without insurance, you may face license suspension for up to a year, have your motorcycle impounded, and lose your right to recover non-economic damages (pain and suffering) if you’re injured in an accident—even if the other driver was at fault.
I’m Ryan McEachron, CEO of ISU Insurance Services ARMAC Agency in Victorville, and I’ve helped countless High Desert residents steer the complexities of bike insurance California requirements while finding affordable coverage that truly protects their investment. With over two decades of experience in the insurance industry serving California communities, I understand the unique challenges motorcyclists face when securing the right protection for their rides.
Bike insurance california glossary:
- Motorcycle insurance for Harley Davidson
- Motorcycle insurance for beginners
- California minimum motorcycle insurance
California’s Mandatory Motorcycle Insurance Requirements
When we hit the open road in California, whether it’s through the scenic routes of Apple Valley or the busy streets of Victorville, ensuring we’re properly insured isn’t just a good idea—it’s the law. The Golden State requires all registered vehicles, including motorcycles, to have insurance. This isn’t just about protecting our own bikes; it’s about safeguarding ourselves and others from the financial fallout of an unexpected accident.

Understanding the 30/60/15 Minimum Liability Rule
California’s financial responsibility law dictates the bare minimum we must carry to legally operate our motorcycles. This is often referred to as the “30/60/15” rule, and it breaks down like this:
- Bodily Injury Liability ($30,000 per person): This coverage pays for medical expenses, lost wages, and pain and suffering for one person injured in an accident where you are at fault. Think of it as protecting your assets if you accidentally cause injury to another rider, pedestrian, or vehicle occupant.
- Bodily Injury Liability ($60,000 per accident): This is the maximum amount your insurance will pay for all injuries sustained in a single accident you cause, regardless of how many people are hurt. So, if multiple people are injured, this $60,000 limit would be shared among them.
- Property Damage Liability ($15,000 per accident): This covers the cost of damage to another person’s property, such as their vehicle, motorcycle, fence, or other belongings, if you are found responsible for the accident.
These minimums are the foundation of any bike insurance California policy. While they fulfill the legal requirement, we often advise our clients in Hesperia and Oak Hills to consider higher limits. Why? Because the actual costs of medical care and property repair after a serious accident can easily exceed these minimums, leaving us personally responsible for the difference. For more detailed information, you can always check out our guide on California minimum motorcycle insurance or visit the Official CA Insurance Requirements directly.
Uninsured/Underinsured Motorist (UM/UIM) Coverage
Here’s a crucial aspect of bike insurance California that often surprises riders: California mandates that insurance providers offer uninsured/underinsured motorist bodily injury (UMBI) coverage. While it’s offered, you technically have the option to reject or lower these coverages, but only with the submission of a signed form.
So, what does this mean for us, the riders?
- Uninsured Motorist (UM) coverage steps in when an at-fault driver has no insurance. Imagine you’re hit by another vehicle, and the driver flees or simply has no coverage. UM coverage would help cover your medical bills and potentially lost wages.
- Underinsured Motorist (UIM) coverage comes into play when an at-fault driver has insurance, but their limits aren’t high enough to cover all your damages. Your UIM coverage would then pay the difference up to your policy’s limits.
Given the potential for high medical costs and the unfortunate reality that some drivers are uninsured, we strongly recommend accepting UM/UIM coverage. It’s a vital layer of protection for you and your passengers, ensuring that even if the other party can’t pay, you’re not left footing the bill alone. It truly protects us when others fail to protect themselves.
Penalties for Riding Without Insurance
Riding without proper bike insurance California is a gamble with severe consequences. If you’re caught without proof of financial responsibility, you could face:
- Fines: These can be substantial and increase with subsequent offenses.
- License Suspension: Your motorcycle license could be suspended for a year, significantly impacting your ability to ride legally.
- Motorcycle Impoundment: Your beloved bike could be impounded, leading to towing and storage fees on top of everything else.
- SR-22 Certificate: You might be required to obtain an SR-22 certificate, which is a document your insurance company files with the DMV proving you have insurance. This often results in higher insurance premiums for several years.
- Inability to Claim Non-Economic Damages: This is one of the most painful penalties. If you’re involved in an accident and don’t have insurance, even if you’re not at fault, California law may prevent you from recovering “pain and suffering” damages. You could still claim economic damages (medical bills, lost wages), but the non-economic aspect, which can be significant, would be off-limits.
Riding uninsured means risking not only your financial stability but also your legal right to ride. It’s a risk simply not worth taking.
Beyond the Basics: Optional Coverages for Full Protection
While meeting California’s minimum liability requirements is essential for legal riding, truly protecting your investment and your peace of mind often means going beyond the basics. Think of it like this: the minimum covers the other guy; optional coverages cover you and your prized possession.
What is the Difference Between Liability, Comprehensive, and Collision?
These three terms are the bedrock of most insurance policies, and understanding their distinctions is key to building a robust bike insurance California plan:
- Liability Coverage: As we discussed, this is the mandatory minimum. It covers damages you cause to other people and their property if you’re at fault in an accident. It does not cover your own injuries or damage to your motorcycle.
- Collision Coverage: This is where your own bike gets protection in an accident. Collision coverage pays for repairs or replacement of your motorcycle if it’s damaged in a collision with another vehicle or object (like a guardrail or tree), regardless of who is at fault. If you’re financing your motorcycle, your lender will almost certainly require this coverage, as they want to protect their investment.
- Comprehensive Coverage: Often misunderstood, comprehensive coverage protects your motorcycle from non-collision-related incidents. This includes events like theft, vandalism, fire, natural disasters (hail, floods), and even damage from striking an animal. If you live in an area with high theft rates, or if you simply want protection against the unpredictable, comprehensive coverage is a must.
Together, collision and comprehensive coverage are often referred to as “full coverage,” offering a much broader shield for your motorcycle. To dive deeper into what this means for your ride, check out our guide on full-coverage-motorcycle-insurance-california.
Valuable Add-Ons for Your Policy
Beyond the core coverages, several optional add-ons can tailor your bike insurance California policy to your specific needs, providing extra layers of protection for those unforeseen moments.
- Medical Payments (MedPay): This coverage helps pay for medical expenses for you and any passengers, regardless of fault, if you’re injured in a motorcycle accident. It can cover ambulance fees, hospital stays, and doctor visits, acting as a quick source of funds for immediate care. Some policies may offer “Improved Injury Protection” which could pay up to $250 a week for two years if you’re unable to work due to crash injuries.
- Accessory & Custom Parts Coverage: Many riders personalize their motorcycles with custom paint, chrome, upgraded exhausts, or specialized seating. Standard policies might only cover factory-installed parts. This add-on ensures that your investment in aftermarket accessories and custom modifications is protected in case of damage or theft. This is particularly relevant for riders who take pride in their unique machines, like those who customize their Harleys. Find out more about protecting your specific ride with our motorcycle-insurance-for-harley-davidson page.
- Roadside Assistance: A flat tire in the middle of a desert highway in Victorville or a breakdown far from home in Hesperia can ruin a ride. Roadside assistance coverage can be a lifesaver, providing services like towing to the nearest repair shop, battery jump-starts, fuel delivery, and tire changes. It’s designed for those fundamental issues that can leave you stranded.
- Total Loss Coverage: For newer motorcycles, typically those no more than one model year old on a new policy, total loss coverage (also known as “new bike replacement”) can be invaluable. If your motorcycle is declared a total loss after a covered incident, this coverage will pay to replace it with a brand-new model, rather than just its depreciated actual cash value.
These add-ons provide a robust safety net, allowing you to ride through Southern California’s diverse landscapes with greater confidence, knowing you’re well-prepared for almost anything the road throws your way.
The Cost of Bike Insurance California: What to Expect
“How much does motorcycle insurance cost?” is one of the most common questions we hear from riders across Apple Valley, Oak Hills, and beyond. The answer, unfortunately, is rarely a simple number. While we can provide averages, your individual premium for bike insurance California will be unique, influenced by a multitude of factors.

How Much Does Motorcycle Insurance Typically Cost?
Let’s start with a benchmark. According to recent data from 2023, the annual cost for a liability-only motorcycle insurance policy in California was approximately $195.70. That’s a great starting point for understanding the minimum expense.
However, if you’re looking for comprehensive and collision coverage—what we often refer to as “full coverage”—your costs will naturally be higher. While exact figures vary widely, full coverage could range from several hundred to over a thousand dollars annually, depending on your specific circumstances.
Why such a wide range? Because insurance rates are highly personalized. They reflect the perceived risk you represent to an insurer. Factors like your age, driving history, the type of bike you ride, and even where you live (your ZIP code) all play a significant role. For a deeper dive into these figures, you can explore our page on the average-cost-of-motorcycle-insurance-in-california.
Factors That Determine Your Premium
When an insurance company calculates your premium for bike insurance California, they consider a mosaic of information to assess risk. Here are the primary factors that influence your motorcycle insurance cost:
- Rider Age & Experience: Younger, less experienced riders (especially those under 25) typically pay more due to a higher statistical likelihood of accidents. As you gain more years of riding experience and maintain a clean record, your rates tend to decrease.
- Driving Record: This is a big one. A history of traffic violations (speeding tickets, reckless driving) or at-fault accidents will significantly increase your premiums. Conversely, a clean driving record is your best friend when it comes to affordable insurance.
- Location (ZIP Code): Where you live and often ride matters. Urban areas like parts of Los Angeles or San Bernardino County, with higher traffic density, theft rates, and vandalism, usually have higher insurance costs than more rural areas like Oak Hills or parts of Apple Valley.
- Motorcycle Type & Engine Size: The bike itself is a major factor.
- Sport bikes (especially high-performance models) often have the highest premiums due to their power, higher accident rates, and greater repair costs.
- Cruisers and touring bikes generally fall in the mid-range.
- Standard bikes and mopeds/scooters typically have the lowest rates.
The larger the engine (CCs), the more powerful the bike, and often the higher the premium.
- Coverage Choices: The more coverage you choose (e.g., adding comprehensive, collision, MedPay, accessory coverage), the higher your premium will be. This is a trade-off between protection and cost.
- Deductible Amount: Your deductible is the amount you pay out-of-pocket before your insurance kicks in for a covered claim. Choosing a higher deductible typically lowers your premium, but means you’ll pay more upfront if you have a claim. A lower deductible means higher premiums but less out-of-pocket during a claim.
Understanding these factors empowers you to make informed decisions about your coverage and potentially find ways to lower your costs. For those facing higher premiums, perhaps due to past incidents, we also offer insights on motorcycle-insurance-for-high-risk-drivers.
How to Save Money and Ride Legally in California
Getting on the road in California legally and affordably means knowing how to leverage discounts and adhere to state-specific laws. We believe every rider in Victorville, Hesperia, and across Southern California deserves the best possible rate without compromising on essential protection.
Discounts Available for Your Bike Insurance California Policy
Insurance companies love responsible riders, and they often reward them with discounts. When we help you shop for bike insurance California, we always look for these money-saving opportunities:
- Multi-Policy Bundle: One of the easiest ways to save. If you bundle your motorcycle insurance with another policy, like your auto insurance or homeowners insurance, you can often receive a significant discount. This simplifies your insurance management, too!
- Safety Course Completion (MSF): Completing an approved motorcycle safety course, such as those offered by the Motorcycle Safety Foundation (MSF) or the California Motorcyclist Safety Program (CMSP), can lead to a discount of up to 6%. Not only does it make you a safer rider, but it also saves you money. This is especially beneficial for motorcycle-insurance-for-beginners.
- Good Driver Discount: Maintain a clean driving record with no at-fault accidents or major violations for a certain period (often 3 years), and you could qualify for a good driver discount, sometimes up to 20%.
- Multi-Motorcycle Discount: If you’re fortunate enough to own more than one motorcycle, insuring them all with the same carrier can earn you a discount, sometimes up to 12%.
- Mature Rider Discount: Experienced riders, typically those over a certain age (e.g., 55 or 60), often qualify for discounts, recognizing their years of safe riding.
- Association Memberships: Belonging to certain motorcycle clubs or associations, like the Harley-Davidson Owner’s Group (H.O.G.), can sometimes make you eligible for specific discounts.
- Anti-Theft Device Discount: Installing approved anti-theft devices on your motorcycle can also lead to a small reduction in your comprehensive coverage premium.
Always ask about available discounts when getting a quote. You might be surprised by how much you can save! For more tips on finding economical coverage, check out our insights on affordable-motorcycle-insurance.
Key Motorcycle Laws You Must Know
California has some unique and crucial laws that every motorcyclist must be aware of, not just for safety but also for staying on the right side of the law:
- Universal Helmet Law (DOT-Compliant): This is non-negotiable. California has a universal helmet law, meaning all motorcycle operators and passengers are required to wear a U.S. DOT-compliant helmet at all times while riding. This applies regardless of age or experience. No excuses, no exceptions—your brain bucket is your best friend.
- Lane Splitting Guidelines (AB 51): California is famous for being one of the few states where lane splitting is legal. However, it’s not a free-for-all. While specific speed limits for lane splitting were removed with AB 51, the California Highway Patrol (CHP) advises best practices, including not splitting lanes when traffic is moving faster than 30 mph, and exercising extreme caution. It’s about safety and common sense, not just legality.
- Rider Training for Under 21s: If you’re under 21 and looking to get your motorcycle permit, you must complete a motorcycle rider training course approved by the California Motorcyclist Safety Program. This ensures new, young riders get proper instruction before hitting the busy California roads.
Understanding and adhering to these laws is paramount. Not only does it keep you safer, but it also helps maintain a clean record, which, as we’ve seen, can positively impact your bike insurance California premiums. For a comprehensive overview of all regulations, we encourage you to consult the California Motorcycle Handbook.
Finding and Securing Your California Motorcycle Insurance Quote
Navigating insurance can feel like a maze, but getting a quote for your bike insurance California doesn’t have to be complicated. Our goal is to make the process as straightforward and transparent as possible, ensuring you get the coverage you need at a price you’ll appreciate.
The Process of Getting a Quote
When you’re ready to explore your options for motorcycle insurance, here’s what the process generally looks like:
- Gathering Information: We’ll need some key details about you and your motorcycle. This typically includes your driver’s license information, riding history, the year, make, model, and Vehicle Identification Number (VIN) of your motorcycle. If you’ve made any significant modifications or added custom parts, it’s good to have that information handy too.
- Assessing Coverage Needs: This is where we discuss your riding habits, financial situation, and risk tolerance. Are you a weekend warrior or a daily commuter? Do you have a newer, expensive bike that needs full protection, or an older model where liability might suffice? We’ll help you understand the various coverage options and their implications.
- Comparing Offers: Once we have a clear picture, we get to work. As an independent agency, our strength lies in our ability to shop multiple top-rated insurance carriers on your behalf. This means we don’t just offer you one option; we compare policies from several providers to find the best blend of coverage and cost for your specific needs.
Getting a quote is the first step towards securing your ride and your peace of mind. For more insights into this process, visit our california-motorcycle-insurance-quote page.
The Advantage of Using an Independent Insurance Agent
It might seem easy to get an online quote, and while that’s a good starting point, it often doesn’t tell the whole story. This is where the advantage of working with an independent insurance agent, like us at ISU Armac, truly shines for your bike insurance California needs.
- Access to Multiple Carriers: Unlike captive agents who can only sell policies from one company, we work with a wide network of insurance providers. This means we can literally shop around for you, comparing rates and coverage options from various insurers to find the policy that best fits your unique profile and budget. It’s like having multiple quotes delivered to you, without all the individual effort.
- Unbiased Advice: Our loyalty is to you, not a single insurance company. We provide objective advice, explaining the pros and cons of different policies and coverages, ensuring you make an informed decision based on your needs, not a sales quota.
- Personalized Service: We take the time to understand your specific circumstances, your riding style, and your concerns. Whether you’re in Victorville, Apple Valley, or anywhere in Southern California, we offer personalized attention that an online form simply can’t match. We can help you steer complex situations, like insuring a custom bike or understanding specific state regulations.
- Finding the Best Rates: By comparing options from various carriers and identifying all eligible discounts, we often find our clients better coverage at a more competitive price than they might find on their own. We know the market, and we know how to leverage it for your benefit.
When you’re searching for a trusted partner to help with your insurance needs, think of us as your local experts, much like finding a reliable car-insurance-broker-near-me. We’re here to guide you through the process and ensure your ride is well-protected.
Conclusion: Ride with Confidence in the Golden State
Riding a motorcycle in California is an unparalleled experience, offering freedom, adventure, and breathtaking scenery. But with that freedom comes responsibility—the responsibility to protect yourself, your passengers, and your investment with comprehensive bike insurance California.
We’ve covered the essentials: from the mandatory 30/60/15 liability minimums that keep you legal, to the critical role of uninsured/underinsured motorist coverage in safeguarding your financial future. We’ve explored the differences between liability, comprehensive, and collision coverage, and highlighted valuable add-ons like medical payments and accessory coverage that provide a robust safety net. Understanding how factors like your riding history and bike type influence costs, and knowing which discounts to pursue, empowers you to secure affordable yet effective protection. Lastly, we’ve emphasized the importance of adhering to California’s unique motorcycle laws, including the universal helmet law and lane splitting guidelines.
At ISU Armac, we understand the unique needs of California motorcyclists. We’re dedicated to helping riders in Victorville, Hesperia, Apple Valley, Oak Hills, and across Southern California find the perfect balance of coverage and cost. Our expertise allows us to steer the complexities of the insurance market, ensuring you ride with confidence, knowing you’re fully protected.
Don’t let the open road become a path to financial uncertainty. Let us help you secure the right bike insurance California policy that fits your lifestyle and budget. Contact us for a comprehensive motorcycle insurance review today, and let’s get you covered so you can focus on what truly matters: the ride.