
Why Affordable Commercial Auto Insurance Is Essential for Your Business
Affordable commercial auto insurance protects your business vehicles and drivers without draining your budget. Here are your best options for cost-effective coverage:
Top Ways to Find Affordable Commercial Auto Insurance:
- Compare quotes from multiple carriers to save 20% or more.
- Increase deductibles to lower monthly premiums.
- Bundle policies for automatic discounts of up to 10%.
- Maintain clean driving records for all business drivers.
- Choose appropriate coverage limits—not too little, not too much.
- Ask about discounts for safety features, driver training, or professional associations.
If your business uses vehicles for deliveries, transporting equipment, or driving to job sites, you’re legally required to carry commercial auto insurance in most states. The good news is you don’t have to break the bank to get proper protection.
The reality is stark: approximately one in eight drivers is uninsured, making adequate coverage even more critical. With quotes typically ranging from $1,200 to $2,400 per vehicle per year, finding the right balance between cost and coverage is crucial.
I’m Ryan McEachron, CEO of ISU Insurance Services ARMAC Agency in Victorville. I’ve helped countless High Desert businesses find affordable commercial auto insurance that fits their budget and protects their operations. My experience on the Victorville City Council and with local business organizations has given me deep insight into what small businesses need most—comprehensive protection that won’t compromise their bottom line.
Explore more about affordable commercial auto insurance:
- commercial auto insurance quote online
- how does commercial auto insurance work
- what does commercial auto insurance cover
Understanding Commercial Auto Insurance Essentials
Imagine a car accident on the way to a job site in Barstow. The other driver is hurt, your work truck is totaled, and you’re facing thousands in medical and replacement costs. Without affordable commercial auto insurance, this scenario could bankrupt your business. Commercial auto insurance is a financial lifeline, providing a protective shield around everything you’ve built. When accidents happen, proper coverage lets you focus on getting back to work instead of figuring out how to pay massive bills.
The stakes are high for businesses. A single accident can trigger lawsuits with legal fees reaching tens of thousands of dollars. Your commercial policy covers immediate damage and provides legal defense, protecting your business assets from being seized to pay judgments. Every business owner in the High Desert knows that operating without insurance is a huge risk.
Who Needs Commercial Auto Insurance?
If you use a vehicle to make money, you need commercial coverage. Your personal car insurance won’t protect you during business activities, leaving you exposed to financial ruin.
- Transporting Goods or People: If you carry tools, deliver products, or transport clients, your vehicle is a core part of your business operations. Personal policies specifically exclude this type of use.
- Driving Between Job Sites: Contractors, electricians, landscapers, and other professionals who travel between locations are using their vehicles for commercial purposes.
- Employees Driving: If employees use company vehicles or their own cars for work tasks, your business is liable. Hired and non-owned auto coverage is crucial in these situations.
- Gig Work: Rideshare and food delivery drivers operate commercial vehicles the moment they turn on their app. Personal policies will deny claims that occur while working.
For LLC owners, understanding how vehicle coverage fits into your overall protection strategy is essential. Check out our guide on Business Insurance for LLC to see how commercial auto integrates with other coverages. And if you’re wondering about using your commercial vehicle for weekend errands, our article Does Commercial Auto Insurance Cover Personal Use? has the answers.
Personal vs. Commercial Auto Insurance
Many business owners ask if they can just use their personal car insurance. The reality is that using personal insurance for business is like bringing a butter knife to a gunfight—you’re severely underprotected.
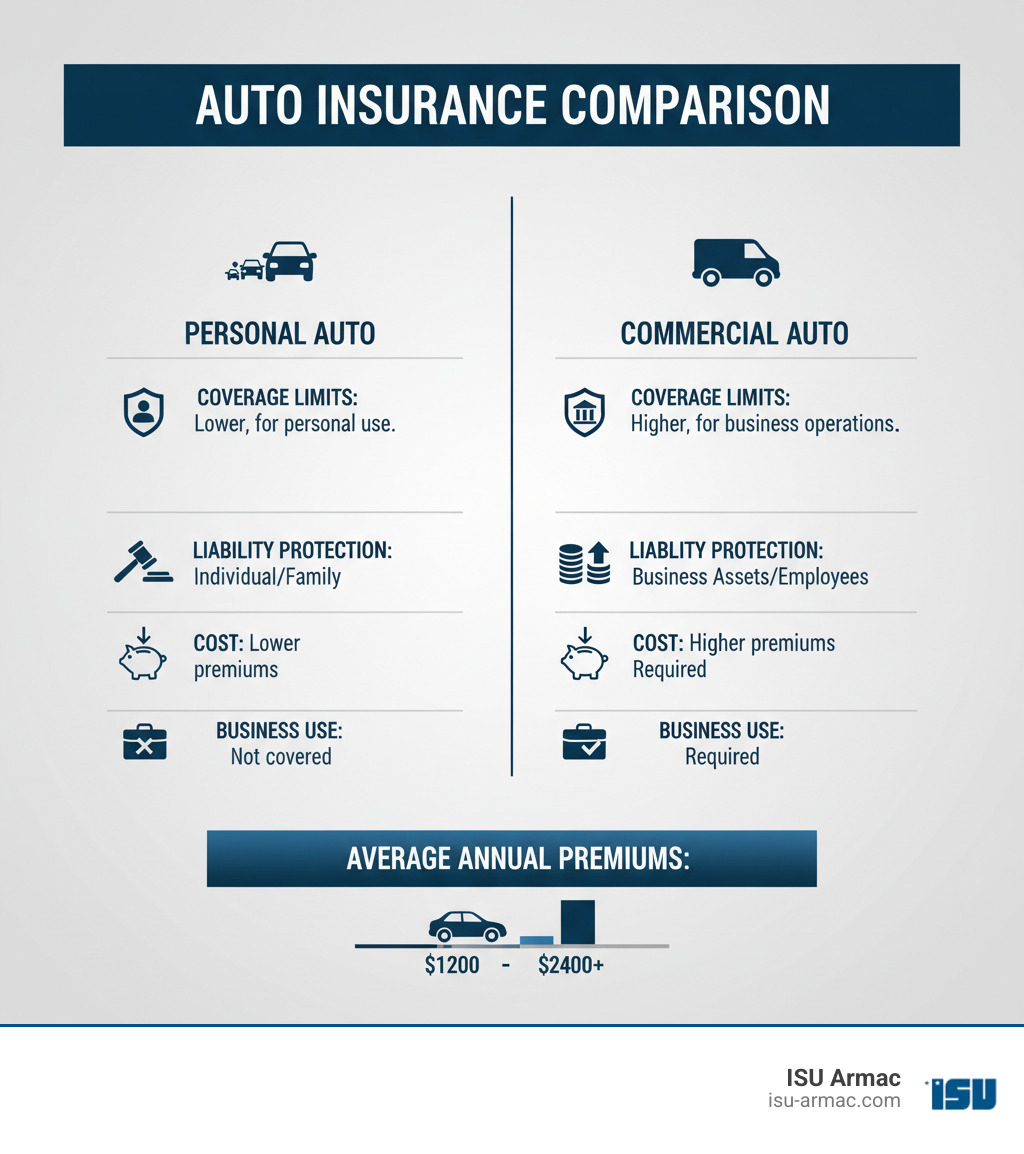
- Coverage Limits: Personal policies might offer $100,000 in liability coverage, while commercial policies typically start at $500,000 and often go up to $1,000,000 or more. This reflects that business-related accidents often result in much larger claims.
- Liability Protection: Commercial policies are designed for complex business-related accidents, covering lost wages for injured parties, ongoing medical treatment, and extensive legal defense costs.
- Covered Drivers: Commercial policies can extend protection to employees and temporary workers, even when they drive their own vehicles for company business (with the right endorsements).
- Business Use Exclusion: Nearly every personal auto policy contains a clause that excludes coverage for accidents that occur during commercial activities.
- Cost Differences: Commercial auto insurance costs more because the risks are higher—business vehicles log more miles, carry heavier loads, and operate in busier areas. However, the cost is a smart investment compared to the financial devastation of an uninsured accident.
Affordable commercial auto insurance is achievable. By understanding your risks and working with an agency that shops multiple carriers, you can find protection that fits your budget. For a deeper dive, our guide Navigating Business Auto Insurance: A Comprehensive Comparison Guide walks you through every consideration.
What Your Policy Covers: Vehicles, Liability, and Legal Minimums

Understanding your commercial auto policy is key to finding real value, not just a low price. Your policy combines several types of protection—some required by law, others optional but highly recommended. The goal is to find the right balance for your business needs and budget.
For a deeper dive into coverage details, check out our guide on What Does Commercial Auto Insurance Cover?. We also have specific information about Commercial Vehicle Insurance that covers different vehicle types.
Key Coverage Options
Every policy is built from these essential coverages:
- Bodily Injury Liability: Covers medical bills, lost wages, and legal costs if your business vehicle injures someone. This is crucial for protecting your business from devastating lawsuits.
- Property Damage Liability: Pays for repairs or replacement of someone else’s property (like their car or a building) that your vehicle damages.
- Collision Coverage: Pays to repair or replace your business vehicle if it’s damaged in a collision, regardless of who is at fault. This is vital for minimizing downtime and lost income.
- Comprehensive Coverage: Protects your vehicle from non-collision events like theft, vandalism, fire, hail, or hitting an animal.
- Uninsured/Underinsured Motorist: Covers your costs when the at-fault driver has little or no insurance. With about one in eight drivers uninsured, this is critical protection.
- Hired and Non-Owned Auto Coverage: Provides liability protection when you or your employees use rented vehicles or personal cars for business errands.
State and Federal Requirements
Every state has minimum insurance requirements, but what’s legal isn’t always what’s smart for your business.
California requires minimums of $15,000 for injury to one person, $30,000 for multiple people, and just $5,000 for property damage. These limits are dangerously low given today’s medical and repair costs.
In contrast, states like New York have higher minimums, but even those are often insufficient for commercial operations. Insurance carriers typically recommend at least $500,000 in coverage, with $1 million being the standard for adequate protection. Commercial vehicles can cause more severe accidents, and higher limits are necessary to protect your business assets.
If your business operates across state lines, you must meet federal insurance requirements, which are much stricter and often require $750,000 or more in coverage. You can find details at the Federal insurance requirements website.
The bottom line: meeting legal minimums is just the start. We help clients find affordable commercial auto insurance with limits that provide real-world protection.
Decoding the Cost of Commercial Auto Insurance

Commercial auto insurance pricing can seem complex, but it’s based on a formula that assesses your business’s specific risks. Understanding this formula helps you make smarter choices to find truly affordable commercial auto insurance. Many of these factors are within your control, giving you the power to influence your costs.
We break down all the details in our guide about the Cost of Commercial Auto Insurance, but here’s what you need to know now.
What Factors Influence Your Premium?
Insurers evaluate five key risk factors to determine your premium:
- Industry Risk: Your line of work is a major factor. A construction company hauling heavy equipment will pay more than a real estate agent. Industries like construction and delivery have higher accident rates, which is reflected in their premiums.
- Vehicle Type and Use: A heavy-duty truck costs more to insure than a small sedan. How you use the vehicle also matters—a delivery van making frequent stops poses a higher risk than a consultant’s car driven to occasional meetings.
- Driving Records: Insurers review the motor vehicle records (MVR) of all drivers. A clean driving record is one of the best ways to secure lower rates, while accidents or tickets can increase your premium significantly.
- Business Location: Operating in a dense urban area like San Bernardino will likely cost more than in a rural town like Apple Valley due to higher rates of traffic, accidents, and theft.
- Claims History: A history of frequent claims signals higher risk to insurers. Conversely, a clean claims history can earn you significant discounts.
How Policy Choices Affect Your Price
The choices you make when building your policy directly impact your premium:
- Coverage Limits: Opting for higher liability limits (e.g., $1 million) costs more upfront but provides crucial protection for your business assets. State minimums are cheaper but leave you dangerously exposed.
- Deductible Amounts: Choosing a higher deductible (e.g., $1,000 instead of $500) will lower your monthly premium. Just ensure you can comfortably pay this amount out-of-pocket if you file a claim.
- Number of Vehicles: While more vehicles increase your total cost, many insurers offer multi-vehicle discounts, making the per-vehicle cost lower as your fleet grows.
- Annual Mileage: Be realistic about your mileage. Lower annual mileage often translates directly to lower premiums, so don’t pay for coverage you don’t need.
Finding affordable commercial auto insurance is about balancing cost and protection, not just picking the cheapest options.
Your Guide to Finding Affordable Commercial Auto Insurance

You don’t have to overpay for insurance, but you can’t afford to skimp on coverage. The good news is that finding affordable commercial auto insurance is possible when you shop smart. Too many business owners in the High Desert grab the first quote they see, potentially missing out on hundreds in savings.
Strategies for Finding Affordable Commercial Auto Insurance
- Comparison Shop: This is your most powerful tool. Prices can vary by 20% or more between carriers for the same coverage. Don’t settle for the first offer.
- Adjust Your Deductibles: Increasing your deductible from $500 to $1,000 can noticeably lower your premiums. Just be sure you can cover the higher out-of-pocket cost.
- Review Coverage Annually: Your business needs change over time. An annual review ensures you’re not paying for coverage you no longer need and allows you to benefit from an improved driving record.
- Maintain Clean Driving Records: A safe driving culture is the best long-term strategy for lower rates. Accidents and even minor violations can significantly increase your premium.
The easiest way to get started is with our Commercial Auto Insurance Quote Online tool, which lets you see what you’ll pay without any pressure.
Discounts That Make Commercial Auto Insurance More Affordable
Insurers offer many discounts, but you often have to ask for them.
- Bundling Policies: Combining your commercial auto, general liability, and property insurance with one carrier can lead to savings of 10% or more.
- Paying in Full: If you can pay your annual premium upfront instead of in installments, most insurers offer a discount.
- Safety Features: Vehicles with backup cameras, anti-lock brakes, and modern airbags often qualify for lower rates.
- Telematics Programs: These programs monitor driving habits and reward safe drivers with lower premiums. They can also provide valuable fleet management data.
- Professional Associations: Check if your chamber of commerce or trade organization has negotiated group insurance rates.
- Driver Training: Investing in defensive driving courses for your employees demonstrates a commitment to safety that insurers reward with lower rates.
Affordable commercial auto insurance is about being smart with your choices, not cutting corners on protection.
Frequently Asked Questions
When business owners in Victorville, Hesperia, and across Southern California sit down with us to discuss their insurance needs, certain questions come up again and again. These are the real concerns keeping entrepreneurs up at night – the practical stuff that matters when you’re trying to protect your livelihood while keeping costs manageable. Let me share the answers to the most common questions we hear about affordable commercial auto insurance.
Is commercial auto insurance more expensive than personal auto?
Yes, commercial auto insurance typically costs more than a personal policy, and for good reason. Commercial vehicles face higher risk exposure—they’re on the road more, carry heavier loads, and operate in busy areas.
Policies also require higher liability limits, often $500,000 to $1,000,000, to properly protect your business assets from a major lawsuit. While personal policies have lower limits, they are insufficient for business risks.
Quotes typically range from $1,200 to $2,400 per vehicle annually, though about 44% of small businesses pay under $1,500 per year. This shows that affordable commercial auto insurance is achievable. The extra cost protects against business-specific risks that personal policies don’t cover.
Are my tools and equipment covered?
No, your commercial auto insurance policy generally does not cover tools, equipment, or cargo inside your vehicle. The policy protects the vehicle itself and covers liability from accidents, but the contents are excluded.
For example, if tools are stolen from your work van, your auto policy would cover a broken window but not the stolen items. To protect your gear, you need a separate inland marine insurance policy, which is designed for property that moves with you. A Business Owner’s Policy (BOP) may also offer some coverage, but it’s crucial to confirm the limits and ensure your valuable equipment is properly insured.
Can I get a policy for just one vehicle?
Absolutely. Commercial auto insurance is not just for large fleets. We work with many sole proprietors and small businesses that only need to insure a single work vehicle.
Whether you’re a contractor with one truck, a freelance photographer, or a consultant driving to client meetings, you need proper commercial coverage if the vehicle is used for business.
Commercial auto policies are scalable. You can start with one vehicle and easily add more as your business grows. We specialize in finding affordable commercial auto insurance for single-vehicle businesses, ensuring you get robust protection without overpaying.
Conclusion: Secure Your Business with the Right Coverage
Finding the right commercial auto insurance doesn’t have to be a challenge. The key takeaway is clear: if your business uses vehicles, affordable commercial auto insurance is essential for protecting everything you’ve built. You now understand the key differences between policies, what’s covered, and how to find coverage that fits your budget.
Balancing cost and protection is the goal. You need robust coverage to shield your business from financial loss, but with premiums that fit your budget. This balance comes from making informed choices, not cutting corners.
Here at ISU Insurance Services ARMAC Agency, we understand the challenges facing businesses in Victorville, Apple Valley, and the High Desert. Our ISU Armac value proposition is simple: we work for you, not an insurance company. By shopping multiple carriers, we provide genuine options, comparing coverage, cost, and reliability to find your perfect match.
We specialize in finding affordable commercial auto insurance without sacrificing protection. We take the time to understand your unique business before shopping the market on your behalf.
You don’t have to steer the complex insurance landscape alone. We’re here to translate policy language, explain your options, and help you make confident decisions.
Ready to find peace of mind with a policy that fits your budget? Let’s work together to Find the best business auto insurance for your needs. Your business deserves protection that works as hard as you do.