
You sit down to review expenses at the end of a long week. Payroll is up, supply costs never seem to settle down, and the insurance renewal sitting in your inbox looks familiar enough that it's tempting to sign and move on. That's exactly where many practice owners in Victorville make expensive mistakes.
A dental office isn't just a treatment space. It's a workplace, a professional service business, a property risk, and in many cases a small employer trying to stay competitive in the High Desert labor market. If your quote only handles one of those problems, you're underinsured. If it bundles the wrong things, you're overpaying.
The right approach to dentist office insurance quotes in Victorville is simple. Stop treating insurance like a generic office expense and start treating it like part of your operating system. A local independent agency can help you sort out what belongs in your package, what can be removed, and where California rules hit harder than many dentists expect.
Table of Contents
- Protecting Your Victorville Practice Beyond the Chair
- The Core Insurance Your Victorville Dental Practice Needs
- Advanced Protection Optional Coverages to Consider
- How to Prepare for Your Insurance Quote Request
- Comparing Quotes and Choosing a Victorville Agent
- Smart Strategies to Lower Your Insurance Premiums
- Victorville Dentist Insurance FAQ and Next Steps
Protecting Your Victorville Practice Beyond the Chair
A lot of dentists start with the wrong question. They ask, "What's the cheapest quote I can get?" The better question is, "What would hurt this practice most if something went wrong?"
A Victorville dental office has several pressure points at once. A patient slips near the front desk. A sterilization issue leads to a professional liability claim. A compressor fails and disrupts the schedule. A staff injury triggers a workers' compensation issue. None of those events care whether your policy language looked fine at renewal.
That's why a generic office package usually misses the mark. Dental practices have equipment, clinical exposure, patient traffic, employment obligations, and revenue that depends on keeping the doors open. If you're shopping dental office insurance options for Victorville practices, your quote should reflect how your office runs, not how a basic retail business runs.
What local owners often miss
Many practice owners already carry some insurance, but they haven't reviewed whether the pieces fit together. They have one policy for the office, another for malpractice, and maybe an old add-on that no longer matches current operations.
Practical rule: If your insurance was built around your practice from three years ago, it's probably wrong for the practice you run today.
Victorville businesses also benefit from local guidance because real conditions matter. Property concerns, staffing realities, lease terms, and California compliance all shape what belongs in your quote. A local independent agency doesn't just pull a number. It helps you identify which exposures deserve protection and which line items should be challenged.
The Core Insurance Your Victorville Dental Practice Needs
If your quote doesn't address the core coverages below, it isn't a real dental practice insurance strategy. It's a patchwork.
Where most quotes go wrong
Some dentists think "office insurance" means everything. It doesn't. Others assume the malpractice policy covers front-office incidents, damaged equipment, and staff injuries. It doesn't do that either.
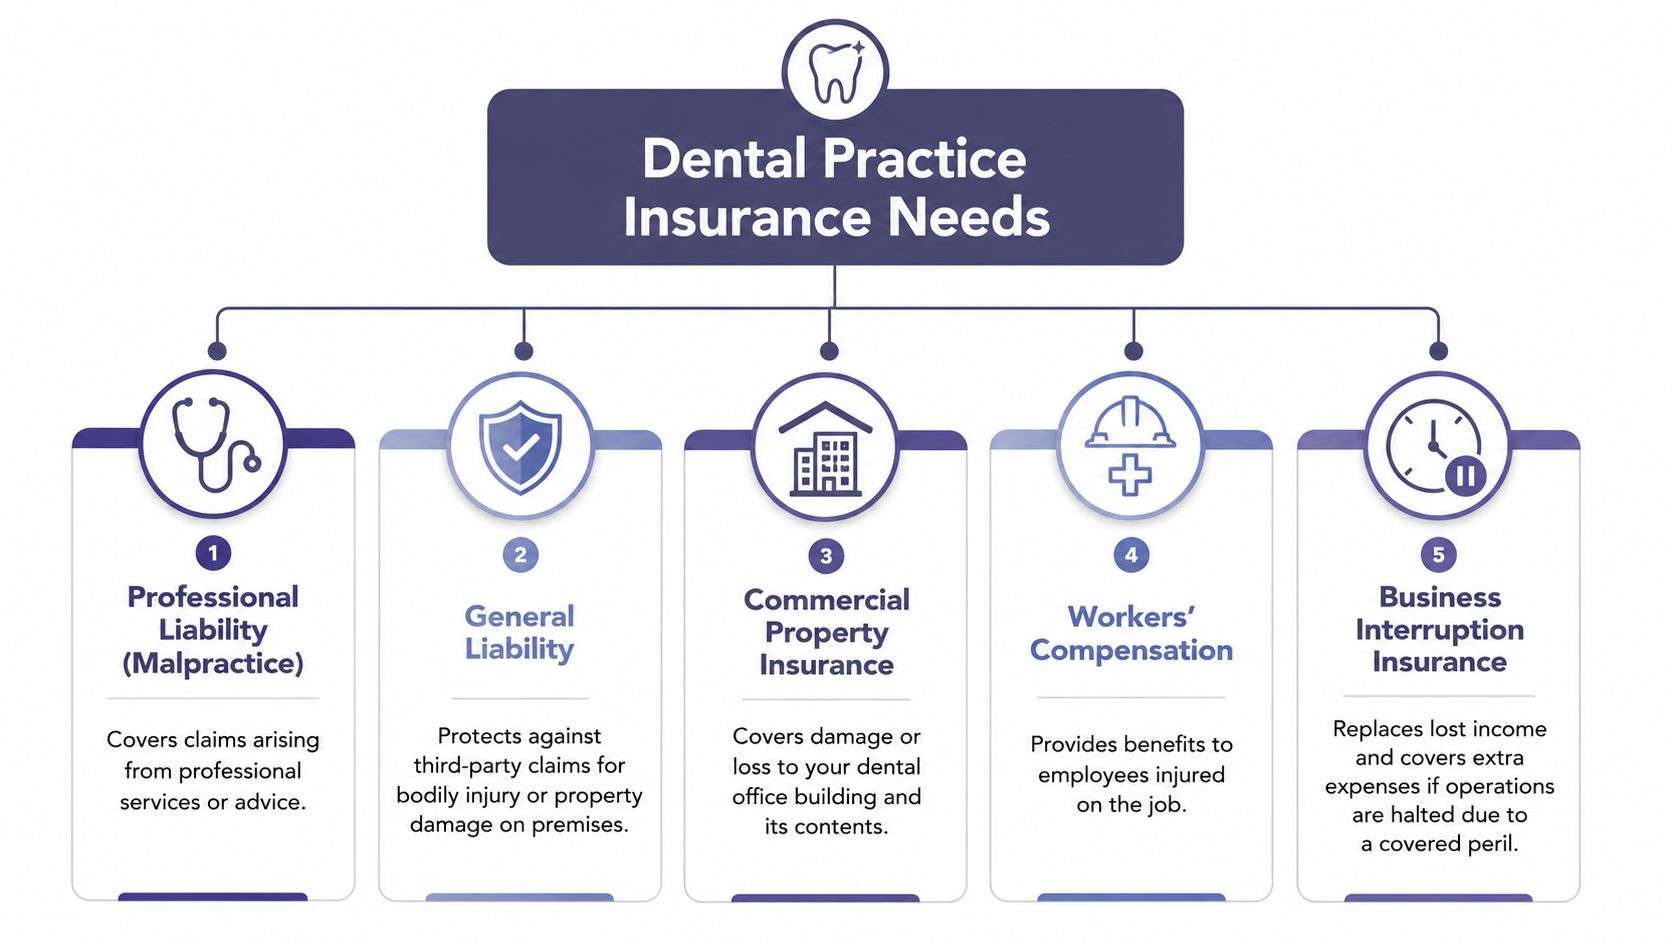
The cleanest way to think about dentist office insurance quotes in Victorville is to separate the risk into functional buckets. Clinical work needs one type of protection. Premises risk needs another. Employee injuries are their own category. Income loss from a shutdown needs separate attention.
For malpractice specifically, California pricing gives you a useful benchmark. General dentists in California, including the Victorville region, typically pay between $1,000 and $3,000 annually for standard dental malpractice coverage with limits of $1 million per occurrence and $3 million aggregate, while specialists such as orthodontists may average around $3,287 per year according to California dental malpractice pricing details for Victorville dentists and dentist malpractice insurance in Victorville.
The non-negotiable policies
Professional liability
This is malpractice coverage. It responds to claims tied to your professional services, treatment decisions, and clinical outcomes. If you perform dentistry, this is not optional.
Those typical California limits of $1 million per occurrence and $3 million aggregate are the standard baseline tied to the pricing benchmark above. For many general practices, that's the starting point for serious discussion, not an afterthought.
General liability
This covers third-party bodily injury and property damage unrelated to the quality of dental treatment itself. If a patient trips in the waiting room or a delivery person gets hurt on your premises, this is the coverage that comes into play.
A dentist's office has more visitor traffic than many small businesses. That alone makes general liability a basic requirement.
Commercial property coverage
Your office contains expensive business property. Chairs, imaging equipment, instruments, computers, cabinetry, and tenant improvements all need to be valued properly. If your quote uses rough guesses, you risk underinsuring the space.
A low premium built on weak property values isn't savings. It's deferred pain.
Workers' compensation
If you have employees in California, workers' compensation needs to be handled correctly. Dental assistants, hygienists, front-office staff, and other team members all create payroll-based exposure. If someone gets injured doing job-related work, this coverage matters immediately.
Business interruption coverage
A dental office that can't operate doesn't just lose time. It loses scheduled procedures, hygiene revenue, and patient continuity. Business interruption coverage can help replace lost income and cover extra expense when a covered event shuts you down.
Here's the short version:
| Coverage | What it protects | Why it matters in a dental office |
|---|---|---|
| Professional liability | Clinical claims | Treatment-related exposure is central to the business |
| General liability | Premises and third-party injury | Patients and vendors move through the office daily |
| Commercial property | Building contents and equipment | Dental equipment is costly to replace |
| Workers' compensation | Employee injury claims | California compliance and staff protection |
| Business interruption | Lost income after a covered shutdown | Your schedule is your revenue engine |
Advanced Protection Optional Coverages to Consider
Optional coverage isn't fluff when it solves a real problem. In modern dental practices, some "optional" policies are effectively the next layer of responsible planning.
Digital risk is now a business risk
Dental offices handle patient information, scheduling systems, billing data, and internal communications across connected systems. If those systems are interrupted or compromised, the problem isn't technical. It's operational.
Cyber liability is worth serious attention for any practice using digital records and electronic workflows. It can be especially relevant when you're trying to account for privacy exposure, system downtime, and the cost of responding to an incident. If you're evaluating cyber liability insurance for business operations, don't treat it like an add-on for larger companies. Small offices feel cyber disruption faster because they don't have much slack in the schedule.
Another optional coverage that deserves more attention is business interruption if it wasn't built into your package already. Fires, property damage, and other covered disruptions don't just create repair bills. They interrupt production.
Benefits can strengthen retention
Hiring is difficult when you need reliable front-office staff, assistants, and clinical support. Benefits matter more than many small practices admit.
Recent data shows that 68% of California small businesses with 10 to 49 employees now add stand-alone dental benefits to retain talent, as noted in California small business dental benefits data. That's important because many local discussions around "dental insurance" focus on patient financing or patient care plans, not employer-side benefit strategy.
If you're trying to keep a good employee, compensation gets attention first. Benefits usually decide whether they stay.
There's also a common confusion worth clearing up. Patient discount plans are not the same thing as business insurance. One local example, the Smile Generation Dental Discount Plan, offers 20% to 50% discounts, has no deductibles or copays, and excludes annual maximums, but it is not insurance, according to details on the Smile Generation Dental Discount Plan. That's a patient savings arrangement. It doesn't replace commercial liability, property, workers' compensation, or malpractice coverage for your office.
How to Prepare for Your Insurance Quote Request
A clean quote starts with clean information. If you hand an agent incomplete details, you'll get a vague estimate, extra follow-up, and higher odds of fixing mistakes later.
Bring the right information the first time
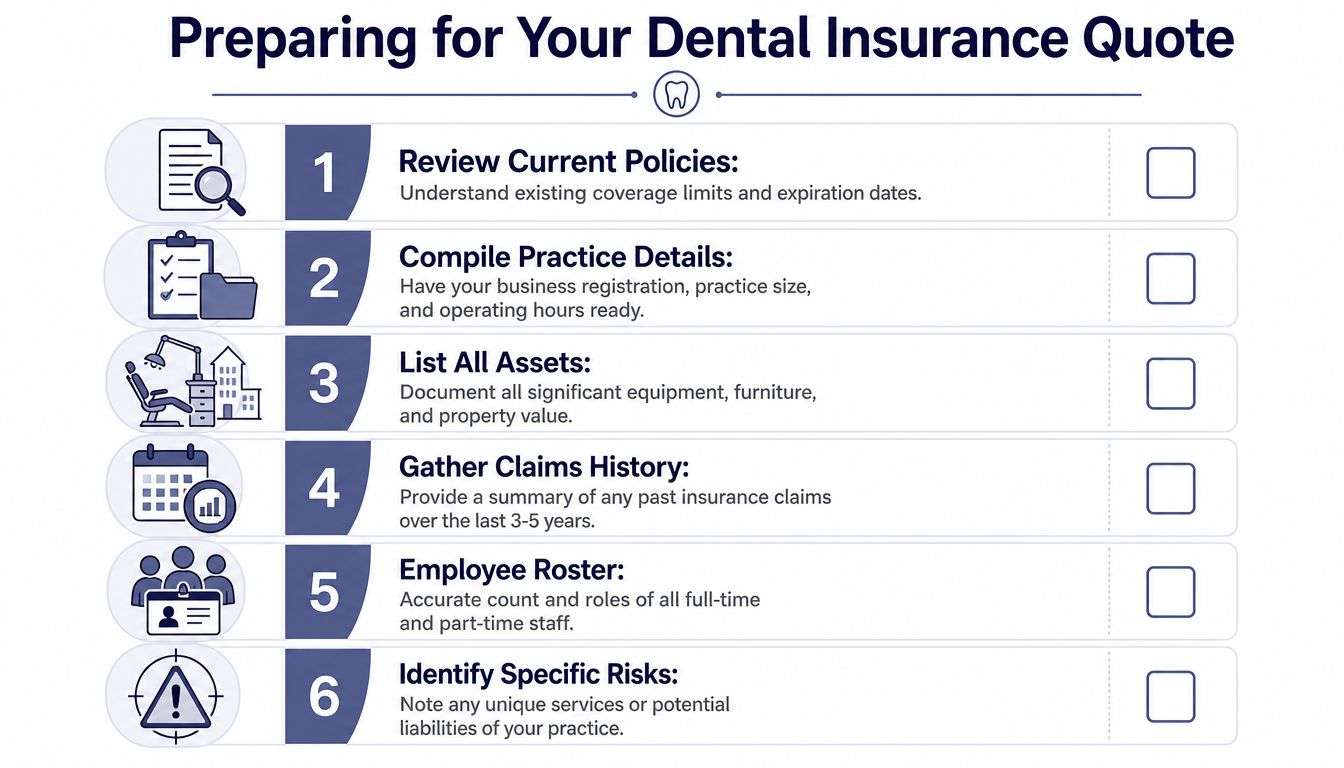
Before you ask for dentist office insurance quotes in Victorville, gather the basics in one folder:
- Business identity: Legal business name, entity type, business address, and tax ID.
- Practice snapshot: Number of operatories, office square footage, and whether you own or lease the space.
- Revenue and payroll: Current annual revenue and payroll broken out by role if possible.
- Employee roster: List your hygienists, assistants, administrative staff, and any part-time team members.
- Current policies: Renewal dates, limits, deductibles, and known endorsements.
- Claims history: Prior claims and near-misses that could affect underwriting.
This isn't busywork. It keeps the quote tied to your actual operation instead of assumptions.
What underwriters want to understand
Underwriters usually want a clear picture of what you do, how often you do it, and how you control risk. Help them out.
Start with procedures. A practice focused on routine general dentistry doesn't present the same profile as a practice that handles more advanced or specialty work. Then show your controls. Document sterilization procedures, staff training, complaint handling, maintenance routines, and any security measures protecting the office and patient data.
Use this quick pre-flight check before the first call:
- Review coverage gaps: Know what your current package doesn't handle.
- Confirm property values: Equipment and improvements should be based on realistic replacement needs.
- Organize loss records: Missing claim details slow everything down.
- List special services: Sedation, specialty referrals, or expanded procedures affect underwriting.
- Check lease requirements: Landlords often require specific limits or endorsements.
- Name decision makers: Make sure the person requesting the quote can answer operational questions.
A strong submission doesn't just speed up quoting. It often leads to a more accurate premium because the underwriter isn't forced to price uncertainty.
Comparing Quotes and Choosing a Victorville Agent
Once the quotes come in, ignore the urge to sort by premium and call it a day. That's how dentists buy policies that look fine on paper and disappoint the first time a claim appears.
Cheap isn't always usable
Read quotes in layers. First, confirm that each quote covers the same policy types. Then compare limits, deductibles, sublimits, and exclusions. A lower premium may reflect narrower property coverage, weaker business interruption terms, or missing endorsements.
Use these questions when reviewing any quote:
- What's excluded: Ask what common dental office scenarios are not covered.
- How is property valued: Replacement cost and stated values need to be clear.
- Is business interruption included: Don't assume it is.
- How are employees classified: Workers' compensation errors usually start here.
- What triggers the malpractice form: Claims-made details and retroactive handling need attention.
If an agent can't explain those items in plain English, move on.
Why local agency knowledge matters
A Victorville dental practice doesn't need generic advice from someone who only sees a spreadsheet. It needs someone who understands local business conditions, California compliance, and how dental offices are insured.
One useful local fact is straightforward. ISU Insurance Services – Armac Agency is a BBB Accredited Business located at 17177 Yuma St, Victorville, CA 92395-5886, and it offers workers' compensation and general liability coverage designed for California small and mid-sized businesses, according to the BBB profile for the Victorville agency. That's relevant because physical presence matters when you want in-person review, document follow-up, and someone who knows the High Desert business environment.
For a dentist, the agent selection process should be blunt:
| Question to ask | Why it matters |
|---|---|
| Have you quoted dental practices before? | Dental risk isn't the same as standard office risk |
| How do you handle property valuation? | Equipment mistakes create claim problems |
| What California compliance issues should I watch? | Workers' compensation and liability details matter |
| Can you help bundle multiple lines? | Better structure can reduce waste |
| Will you review my current policy line by line? | Real advice starts with identifying overlap and gaps |
If you want one local option to review, quote, and compare through an independent agency model, [object Object] fits that role.
Smart Strategies to Lower Your Insurance Premiums
Lower premiums come from better risk presentation, not wishful thinking. If you want the market to take your practice seriously, run it like a disciplined business.
Cut risk before you ask for a lower rate
The easiest premium to reduce is the one tied to preventable problems.
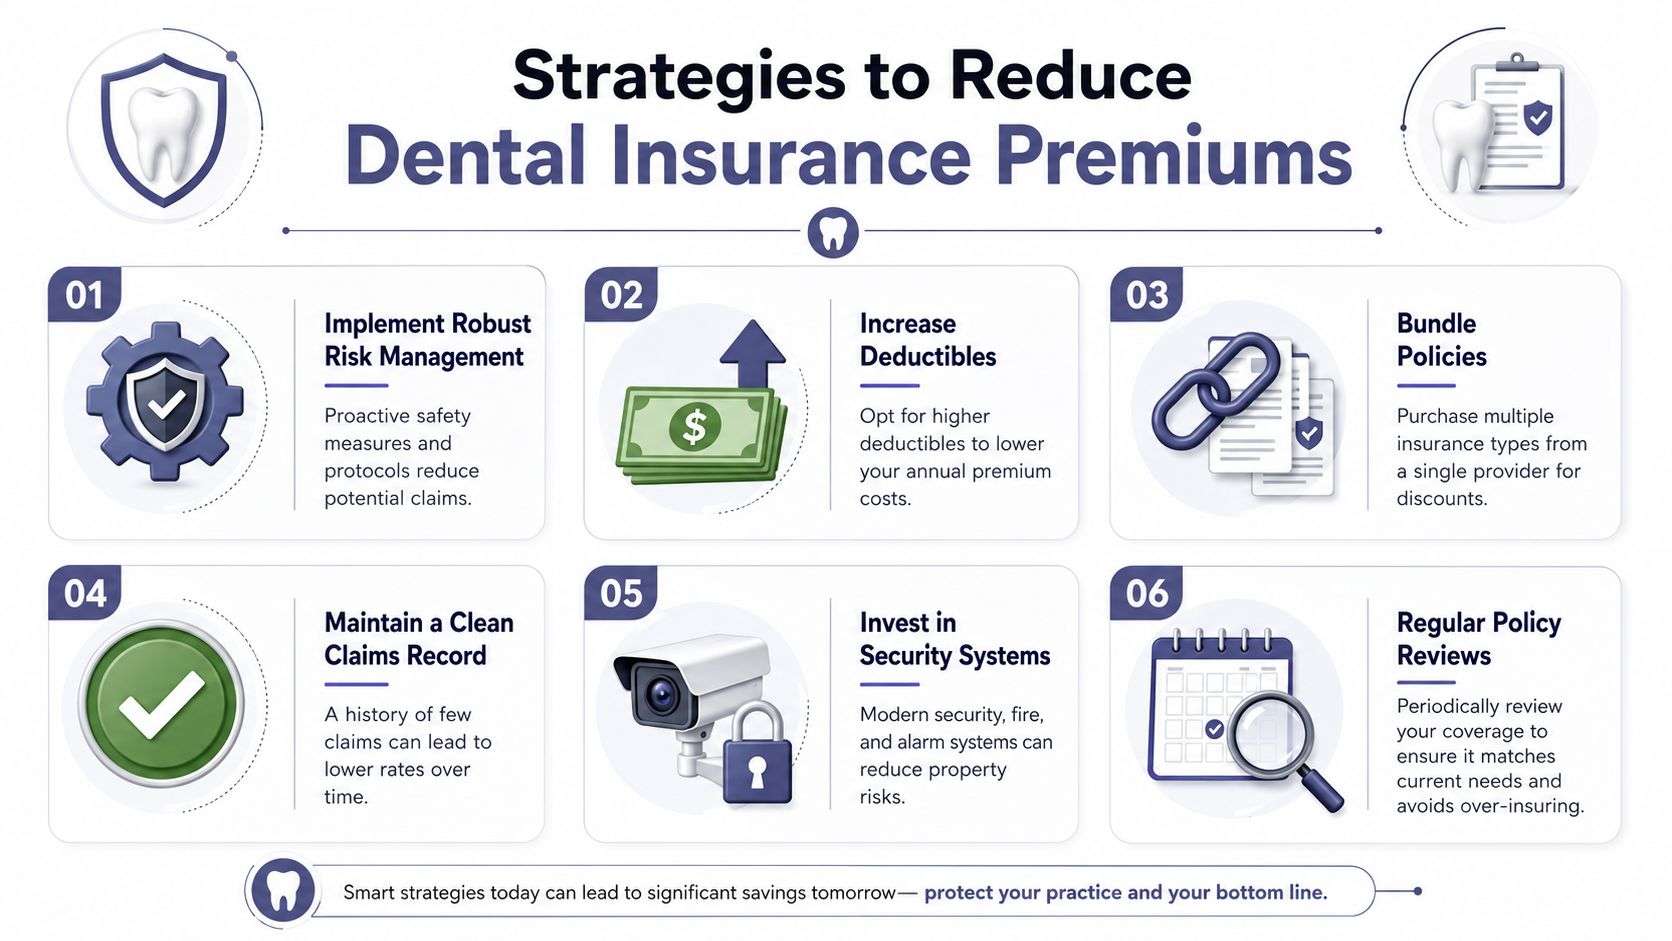
- Train your staff consistently: Safety habits, patient communication, and incident reporting reduce avoidable claims.
- Review procedures regularly: If your scope of work changes, update the policy before renewal.
- Bundle intelligently: Property, liability, and related lines often make more sense when coordinated through one plan.
- Increase deductibles when appropriate: This isn't right for every office, but it can lower annual premium when cash flow can absorb a higher out-of-pocket loss.
- Keep your claims history clean: Small preventable incidents can raise costs later.
A lot of savings also come from deleting stale coverage. Practices evolve. Old endorsements and outdated property schedules stay on the books longer than they should.
Victorville property concerns deserve attention
Property insurance in the High Desert shouldn't be approached casually. Local environmental conditions can affect pricing and underwriting decisions. That's one reason accurate building details, maintenance records, and safety measures matter so much.
A relevant local point is that ISU Armac is an authorized agent for Mercury Insurance, a California-based carrier that specializes in high-risk and fire-prone areas like Victorville and offers home insurance designed for high fire risk zones, according to the agency's Victorville insurance overview. Even if your dental office quote isn't a home policy, that local fire-risk awareness tells you something important. Property exposure in this region deserves careful review, not boilerplate assumptions.
Review your insurance the same way you review equipment maintenance. Small neglect turns into expensive failure.
Victorville Dentist Insurance FAQ and Next Steps
Quick answers for common insurance questions
Is a patient dental discount plan the same as dentist office insurance?
No. A patient discount plan helps patients reduce their out-of-pocket dental care costs. It does not insure your business against liability claims, property loss, employee injuries, or malpractice exposure.
Do I need both malpractice and general liability?
Yes. They solve different problems. Malpractice addresses professional services. General liability addresses third-party injury and property damage that happen around the business.
Should owner-dentists be included in workers' compensation?
This depends on how the business is structured and how California rules apply to your specific setup. Don't guess. Ask for a formal review tied to your entity type and payroll setup.
How often should I review my policies?
At minimum, review them at renewal and any time your practice changes meaningfully. Expansion, equipment purchases, staffing changes, new procedures, and lease changes all justify an immediate look.
What makes a quote accurate?
Accurate payroll, realistic property values, clear procedure lists, and complete claims history. Incomplete submissions usually produce misleading pricing.
Can I meet with someone locally instead of handling everything online?
Yes. The local team at ISU Insurance Services, including experienced agents, can be reached at (760) 241-7900 for personalized insurance service with in-person appointment options at their Victorville office, according to the agency contact listing for Victorville appointments.
The team also includes Dean Rickard, Kimberly Stockton, and Panadda Lampi, all reachable through that same office number. If you prefer sitting across the desk from someone and walking through your policies line by line, that's still available in Victorville.
The bottom line is simple. Dentist office insurance quotes in Victorville should be built around how your practice operates. If the quote is vague, generic, or missing key categories, don't accept it just because it came in fast.
If you want a practical review of your current coverage, a second opinion on a renewal, or a fresh quote built around your practice, contact ISU Insurance Services. A local independent agency can help you sort out what belongs in the package, what should be removed, and how to structure coverage that protects the business without paying for clutter.